
Aerospace and Defense Materials Market Size, Competitive Landscape Analysis Report 2035
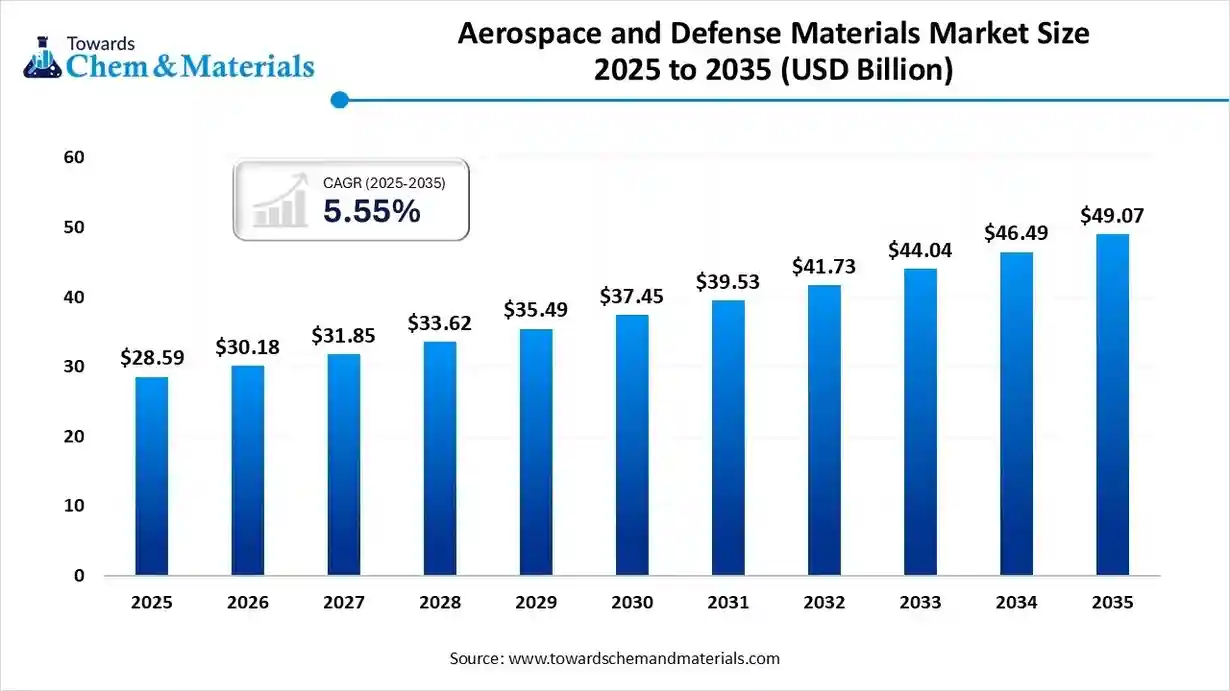
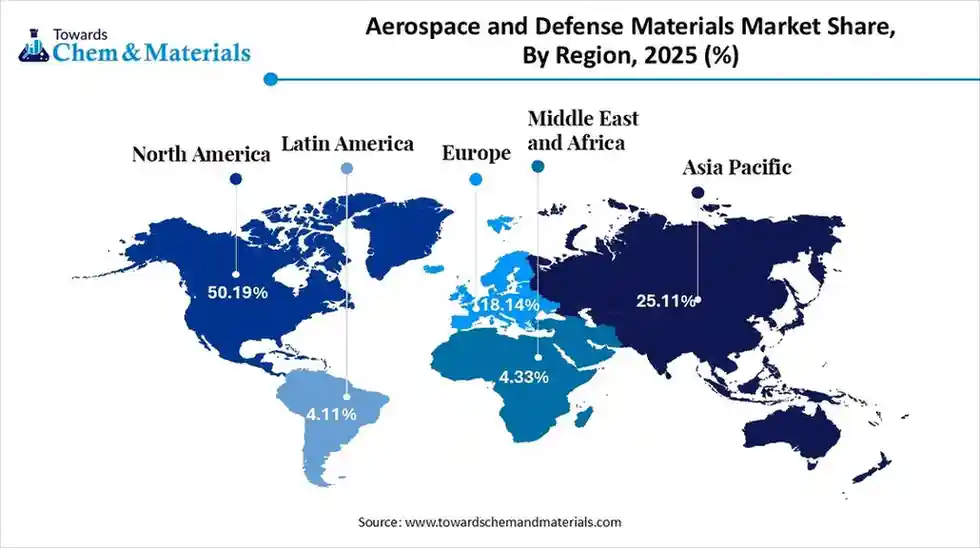
The global aerospace and defense materials market size is calculated at USD 28.59 billion in 2025 and is predicted to increase from USD 30.18 billion in 2026 and is projected to reach around USD 49.07 billion by 2035, The market is expanding at a CAGR of 5.55% between 2026 and 2035. Asia Pacific dominated the aerospace and defense materials market with a market share of 50.19% the global market in 2025. The strong focus of airlines on lowering carbon emissions and the rise in air passenger traffic drive the market growth,
Key Takeaways
- North America dominated the aerospace and defense materials market with a revenue share of 50.19% in 2025.
- By material type, the metals & alloys segment led the market and accounted for 45% of the global revenue share in 2025.
- By aircraft type, the commercial aircraft segment accounted for the largest revenue share of 44% in 2025.
- By property, the lightweight & high strength materials segment dominated with the largest revenue share of 42% in 2025.
- By end-use sector, the commercial aviation OEMs segment dominated the market and accounted for the largest revenue share of 37% in 2025.
- By distribution channel, the direct supply segment accounted for the largest market revenue share of 55% in 2025.
What is Driving the Future of Aerospace and Defense Materials?
The aerospace and defense materials market is experiencing rapid growth, driven by a rise in global air travel, the modernization of military equipment, increased defense budgets, innovations in aircraft designs, a focus on modernizing military fleets, and increasing investment in space programs. The strong focus of manufacturers and airlines on the development of fuel-efficient vehicles increases demand for lightweight materials to enhance safety and improve performance.
The growing government investment in domestic defense capabilities & the manufacturing of aerospace, and rising spending on defense equipment, military aircraft, & weapon systems, leads to higher demand for stealth & high-strength materials.
What are Aerospace and Defense Materials?
Aerospace and defense materials are advanced materials that have been developed to meet the extreme performance requirements of military equipment, aircraft, and spacecraft. These material has high durability, corrosion resistance, strength-to-weight resistance, fatigue resistance, and heat resistance. The diverse materials used in aerospace and defense applications are composite, polymeric, metallic, and ceramic.
In aerospace applications, the specialized or advanced material is used in spacecraft, airframes, aircraft structures, & engines, whereas in defense applications is used in defense systems, radar, military aircraft, satellites, and armored vehicles.
Aerospace and Defense Materials Market Trends:
- Growing Commercial Aviation:- The growing middle-class population globally and the expansion of the economy, particularly in the Asia Pacific, increase demand for commercial aviation. The rise in air travel supports fleet renewal and the modernization of airlines, which increases the adoption of advanced aircraft. The growing international tourism and increasing government investment in airport infrastructure increase demand for commercial aviation. For instance, Air India ordered over 500 new aircraft from Boeing & Airbus to modernize its fleet with fuel-efficient planes.
- Defense System Modernization:- The geopolitical tensions, unresolved border disputes, and growing budgets of defense increase the modernization of defense systems, which fuels demand for advanced materials. The modernization of military vehicles, infrastructure, equipment, and aircraft requires advanced materials to enhance survivability and performance.
- Shift Towards Lightweight Materials:- The strong emphasis on enhancing fuel efficiency, lowering GHG emissions, and enhancing the performance of military and commercial aircraft increases demand for lightweight materials. The materials like carbon fiber-reinforced polymers and advanced titanium & aluminum alloys lower the weight of aircraft and offer a high strength-to-weight ratio. The stricter regulatory pressures and growing environmental concerns are leading to a shift towards lightweight materials.
- Additive Manufacturing:- The strong focus of aircraft manufacturers to lower waste of materials and create complex parts increases demand for additive manufacturing. The growing development of lighter parts and focus on rapid customization of components requires additive manufacturing. Parts like engine components, drone components, interior parts, thrust chambers, RF antennas, customized spares, satellite structures, and many more are created using additive manufacturing.
Report Scope
| Report Attribute | Details |
| Market Size Value in 2026 | USD 30.18 Billion |
| Revenue Forecast in 2035 | USD 49.07 Billion |
| Growth Rate | CAGR 5.55% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Dominant Region | North America |
| Fastest Growing Region | Asia Pacific |
| Segments covered | By Material Type, By Aircraft / Platform Type, By Property / Material Performance Requirement, By End-Use Sector, By Distribution Channel, By Region |
| Key companies profiled | Allegheny Technologies, Cytec Solvay Group, Hexcel Corporation, Novelis, Constellium N.V, SGL Carbon, thyssenkrupp Aerospace, Formosa Plastics Corporation, U.S.A, Strata Manufacturing PJSC, Teijin Limited |
Key Technological Shifts in the Aerospace and Defense Materials Market:
The technological innovation in aerospace and defense materials focuses on the development of heat-resistant, lightweight, and stronger parts using advanced materials. The key technological innovations include nanomaterials use, 3D printing, digitalization, electrification, and hypersonic technologies support the development of new generation defense and aircraft systems.
One of the major transformations is the integration of artificial intelligence to optimize manufacturing processes and enhance the performance of materials.
AI analyzes large datasets of materials and identifies new composite or alloy materials for the development of aircraft and spacecraft parts. AI creates durable & lightweight components and predicts engine or system failures. AI detects surface defects, microscopic cracks, & other defects, and also optimizes flight paths to lower consumption of fuel.
Artificial Intelligence performs tasks like assembly, drilling, and painting to accelerate production timelines, enhance consistency, and minimize errors. AI develops autonomous systems to perform tasks like engaging targets & tracking. However, AI is redefining the aerospace and defense materials industry by offering the highest quality standards, managing complexity, and providing safety.
Trade Analysis of Aerospace and Defense Materials Market: Import & Export Statistics
- France exported $44.7B of aircraft and spacecraft.
- India exported 19226 shipments of aluminum alloys.
- Russia exported 11640 shipments of titanium alloys.
- India exported 1077 shipments of glass fiber reinforced plastic.
- China exported 9423 shipments of elastomers.
- The United States exported $25.9B of aircraft parts.
Aerospace and Defense Materials Market Value Chain Analysis
- Feedstock Procurement :The feedstock procurement is the process of sourcing & acquiring raw materials like titanium alloy, copper, nickel, aluminum alloy, tungsten, carbon fiber-reinforced polymers, and glass fiber composites to manufacture military systems, aircraft, and spacecraft.
- Key Players: Alcoa Corporation, Constellium SE, Mishra Dhatu Nigam, ATI, Hexcel Corporation
- Quality Testing and Certifications :Quality Testing involves diverse tests like fatigue, vibration, thermal stability, fluid susceptibility, and non-destructive testing to ensure components meet performance & stringent safety. Certifications like NANDCAP, AS9100, and AMS ensure material safety and performance.
- Key Players: SGS SA, Applus+ Laboratories, Element Materials Technology, Intertek Group plc
- Regulatory Compliance and Safety Monitoring :Regulatory compliance ensures operational integrity, high levels of safety, & national security through quality management systems, environmental regulations, & airworthiness standards. Safety monitoring involves documentation, incident investigation, testing, and data analysis to ensure the functionality of systems, materials, and components.
- Key Players: DEKRA, SGS SA, Element Materials Technology, TÜV SÜD, Bureau Veritas
Classification of Key Aerospace and Defense Materials Category
| Type | Examples | Used in |
| Metals |
|
|
| Composites |
|
|
| Polymers |
|
|
| Ceramics |
|
|
Segmental Insights
Material Type Insights
Why the Metals & Alloys Segment Dominates the Aerospace and Defense Materials Market?
The metals & alloys segment dominated the aerospace and defense materials market with approximately 45% share in 2025. The high strength-to-weight ratio, temperature resistance, and fatigue resistance of metals & alloys help market growth. The growing manufacturing of high-stress components like bulkheads, engine parts, fuselages, and landing gear increases demand for metals & alloys. The presence of titanium alloys, steel alloys, aluminum alloys, and nickel-based superalloys drives the market growth.
The composites segment is the fastest-growing in the market during the forecast period. The strong focus on enhancing the fuel efficiency of vehicles and increasing the payload in aircraft increases the adoption of composites. The growing demand for enhancing the performance of military & commercial fleets and lower maintenance costs increases demand for composites. The development of modern aircraft supports the overall market growth.
The ceramics & ceramic matrix composites segment is growing significantly in the market. The strong focus on lowering emissions and improving the efficiency of aerospace increases demand for ceramics & ceramic matrix. The presence of superior wear & corrosion resistance and the lightweight of ceramics helps market growth. The development of military aircraft and commercial airlines requires ceramic matrix, supporting the overall market growth.
Aircraft Type Insights
How did the Commercial Aircraft Segment hold the Largest Share in the Aerospace and Defense Materials Industry?
The commercial aircraft segment held the largest revenue share of approximately 40% in the aerospace and defense materials industry in 2025. The growing modernization of the fleet and the development of cargo aircraft increase demand for advanced materials. The rising air travel and expansion of the fleet require materials like metals, composites, & metals. The strong focus on enhancing the fuel efficiency of aircraft and the presence of maintenance, repair, and overhaul services drive the market growth.
The spacecraft & launch vehicles segment is experiencing the fastest growth in the market during the forecast period. The growing commercial space sector and rapid deployment of satellite constellations require advanced materials. The increasing investment in space exploration programs and the growing demand for space-based services help market growth. The presence of private space companies like Rocket Lab, SpaceX, and Blue Origin supports the overall market growth.
Additionally, the military aircraft segment is growing significantly in the market. The growing modernization of military forces and the development of modern military aircraft require advanced materials. The strong focus on lowering the aircraft’s radar cross-section and the development of fuel-efficient military aircraft drive the market growth.
Property Insights
Why the Lightweight & High Strength Materials Segment is Dominating the Aerospace and Defense Materials Market?
The lightweight & high strength materials dominated the aerospace and defense materials market with approximately 42% share in 2025. The strong focus on enhancing the fuel efficiency of aircraft and lowering maintenance costs increases the adoption of lightweight materials. The focus on increasing the payload capacity of aircraft and the development of next-generation satellites & aircraft increases the adoption of high strength & lightweight materials, supporting the overall market growth.
The high-temperature & thermal-resistant materials segment is the fastest-growing in the market during the forecast period. The increasing need to lower the consumption of fuel and the development of greater engine thrust require high-temperature materials. The extreme operating environments in aircraft and defense vehicles require thermal-resistant materials. The strong focus on enhancing safety in the aerospace and defense sector drives the market growth.
The wear & corrosion resistance material segment is substantially growing in the market. The growing operations of defense systems, aircraft, and spacecraft in harsh conditions and the increasing need for preventing structural failures increase demand for wear resistance materials. The strong focus on enhancing the performance of military & aircraft vehicles and the need to lower MRO costs require wear & corrosion resistant materials, supporting the overall market growth.
End-Use Sector Insights
Which End-Use Sector Held the Largest Share in the Aerospace and Defense Materials Industry?
The commercial aviation OEMs segment held the largest revenue share of approximately 37% in the aerospace and defense materials industry in 2025. The growing expansion of commercial airlines and the modernization of air fleets increases demand for titanium alloys & advanced composites. The increasing global air travel and expansion of e-commerce require commercial aviation. The presence of companies like Embraer, Boeing, and Airbus drives the market growth.
The space agencies & private space companies segment is experiencing the fastest growth in the market during the forecast period. The growing deployment of satellites and exploration of space requires materials like advanced ceramics, titanium alloys, and superalloys. The strong government support for space expansion through ISRO, NASA, & ESA, and the presence of companies like Blue Origin & SpaceX, support the overall market growth.
The defense OEMs segment is growing significantly in the market. The growing terrorist attacks and increasing geopolitical tensions increase the demand for defense OEMs. The rapid growth in defense budgets and the modernization of military fleets increases demand for advanced materials, driving the overall growth of the market.
Distribution Channel Insights
How Direct Supply Segment Dominated the Aerospace and Defense Materials Market?
The direct supply segment dominated the aerospace and defense materials market with approximately 55% share in 2025. The growing customization of aircraft parts and focus on direct collaboration between manufacturers & suppliers increases demand for direct supply. The presence of specialized expertise and focus on streamlining logistics requires direct supply. The greater control over quality and a consistent & stable supply drive the market growth.
The specialized material service centers segment is the fastest-growing in the market during the forecast period. The rigorous testing needs and stricter safety & quality standards increase demand for specialized material service centers. The ability of service centers to manage customization, sourcing, and processing of complex materials helps market growth.
The distributors & tier-2 or tier-3 suppliers segment is substantially growing in the market. The specialization of tier-2 or tier-3 in manufacturing processes, components, and materials helps market growth. The strong focus on managing inventory & logistics and the need to lower lead times requires distributors, supporting the overall market growth.
Regional Insights
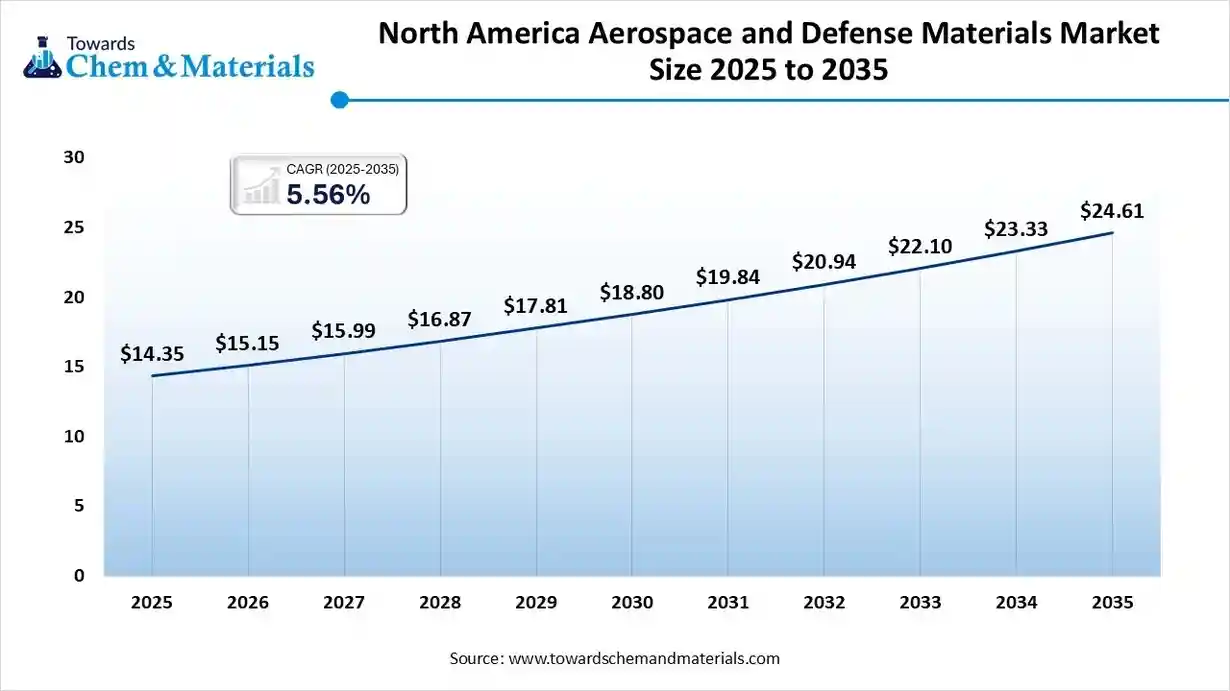
The North America aerospace and defense materials market size was valued at USD 14.35 billion in 2025 and is expected to reach USD 24.61 billion by 2035, growing at a CAGR of 5.56% from 2026 to 2035. North America dominated the market with approximately 50.19% share in 2025.
The growing government spending on fleet modernization, advanced aircraft, and space systems increases demand for aerospace & defense materials. The increasing air travel and development of new commercial aircraft require aerospace materials. The presence of a mature aerospace manufacturing ecosystem and increasing development of new materials like advanced alloys & composites helps market growth. The strong presence of manufacturers like Lockheed Martin and Boeing drives the market growth.
Setting Standards: United States Excellence in Aerospace and Defense Materials
The United States is a key contributor to the aerospace and defense materials market. The growing spending on defense increases demand for advanced materials for the development of military systems, aircraft, & drones. The strong presence of commercial aircraft production and space exploration programs like SpaceX increases demand for advanced materials. The presence of defense contractors and Original Equipment Manufacturers supports the overall market growth.
- The United States exported 58580 shipments of aluminum alloys. (Source: www.volza.com)
Asia Pacific Aerospace and Defense Materials Market Trends:
Asia Pacific is experiencing the fastest growth in the market during the forecast period. The growing modernization of air fleets and the commercial aviation boom increase demand for advanced materials. The growing regional security concerns and geopolitical tensions in countries like Japan, China, & India increase defense spending. The increasing expansion of maintenance, repair, & overhaul facilities and focus on self-reliance in defense production drives the market growth.
Advanced Material: Pillar Behind China Aerospace and Defense Materials
China is a major contributor to the market. The growing modernization of military systems, like next-generation aircraft, advanced flight systems, and avionics, increases demand for advanced materials. The increasing demand for civilian aviation and the rising number of air travel passengers require advanced materials. The high production capacity of composites and titanium supports the overall market growth.
China exported 17698 shipments of aluminum alloys.(Source: www.volza.com)
Europe Aerospace and Defense Materials Market Trends:
Europe is growing at a notable rate in the market. The growing spending on defense in countries like Poland & Germany and the rise in air passenger traffic increase demand for aerospace & defense materials. The development of new commercial aircraft and innovations in cutting-edge technologies requires aerospace materials. The growing maintenance, repair, and overhaul activities and the strong commercial aerospace sector drive the market growth.
Precision Materials: Germany’s Power in the Aerospace and Defense Sector
Germany is growing substantially in the aerospace and defense materials industry. The growing commercial air travel and increasing defense investments require aerospace & defense materials. The increasing defense budget and rising investment in sustainable aviation technologies require aerospace & defense materials. The presence of leading companies like Rheinmetall and Airbus supports the overall market growth.
Middle East & Africa Aerospace and Defense Materials Market Trends:
The Middle East & Africa are growing significantly in the market. The growing investment in modernizing military capabilities in countries like the UAE, Egypt, Saudi Arabia, and Israel increases demand for defense materials. The expansion of civil aviation and a strong focus on creating fuel-efficient civilian & military aircraft require aerospace & defense materials, driving the overall market growth.
United Arab Emirates Aerospace and Defense Materials Market Trends:
The United Arab Emirates is growing substantially in the market. The increasing government investment in defense modernization and the development of aerospace infrastructure requires aerospace & defense materials. The growing fleet sizes and expansion of international & domestic airlines like Etihad & Emirates support the overall market growth.
South America Aerospace and Defense Materials Market Trends:
South America is growing in the market. The growing modernization of naval & air fleets and increasing expansion of civil aviation require materials like alloys & composites. The growing investment in domestic aerospace manufacturing capabilities in countries like Brazil and the well-established commercial aircraft & military industry drives the overall market growth.
From Forest to Flight: Brazil’s Intelligence in Aerospace and Defense Materials
Brazil experiences significant growth in the market. The increasing investment in the defense modernization industry and the expansion of commercial aviation services increase demand for advanced materials. The strong government support through programs like airport privatization and the presence of major aerospace & defense hubs like Sao Paulo support the overall market growth.
Recent Developments
- In September 2025, Aerolloy Technologies launched an advanced superalloy manufacturing facility. The facility enhances India’s self-reliance and lowers the import dependence of defense and aerospace materials. The facility specializes in advanced VIM of large castings & superalloys.(Source: scanx.trade )
- In October 2025, Rajnath Singh inaugurated a titanium and superalloy plant on a 50-acre campus for the defense sector in Lucknow. The plant focuses on manufacturing aviation-grade superalloys & titanium. The material supports the development of missiles, satellites, fighter jets, and naval systems. (Source: currentaffairs.adda247.com)
- In April 2025, Cambium launched a new high-temperature resin system, ApexSheild 1000, for aerospace manufacturers. The system supports the production of rocket nozzle extensions, hypersonic glide bodies, and other components. The system minimizes hypersonic parts fabrication by 70-80% and supports cost-effective production.(Source: www.prnewswire.com)
Top Companies List:
- Huntsman International LLC: The company supplies advanced materials like polyurethane-based resins, epoxy resins, adhesives, and acrylic resins for the aerospace & defense industries.
- Toray Composites America, Inc.: The company produces advanced materials like thermoset prepreg and carbon fiber to support diverse industries like defense, sports equipment, aerospace, automotive, and wind energy.
- VSMPO-AVISMA: The Russian-based company supplies titanium & its alloys to major aircraft manufacturers like Pratt & Whitney, Airbus, and Boeing.
- Arconic Inc.: The company manufactures architectural products, aluminum extrusion, sheets, & plates, and 3D printed aerospace parts to support diverse industries.
- Kobe Steel, Ltd: The Japan-based company supplies advanced aluminum and titanium materials to support aerospace and defense applications like aircraft components, aircraft engines, landing gears, and other structural components.
Other Companies List
- Allegheny Technologies
- Cytec Solvay Group
- Hexcel Corporation
- Novelis
- Constellium N.V
- SGL Carbon
- thyssenkrupp Aerospace
- Formosa Plastics Corporation, U.S.A
- Strata Manufacturing PJSC
- Teijin Limited
Segments Covered
By Material Type
- Metals & Alloys
- Aluminum Alloys
- Titanium Alloys
- Steel & Superalloys
- Composites
- Carbon Fiber Reinforced Polymers (CFRP)
- Glass Fiber Composites (GFRP)
- Aramid Fiber Composites (Kevlar)
- Ceramics & Ceramic Matrix Composites (CMCs)
- Elastomers & Rubber Materials
- Adhesives, Sealants & Coatings
By Aircraft / Platform Type
- Commercial Aircraft
- Military Aircraft
- Helicopters
- UAVs / Drones
- Spacecraft & Launch Vehicles
- Naval & Marine Defense Platforms
By Property / Material Performance Requirement
- Lightweight & High Strength
- High-Temperature & Thermal Resistance
- Wear & Corrosion Resistance
- Impact & Ballistic Resistance
- Electrical & EMI Shielding Properties
- Fire-Resistant & Low-Smoke Materials
By End-Use Sector
- Commercial Aviation OEMs
- Defense OEMs
- MRO (Maintenance, Repair & Overhaul)
- Space Agencies & Private Space Companies
- Defense Vehicle Manufacturers (land & naval)
By Distribution Channel
- Direct Supply (OEM Contracts)
- Distributors & Tier-2/Tier-3 Suppliers
- Specialized Material Service Centers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.