
Paints and Coatings Market Size Analysis Report 2035
The global paints and coatings market size was valued at USD 225.85 billion in 2025, is estimated to reach USD 239.06 billion in 2026, and is projected to reach USD 398.78 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.85% over the forecast period from 2026 to 2035. In terms of volume, the paints and coatings industry is projected to grow from 75.97 million tons in 2025 to 123.16 million tons by 2035. growing at a CAGR of 4.95% from 2026 to 2035. Asia Pacific dominated the paints and coatings industry with the largest revenue share of 46% in 2025,reaching USD 103.89 billion, up from USD 109.97 billion in 2026.The global shift towards better infrastructure and durability.

The manufacturing products that are primarily applied on the surface for protection, durability, and decoration are known as paints and coatings. Also, the industries such as construction, industrial equipment, and furniture have allowed stakeholders to capitalize on growth opportunities in recent years. Furthermore, regions like the Asia Pacific and North America have seen heavy production and exports over the years.
Also, governments in many countries are investing heavily in transportation systems, residential housing, smart cities, and manufacturing industries, which is increasing demand for decorative and protective coatings. The automotive industry is also supporting market growth because electric vehicle production and lightweight vehicle manufacturing require advanced coating solutions. Furthermore, industries are increasingly adopting eco-friendly and low-VOC coatings due to strict environmental regulations and rising sustainability awareness.
Furthermore, the water-based coatings, powder coatings, and bio-based raw materials are becoming more popular in recent years because companies are focusing on reducing harmful emissions and improving environmental performance. Technological advancements such as self-cleaning coatings, anti-corrosion coatings, heat-resistant coatings, and smart coatings are also creating new opportunities for manufacturers.
Market Highlights
- By region, Asia Pacific dominated the market with a share of 46% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 6.8% in the forecast period, due to governments across the region investing heavily in smart cities, transportation systems, housing projects, and industrial development, which is creating strong demand for decorative and industrial coatings.
- By region, North America is notably growing with 22% market share in 2025, owing to technological innovation, sustainable coating development, and strong industrial modernization activities.
- By resin type, the acrylic resins segment dominated the market with 31% share in 2025, as acrylic-based coatings offer excellent durability, weather resistance, color retention, and fast drying properties.
- By resin type, the polyurethane resins segment held the 13% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.8% in the forecast period, owing to its superior durability, flexibility, chemical resistance, and abrasion protection properties.
- By technology, the waterborne coatings segment dominated the market with 42% share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.9% in the forecast period, as these coatings are environmentally friendly, low in volatile organic compound emissions, and safer for users compared to traditional solvent-based products.
- By application, the architectural segment dominated the market with 35% share in 2025, as strong demand from residential, commercial, and infrastructure construction activities worldwide.
- By application, the protective coatings segment held the 10% market share in 2025 and is expected to be the fastest-growing segment in the market, with a CAGR of 6.4% in the forecast period, due to industries are increasingly focusing on equipment durability, corrosion prevention, and long-term infrastructure protection.
Trends in the Paints and Coatings Market
- The heavy demand for sustainable coatings has strengthened the foundation for sector growth in recent years. Moreover, the global governments have observed in heavy implementation of environmentally and sustainable manufacturing in the past few years.
- The sudden growth of the functional and smart coatings has enabled the sector to explore untapped potential in the current period. Furthermore, these coatings are often loaded with features like anticorrosion, anti-fingerprint, and antibacterial.
- The heavy increase in innovative construction and infrastructure is expected to drive strategic transformation and sectoral scalability in the coming years. Also, the developers are actively demanding personalized and creative combination paints nowadays.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 239.06 / 79.73 Million Tons |
| Expected Size by 2035 | USD 398.78 Billion/ 123.16 Million Tons |
| Growth Rate from 2025 to 2035 | CAGR 5.11% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Resin Type, By Technology, By Application, By End-Use Industry, By Region |
| Key Companies Profiled | Sherwin-Williams: , PPG Industries, AkzoNobel, BASF SE , Axalta Coating Systems , RPM International Inc., Nippon Paint Holdings , Kansai Paint Co., Ltd. , Jotun Group , Hempel A/S , Asian Paints Limited , Berger Paints India Ltd. ,DuluxGroup , Valspar Corporation , Tikkurila Oyj |
Artificial Intelligence and Automation Revolutionizing Coatings Manufacturing Processes
The industry is witnessing a technology shift toward advanced, sustainable, and high-performance coating solutions. In recent years, companies have moved from traditional solvent-based coatings to water-based, powder-based, and UV-curable technologies due to environmental concerns and strict regulations. Moreover, manufacturers are using nanotechnology, artificial intelligence, and automation to improve coating quality, durability, and production efficiency.
Supply Chain Analysis of the Paints and Coatings Market:
- Distribution to Industrial Users:Industrial distributors act as vital bridges between paint manufacturers and heavy industries. They streamline bulk procurement, manage localized inventory, and ensure just-in-time delivery of specialized formulations like protective marine or automotive coatings. Beyond logistics, these distributors provide crucial technical support, regulatory compliance guidance, and custom color-matching services directly to end-users.
- Key Players: AkzoNobel, PPG Industries, Sherwin-Williams, and Axalta Coating Systems
- Chemical Synthesis and Processing :Chemical synthesis creates robust polymers, while precise mechanical processing disperses pigment particles evenly into this liquid matrix.Advanced milling equipment reduces clumps to maximize opacity, color strength, and durability. Finally, technicians incorporate specialized performance additives to ensure the finished formulation resists environmental weathering and adheres perfectly to industrial surfaces.
- Key Players: Sherwin-Williams, PPG Industries, and AkzoNobel
- Regulatory Compliance and Safety Monitoring:Regulatory compliance mandates strict monitoring of toxic raw materials and volatile organic compounds (VOCs) to guarantee environmental and workplace safety.
Manufacturers must continuously test formulations, manage hazardous waste streams, and issue clear safety data sheets. This rigorous oversight ensures chemical mixtures do not pose immediate health hazards during application.
- Key Agencies: ECHA, EPA, and OSHA.
Paints and Coatings Market Regulatory Landscape: Regulations
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Environmental Protection Agency (EPA) | 40 CFR Part 63, Subpart HHHHHH: National Emission Standards for Hazardous Air Pollutants (NESHAP) for Paint Stripping and Miscellaneous Surface Coating Operations at Area Sources. | HAP Control: Limiting target hazardous air pollutants like methylene chloride, cadmium, chromium, and lead during manufacturing and spraying. |
| Europe | European Commission |
Regulation (EC) No 1907/2006 (REACH): The overarching framework for the Registration, Evaluation, Authorisation, and Restriction of Chemicals. | Chemical Bans & Restrictions: Accelerated phase-outs of per- and polyfluoroalkyl substances (PFAS), specific solvents, and isocyanates. |
| China | Ministry of Emergency Management (MEM) |
GB 30981.1-2025: National mandatory standard limiting hazardous substances in Architectural Paints. | Harmful Substance Ceilings: Strict quantitative caps on total volatile organic compounds (VOCs), semi-volatile organic compounds (SVOCs), formaldehyde, heavy metals, and aromatic hydrocarbons. |
Paints and Coatings Market Dynamics
Driver
Construction Boom Supporting Global Paints Industry Expansion
The rapid growth of construction, industrialization, and infrastructure development activities worldwide is positioning the industry for long-term expansion. Also, in the current period, governments and private companies are investing heavily in residential housing, commercial buildings, transportation systems, and manufacturing industries, which is creating strong demand for paints and coatings.
Restraint
Hazardous Chemical Regulations Limiting Industry Growth Potential
The strict environmental regulations related to volatile organic compound emissions and hazardous chemical usage are expected to hamper the industry's growth in the coming years. In recent years, governments in North America, Europe, and several Asian countries have introduced strong rules to reduce pollution caused by traditional solvent-based coatings.
Opportunity
High Performance Coatings Supporting Future Industry Expansion
The increasing demand for sustainable, smart, and high-performance coating technologies is likely to create significant opportunities for manufacturers during the projected period. In the current period, industries such as renewable energy, electric vehicles, aerospace, healthcare, and electronics are adopting advanced coatings with anti-corrosion, heat-resistant, and self-cleaning properties.
Segments Insights
Resin Type
The acrylic resins segment dominated the market with 31% share in 2025, as acrylic-based coatings offer excellent durability, weather resistance, color retention, and fast drying properties. In recent years, these resins have become highly popular in decorative paints, industrial coatings, and architectural applications due to their strong performance and affordable pricing.
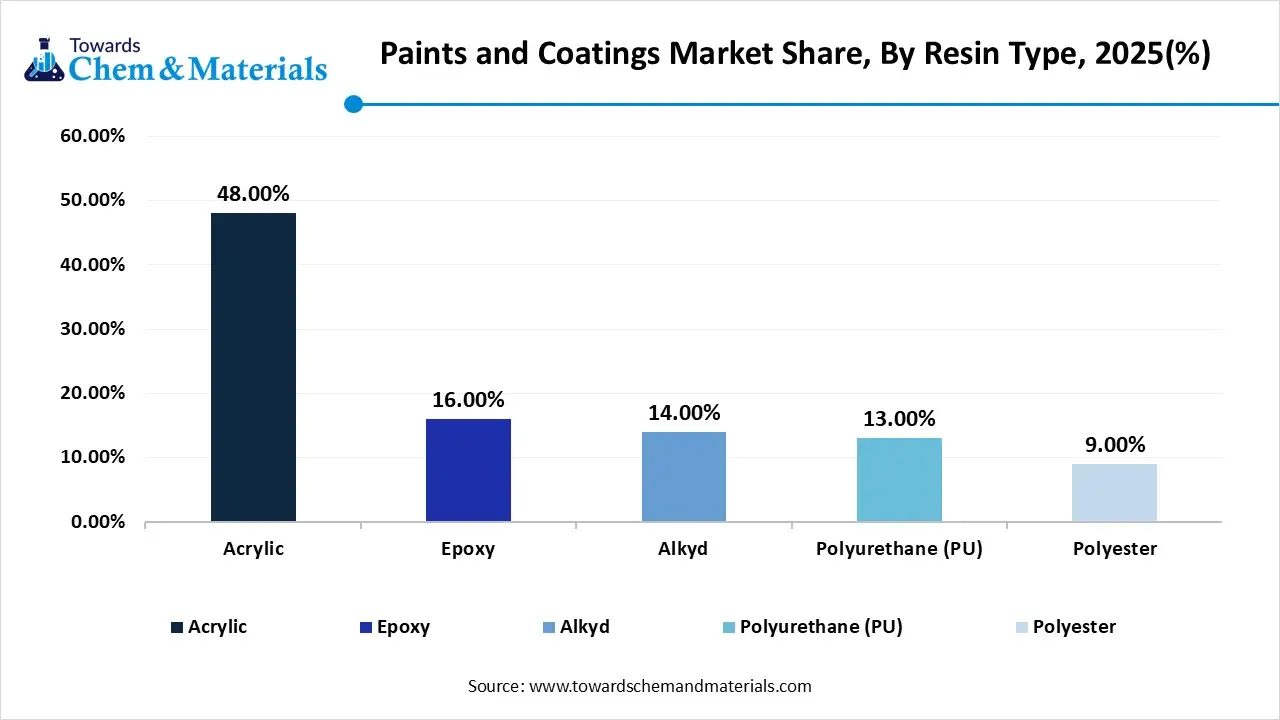
The polyurethane resins segment held the 13% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.8% in the forecast period, owing to its superior durability, flexibility, chemical resistance, and abrasion protection properties. In the current period, industries such as automotive, aerospace, industrial machinery, and construction are increasingly using polyurethane coatings for high-performance applications. Moreover, these coatings provide excellent surface finish and long-term protection against corrosion, chemicals, and extreme weather conditions.
The epoxy resins segment held the 17% market share in 2025, owing to epoxy-based coatings providing excellent adhesion, corrosion resistance, and chemical protection. In recent years, these coatings have gained strong popularity in industrial, marine, oil and gas, and infrastructure applications where strong surface protection is required. Moreover, epoxy coatings are widely used on metal surfaces, pipelines, storage tanks, bridges, and factory floors because they improve durability and reduce maintenance costs.
The alkyd resins segment held the 14% market share in 2025, akin to alkyd-based coatings offer strong gloss, smooth finish, and good adhesion properties at affordable prices. In the current period, these coatings are widely used in decorative paints, wood finishes, and industrial maintenance applications. Moreover, alkyd coatings remain popular in developing regions where cost-effective coating solutions are highly preferred for residential and commercial construction projects.
Paints And Coatings Market Share, By Resin Type, 2025 (%)
| By Resin Type | Revenue Share, 2025 (%) |
| Acrylic Resins | 31% |
| Alkyd Resins | 14% |
| Epoxy Resins | 17% |
| Polyester Resins | 11% |
| Polyurethane Resins | 13% |
| Fluoropolymer Resins | 5% |
| Vinyl Resins | 6% |
| Other Resin Types | 3% |
Technology Insights
The waterborne coatings segment dominated the market with 42% share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.9% in the forecast period, as these coatings are environmentally friendly, low in volatile organic compound emissions, and safer for users compared to traditional solvent-based products. In recent years, governments worldwide have introduced strict environmental regulations encouraging industries to adopt sustainable coating technologies.
The solventborne coatings segment held the 33% market share in 2025, owing to these coatings providing excellent durability, chemical resistance, and strong adhesion under extreme conditions. In the current period, industries such as marine, oil and gas, aerospace, and heavy machinery still prefer solvent-based coatings for highly demanding environments where superior performance is required.
The powder coatings segment held the 19% market share in 2025, owing to powder-based technologies providing excellent durability, high efficiency, and minimal environmental impact. In recent years, industries have increasingly adopted powder coatings because they produce very low emissions and generate less material waste compared to liquid coatings. Moreover, powder coatings offer strong resistance against scratches, corrosion, and chemicals, making them highly suitable for automotive parts, appliances, furniture, and industrial equipment.
The other technologies segment held the 6% market share in 2025, akin to industries are increasingly demanding faster and more energy-efficient coating solutions. In the current period, these advanced technologies are becoming popular in electronics, packaging, furniture, automotive, and printing applications. Moreover, UV-curable coatings provide fast curing speed, high productivity, and lower energy consumption compared to traditional coating methods.
Paints And Coatings Market Share, By Technology, 2025 (%)
| By Technology | Revenue Share, 2025 (%) |
| Waterborne Coatings | 42% |
| Solventborne Coatings | 33% |
| Powder Coatings | 19% |
| Other Technologies | 6% |
Application Insights
The architectural segment dominated the market with 35% share in 2025, as strong demand from residential, commercial, and infrastructure construction activities worldwide. In recent years, rapid urbanization, population growth, and increasing housing projects have significantly increased demand for decorative paints and protective coatings. Moreover, consumers are increasingly focusing on interior decoration, premium finishes, and modern color designs for homes and commercial spaces.
The protective coatings segment held the 10% market share in 2025 and is expected to be the fastest-growing segment in the market, with a CAGR of 6.4% in the forecast period, due to industries are increasingly focusing on equipment durability, corrosion prevention, and long-term infrastructure protection. In the current period, sectors such as oil and gas, marine, aerospace, renewable energy, and heavy manufacturing are investing heavily in advanced protective coating technologies.
The automotive OEM segment held the 12% market share in 2025, akin to vehicle manufacturers are increasingly using advanced coatings to improve durability, appearance, and corrosion resistance. In recent years, rising electric vehicle production and lightweight vehicle manufacturing have increased demand for specialized automotive coatings.
The general industries segment held the 11% market share in 2025, akin to industries are increasingly using paints and coatings to improve equipment durability, corrosion protection, and operational efficiency. In the current period, sectors such as machinery, electronics, metal fabrication, packaging, and manufacturing are increasing demand for industrial coatings. Moreover, rising industrial automation and infrastructure modernization projects are creating new opportunities for protective and specialty coatings.
Paints And Coatings Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Architectural | 35% |
| Automotive OEM | 12% |
| Marine | 5% |
| Coil | 6% |
| General Industries | 11% |
| Protective Coatings | 10% |
| Automotive Refinish | 7% |
| Industrial Wood | 5% |
| Packaging | 6% |
| Others | 3% |
Regional Analysis
How Asia Pacific Dominate the Paints and Coatings Market in 2025?
The Asia Pacific paints and coatings market size was estimated at USD 103.89 billion in 2025 and is projected to reach USD 185.43 billion by 2035, growing at a CAGR of 5.96% from 2026 to 2035.The Asia Pacific dominated the market with a share of 46% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 6.8% in the forecast period, due to governments across the region investing heavily in smart cities, transportation systems, housing projects, and industrial development, which is creating strong demand for decorative and industrial coatings. Furthermore, the region also benefits from lower manufacturing costs and easy raw material availability.
China
- The government of China has focused on heavy infrastructure upgrades and green building projects while driving the industry growth in the current period.
- Also, the local manufacturer of paints and coatings in China has been observed developing low-VOC coatings and water-based formulations nowadays.
Japan
- The industries such as the advanced automotives, electronics, and robotics are actively playing a major role in the industry's potential in recent years.
- Also, the greater demand for personalized and specialty coatings has been elevating the industry growth in the current period.
India
- The major factors, such as the cost-effective housing projects, urbanization, and heavy industrial expansion, are leading the industry sales in India.
- The decorative paints have gained maximum attention in the country while offering affordable options to consumers in recent years.
Paints and Coatings Market Evaluation in North America
The North America Paints and Coatings market size is estimated at USD 49.69 billion in 2026 and is projected to reach USD 89.73 billion by 2035, growing at a CAGR of 6.09% from 2026 to 2035. North America is notably growing with 22% market share in 2025, owing to technological innovation, sustainable coating development, and strong industrial modernization activities. In the current period, companies across the region are investing heavily in advanced coatings for electric vehicles, aerospace, construction, and renewable energy industries. Moreover, strict environmental regulations are encouraging the use of eco-friendly and low-emission coatings, creating demand for premium products.
United States
- The United States has been heavily involved in using advanced coatings for applications such as defense, aerospace, and renewable energy sources nowadays.
- Furthermore, the country is actively investing in self-cleaning and anti-corrosion, including smart coatings nowadays.
Canada
- Canada has increasingly focused on the development of eco-friendly and sustainable paints and coatings, which is likely to lead to industry growth in the coming years.
- Also, consumers are heavily shifting towards protective coatings in specific industries like pipelines, oil and gas, and transportation.
Europe Paints and Coatings Industry Conditions
The Europe Paints and Coatings market size was estimated at USD 45.17 billion in 2025 and is projected to reach USD 81.75 billion by 2035, growing at a CAGR of 6.11% from 2026 to 2035. Europe held the 20% market share in 2025 owing to increasing sustainability initiatives, industrial innovation, and strict environmental regulations. In recent years, many European countries have focused on reducing carbon emissions by promoting eco-friendly paints and low-VOC coatings. Moreover, renovation of old buildings and infrastructure modernization projects are creating a strong demand for decorative and protective coatings.
Germany
- The major drivers in Germany, such as the powerful automotive, manufacturing bases, and industrial machinery, are creating lucrative opportunities for manufacturers in Germany.
- The stricter environmental regulations and turn toward energy efficiency have been observed in recent surveys.
Italy
- The innovative furniture manufacturing and restoration of historic buildings have provided immense attention to the coatings and paint manufacturers nowadays.
- Also, major industries like hospitality and tourism are playing a major role in the ongoing sales of coatings and paints in the current period.
Paints and Coatings Market Survey in Latin America
The Latin America Paints and Coatings market size was estimated at USD 15.81 billion in 2025 and is projected to reach USD 29.91 billion by 2035, growing at a CAGR of 6.58% from 2026 to 2035.Latin America held the 7% market share in 2025 due to increasing urbanization, infrastructure development, and industrial activities in the current period. Moreover, countries across the region are investing in residential construction, transportation projects, and manufacturing expansion, which is creating strong coating demand. Decorative paints are becoming more popular because of improving living standards and rising middle-class populations.
Brazil
- The heavy influence of the construction, agriculture, and mining industries has created a better presence of the coatings and paint industry, as per the recent observation.
- Also, the innovative packaging and furniture shift has been acting as a major advantage for the paint manufacturers in Brazil these days.
Argentina
- The local manufacturers are improving production capabilities to meet changing market needs and environmental standards.
- Local manufacturers are improving production capabilities to meet changing market needs and environmental standards.

Middle East & Africa’s Paints and Coatings Sector Observation
The Middle East & Africa Paints and Coatings market size was estimated at USD 11.29 billion in 2025 and is projected to reach USD 21.93 billion by 2035, growing at a CAGR of 6.86% from 2026 to 2035.The Middle East and Africa held the 5% market share in 2025, akin to rising infrastructure investments, urban development, and industrial expansion. In recent years, governments across the region have launched large construction projects, smart cities, tourism developments, and transportation networks, increasing demand for coatings. Moreover, protective coatings are becoming important in oil and gas, marine, and industrial sectors because of extreme climate conditions.
Saudi Arabia
- The country is investing heavily in smart cities, commercial buildings, airports, entertainment centers, and industrial facilities, creating large demand for decorative and protective coatings.
- Protective coatings are widely used in oil and gas facilities, pipelines, and marine industries because of harsh environmental conditions.
UAE
- Cities like Dubai and Abu Dhabi have increased investments in commercial towers, hotels, transportation infrastructure, and smart city projects, boosting coating demand significantly.
- Also, the region’s extreme weather conditions are increasing the use of heat-resistant and protective coatings in buildings and industrial facilities.
Recent Developments
- In May 2026, Zydex introduced an innovative paint that can act as a shield against monsoon damage. Also, the newly launched paint is known as silicate mineral paint, and it can create a breathable surface which allows vapors to escape, as per the company's claim.(Source: dailypioneer.com)
- In November 2025, Convestro entered a partnership with Nippon Paint. The aim behind this partnership is to provide strength to automotive & industrial coatings. Also, these companies are likely to launch sustainable and high-performance coatings in the coming years, as per the company's claim.(Source: www.indianchemicalnews.com)
Top Players In The Paints And Coatings Market & Their Offerings:

- AkzoNobel: This Dutch powerhouse makes the coatings that protect major landmarks and everyday items globally. They focus heavily on sustainable, eco-friendly formulas, supplying everything from durable marine paints for cargo ships to bright architectural finishes.
- PPG Industries: Based in Pittsburgh, this company is a massive force in industrial and aerospace coatings. They specialize heavily in the automotive world, creating the tough, shiny factory finishes on millions of new cars. Their focus leans toward high-tech chemical solutions that resist extreme heat, harsh weather, and heavy wear.
- Sherwin-Williams: Most people recognize them from their neighborhood retail paint stores, but their commercial reach is absolutely massive. They dominate the North American housing and commercial building sectors. Beyond house paint, they manufacture heavy-duty protective layers for structural steel, bridges, and giant storage tanks that face intense environmental stress.
- Axalta Coating Systems: Axalta Coating Systems is a global leader focused directly on liquid and powder coatings for transport and refinishing. They supply the premium paint for major automotive manufacturing lines, and the specialized refinish coatings that local collision shops use to fix scratches.
Other Key Players
- BASF
- Nippon Paint
- Kansai Paint
- RPM International
- Hempel
- Jotun
- Asian Paints
- Masco Corporation
Segments Covered:
By Resin Type
- Acrylic Resins
- Pure Acrylic
- Styrene Acrylic
- Thermoplastic Acrylic
- Water-Based Acrylic
- Alkyd Resins
- Long Oil Alkyd
- Medium Oil Alkyd
- Short Oil Alkyd
- Epoxy Resins
- Bisphenol A Epoxy
- Novolac Epoxy
- Waterborne Epoxy
- Polyester Resins
- Saturated Polyester
- Unsaturated Polyester
- Powder Coating Polyester
- Polyurethane Resins
- Aromatic Polyurethane
- Aliphatic Polyurethane
- Waterborne Polyurethane
- Fluoropolymer Resins
- PVDF
- FEVE
- PTFE-Based
- Vinyl Resins
- Polyvinyl Acetate
- Polyvinyl Chloride
- Vinyl Ester
- Other Resin Types
- Silicone Resins
- Amino Resins
- Phenolic Resins
By Technology
- Waterborne Coatings
- Acrylic Waterborne
- Epoxy Waterborne
- Polyurethane Waterborne
- Solventborne Coatings
- High Solids
- Conventional Solventborne
- Alkyd Solventborne
- Powder Coatings
- Thermoset Powder
- Thermoplastic Powder
- Hybrid Powder
- Other Technologies
- UV-Cured Coatings
- Radiation-Cured Coatings
- High-Solid Coatings
By Application
- Architectural
- Residential Buildings
- Commercial Buildings
- Infrastructure Projects
- Automotive OEM
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
- Marine
- Cargo Ships
- Offshore Platforms
- Recreational Boats
- Coil
- Steel Coil
- Aluminum Coil
- General Industries
- Machinery
- Consumer Goods
- Electronics
- Protective Coatings
- Oil & Gas
- Power Generation
- Mining
- Automotive Refinish
- Passenger Vehicle Refinish
- Fleet Refinish
- Industrial Wood
- Furniture
- Flooring
- Cabinets
- Packaging
- Metal Packaging
- Flexible Packaging
- Food Containers
- Others
- Aerospace
- Textile Coatings
- Rail Coatings
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.