
U.S. Petrochemicals Market Size, Competitive Landscape Analysis Report 2035
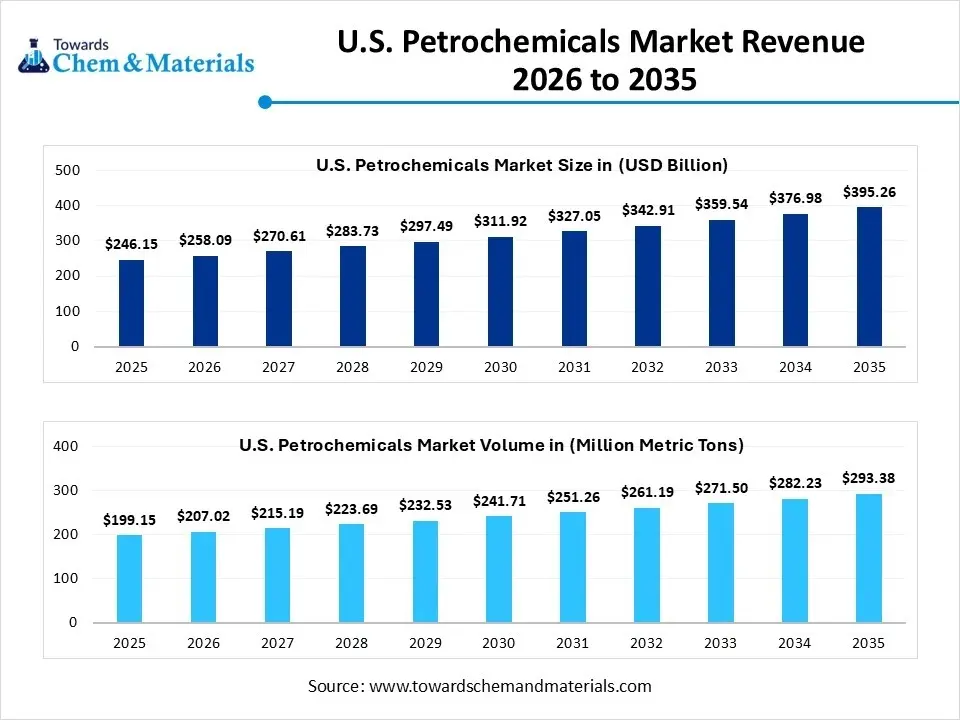
The U.S. petrochemicals market size was valued at USD 246.15 billion in 2025, is estimated to reach USD 258.09 billion in 2026, and is projected to reach USD 395.26 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 4.85% over the forecast period from 2026 to 2035. The push from the major industries around the globe and the country itself, such as packaging, automobiles, and electronics. Also, sustainable manufacturing is expected to play a major role in the future planning of the industry, where the middle way or better decision are act as the main pillar of the industry, as per our industry experts survey.
According to Towards Chemicals and Materials Analytics and Consulting, the U.S. petrochemicals market volume was valued at 199.15 million metric tons in 2025 and is expected to surpass around 293.38 million metric tons by 2035, accelerating a compound annual growth rate (CAGR) of 3.95% over the forecast period from 2026 to 2035.
Market Highlights
- By product, the ethylene segment dominated the market with a 34% share in 2025 and is expected to grow at a CAGR of 4.80% in the forecast period.
- By product, the propylene segment held a 22% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.60% in the forecast period.
- By manufacturing process, the steam cracking segment dominated the market with a 58% share in 2025 and is expected to grow at a CAGR of 4.10% in the forecast period.
- By manufacturing process, the fluid catalytic cracking segment held a 27% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.10% in the forecast period.
- By end use, the packaging segment dominated the market with a 37% share in 2025 and is expected to grow at a CAGR of 4.90% in the forecast period.
- By end use, the electronics segment held a 14% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.90% in the forecast period.
The Improved Product Wave
The heavy focus on greater production efficiency with the following sustainability regulations is actively changing petrochemical industry standards in the United States nowadays. Furthermore, the difficult global situations affect the limited supply of the United States, where the country is not totally dependent on crisis regions like Iran and the Middle East, as per the latest survey. Also, the major manufacturers and importers of petrochemicals in the United States are observed updating industry equipment and integrating digital monitoring these days, as per the recent regional observation.
- For instance, in March 2026, Shintech announced a greater investment for the petrochemical complex in Louisiana, United States. Also, the company is likely to invest around $3.4 billion, which includes the construction of a second ethylene production unit, as per the published report.(Source: www.hydrocarbonengineering.com)
At the same time, the industry is adapting to changing market expectations. Customers are increasingly looking for products with lower environmental impact, encouraging companies to improve energy efficiency, reduce emissions, and develop recycling solutions. Although traditional petrochemical production continues to dominate, businesses are gradually introducing cleaner manufacturing practices and exploring alternative feedstocks.
Investment Flow for the U.S. Petrochemicals Market 2026
Investment in the United States petrochemicals market remains strong because companies continue to expand production capacity, improve existing facilities, and strengthen supply chains. Much of this investment is concentrated along the U.S. Gulf Coast, where companies benefit from easy access to raw materials, transportation networks, and export infrastructure.
Many manufacturers are investing in plant modernization to improve efficiency and reduce operating costs. Instead of only constructing new facilities, companies are upgrading production units with automation, digital process controls, and energy-efficient equipment. These improvements help increase production while supporting safer and more reliable operations.
Moreover, another major investment area is petrochemical recycling and lower-emission manufacturing technologies. Companies are working on projects that improve resource efficiency and support circular economy goals while continuing to meet industrial demand.
- For instance, earlier, LyondellBasell continued investing in circular and advanced recycling technologies supporting its North American petrochemical business, as per the latest reports.(Source: finance.yahoo.com)
Market Trends
- Advancing petrochemical plants with modern equipment, technologies, and mechanisms has actively driven strategic transformations and sectoral scalability of the industry in recent years. Moreover, by improving product quality, modern equipment has gained major industry attention.
- The focus on sustainable and recycling processes is actively strengthening the foundation for future sector growth. The major manufacturers are actively using and recovering useful raw materials from different waste, such as plastic waste and others, in the United States nowadays.
- The heavy demand from the high-growth industries such as packaging, electronics, and automotive is expected to generate value-added opportunities for the industry participants during the forecast period. Also, all these sectors are increasingly dependent on petrochemicals, but are now slowly turning their needs as per the recent sustainability standards by using innovative raw materials and other things.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 258.09 Billion/ 207.02 Million Metric Tons |
| Expected Size in 2035 | USD 395.26 Billion/ 293.38 Million Metric Tons |
| Growth Rate | CAGR of 4.85% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Segment Covered | By Product, By Manufacturing Process, By End-use |
| Key Companies Profiled | Chevron Phillips Chemical, Westlake Corporation, Formosa Plastics Corporation, U.S.A., Eastman Chemical Company, INEOS Olefins & Polymers USA, Occidental Chemical Corporation (OxyChem) |
Artificial Intelligence and Digital Monitoring in Production Plants
The industry is actively turning towards the greater adoption of digital manufacturing and advanced process automation. Also, companies are using artificial intelligence, machine learning, industrial sensors, digital twins, predictive maintenance, and real-time process monitoring to improve plant operations. These technologies help manufacturers identify equipment issues early, reduce unexpected shutdowns, improve energy efficiency, and maintain consistent product quality. Along with automation, companies are also introducing advanced recycling technologies and more energy-efficient production systems.
Supply Chain Analysis of the U.S. Petrochemicals Market:
Production & Processing
- The U.S. shale boom sparked an absolute powerhouse in petrochemical manufacturing, letting us turn raw domestic oil and natural gas into everyday building blocks like plastics, paints, and fibers.
Most of this complex processing hums along the Gulf Coast, feeding a massive global supply chain that keeps modern life moving. - Dow: Dow is a pioneer in materials science, operating massive packaging and specialty chemical facilities worldwide from its Midland, Michigan headquarters.
- Key players: ExxonMobil Chemical, Chevron Phillips Chemical, and LyondellBasell
Quality Testing and Certification
- Rigorous testing ensures U.S. petrochemicals meet strict global standards before hitting the market, ensuring safety and performance.
- Expert labs meticulously check chemical purity, stability, and environmental compliance, giving manufacturers and consumers peace of mind that these complex materials are completely reliable and safe for everyday products.
- ASTM International: ASTM International develops the critical consensus standards and testing protocols used globally to verify petrochemical quality and safety.
- Key Agencies: Intertek, SGS North America, and Bureau Veritas
Distribution to Industrial Users
- Getting U.S. petrochemicals to factories requires a beautifully synchronized dance of logistics, moving bulk materials safely across the country. Specialized networks reliably deliver these raw elements to industrial manufacturers, who ultimately transform them into the essential automotive parts, medical supplies, and consumer goods we use every single day.
- Enterprise Products Partners: Enterprise Products Partners operates a massive, intricate network of pipelines and storage terminals that seamlessly connects Gulf Coast producers with major industrial consumers.
- Key players: Kinder Morgan, Energy Transfer, and Brenntag
Types and Integrated Uses of Petrochemicals
Petrochemicals are chemical products made mainly from crude oil and natural gas. They are the building blocks for thousands of products used in daily life. From food packaging and clothing to medical equipment and electronic devices, petrochemicals support almost every industry. In the United States, petrochemical manufacturing is a major industry because the country has a strong supply of natural gas and well-developed production facilities.
Ethylene
- Ethylene is the most widely produced petrochemical in the world and is the foundation of many plastic products. It is mainly used to produce polyethylene, one of the most common plastics used in packaging films, shopping bags, bottles, food containers, pipes, and household products.
- Ethylene is also used to manufacture ethylene glycol, which is required for polyester fibers, textile products, antifreeze, and PET bottles. Because packaging, healthcare, and consumer goods industries continue to grow, demand for ethylene remains very high. Its wide range of applications makes it one of the most important raw materials in the petrochemical industry.
Propylene
- Propylene is another important petrochemical used in manufacturing polypropylene plastics. Polypropylene is widely used in automotive components, food packaging, medical syringes, reusable containers, furniture, home appliances, and consumer goods.
- Propylene is also used to produce chemicals such as propylene oxide and acrylonitrile, which are required for insulation materials, coatings, adhesives, synthetic fibers, and engineering plastics. As industries continue demanding lightweight and durable materials, propylene remains an essential petrochemical for modern manufacturing.
Benzene
- Benzene is an aromatic petrochemical used as a raw material for producing synthetic rubber, nylon fibers, detergents, dyes, plastics, and industrial chemicals. It plays an important role in the automotive, textile, electronics, and construction industries.
- Many products used in daily life contain materials that are manufactured from benzene-based chemicals. Although strict safety regulations govern its handling, benzene continues to be an essential feedstock for many industrial manufacturing processes.
Toluene
- Toluene is commonly used in paints, coatings, adhesives, inks, cleaning products, and chemical manufacturing. It also serves as a raw material for producing benzene and other specialty chemicals.
- The construction, automotive, and industrial manufacturing sectors are major consumers of toluene because these industries require large amounts of coatings and solvent-based products. Its versatility makes it valuable across many industrial applications.
Xylene
- Xylene is mainly used to manufacture purified terephthalic acid (PTA), which is required to produce polyester fibers and PET plastic bottles. It is also used in paints, printing inks, rubber products, and industrial solvents.
- Demand for xylene continues to grow because polyester is widely used in clothing, packaging materials, home textiles, and beverage containers. This makes xylene an important petrochemical for both consumer and industrial products.
Methanol
- Methanol is an important chemical used to produce formaldehyde, adhesives, plastics, paints, resins, and synthetic fuels. It is also used in biodiesel production and several industrial chemical processes.
- Manufacturers use methanol because it is a flexible raw material that supports multiple industries, including construction, automotive, agriculture, and energy. Growing interest in cleaner fuels has also increased attention on methanol-based technologies.
Butadiene
- Butadiene is mainly used to manufacture synthetic rubber. Synthetic rubber is essential for tires, footwear, industrial belts, hoses, gloves, and automotive parts. The automotive industry is the largest consumer because almost every vehicle requires synthetic rubber components
U.S. Petrochemicals Market Regulatory Landscape: Regulations
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | U.S. Environmental Protection Agency (EPA) | The Clean Air Act (CAA) | This rule tackles toxic emissions leaking from heavy industrial equipment. |
Market Dynamics
Driver :The Stronger Base of Natural Gas
The strong availability of natural gas, especially from shale gas production, has opened profitable avenues for manufacturers in recent years. Natural gas provides cost-effective raw materials such as ethane, which are widely used to manufacture petrochemicals. This helps companies produce chemicals at competitive costs while maintaining a steady supply. At the same time, growing demand from packaging, automotive, healthcare, construction, and consumer goods industries is increasing the need for petrochemical products.
Restraint : Introduction of Sustainable Manufacturing Practices
Increasing environmental regulations related to emissions, waste management, and energy use are expected to hinder industry growth during the forecast period. Manufacturers are expected to reduce their environmental impact while continuing production. Meeting these requirements often requires companies to invest in cleaner technologies, modern equipment, and improved production systems, which can increase operating costs. In addition, fluctuations in crude oil and natural gas prices can affect production expenses and profit margins.
Opportunity :Development and Sales Leads Through Advanced Technologies
The development of advanced recycling technologies and circular economy solutions is likely to create lucrative opportunities during the forecast period. Many companies are investing in processes that recover valuable raw materials from plastic waste and reuse them in new products. This helps improve resource efficiency while supporting customer demand for more sustainable materials. Another important opportunity comes from growing demand for specialty petrochemicals used in electric vehicles, electronics, renewable energy equipment, and advanced medical products.
Segmental Insights
Product Insights
The ethylene segment dominated the market with a 34% share in 2025 and is expected to grow at a CAGR of 4.80% in the forecast period, as the most widely used building-block chemical for manufacturing a wide range of products. It is mainly used to produce polyethylene, which is required for packaging films, plastic bottles, food containers, pipes, and many consumer goods. Ethylene is also used to manufacture ethylene glycol for polyester fibers and PET packaging. The United States benefits from abundant ethane obtained from shale gas, making ethylene production more economical. Strong demand from packaging, healthcare, construction, and consumer goods industries continues to support its leading position in the market.
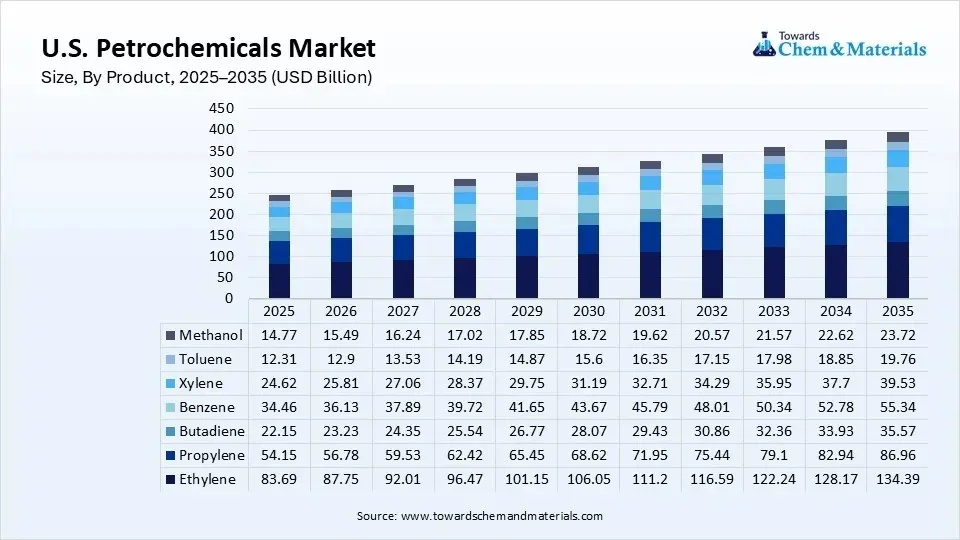
The propylene segment held a 22% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.60% in the forecast period, owing to industries increasingly using polypropylene and other propylene-based materials. Polypropylene is lightweight, durable, and easy to process, making it suitable for automotive components, medical products, electronics, reusable packaging, and household goods. As electric vehicles, healthcare equipment, and electronic devices continue expanding, the demand for propylene-based materials is expected to rise steadily. Companies are also investing in advanced production technologies to increase propylene availability.
U.S. Petrochemicals Market Share, By Product, 2025(%)
| By Product | Market Share (%) |
| Ethylene | 34% |
| Propylene | 22% |
| Butadiene | 9% |
| Benzene | 14% |
| Xylene | 10% |
| Toluene | 5% |
| Methanol | 6% |
Manufacturing Process Insights
The steam cracking segment dominated the market with a 58% share in 2025 and is expected to grow at a CAGR of 4.10% in the forecast period, owing to its being the primary process used to produce large volumes of ethylene and other important petrochemicals. The country has abundant ethane from shale gas, making steam cracking an efficient and cost-effective production method. This process supports the manufacturing of plastics, packaging materials, synthetic fibers, and industrial chemicals used by many industries. Large-scale petrochemical plants across the United States Gulf Coast are designed around steam cracking technology because it delivers high production capacity, reliable output, and consistent product quality, making it the leading manufacturing process in the market.
The fluid catalytic cracking segment held a 27% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.10% in the forecast period, owing to it produces valuable petrochemical feedstocks such as propylene while also supporting refinery operations. As demand for propylene-based products continues to increase, refiners are focusing on improving FCC technologies to increase propylene production. Modern FCC systems are becoming more efficient through better catalysts, process optimization, and digital monitoring technologies. These improvements help manufacturers improve production efficiency while meeting changing market demand.
U.S. Petrochemicals Market Share, By Manufacturing Processes, 2025(%)
| By Manufacturing Processes | Market Share (%) |
| Steam Cracking | 58% |
| Fluid Catalytic Cracking (FCC) | 27% |
| Catalytic Reforming | 15% |
End Use Insights
The packaging segment dominated the market with a 37% share in 2025 and is expected to grow at a CAGR of 4.90% in the forecast period, owing to packaging materials being used across almost every industry. Food and beverage companies, pharmaceutical manufacturers, consumer goods producers, and e-commerce businesses all require plastic packaging to protect products during storage and transportation. Petrochemical materials provide lightweight, durable, flexible, and cost-effective packaging solutions. Increasing online shopping and demand for packaged food products have further increased the need for polyethylene, polypropylene, and PET materials.
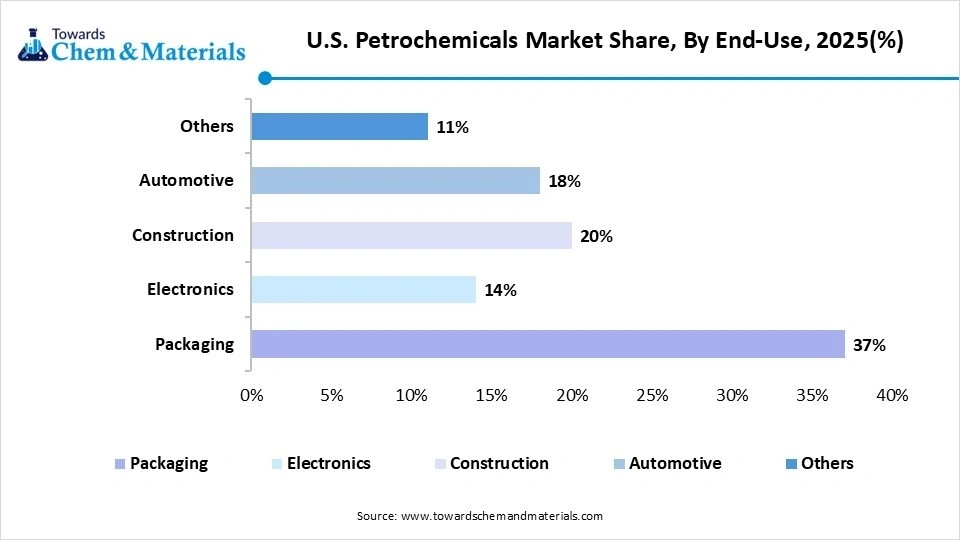
The electronics segment held a 14% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 5.90% in the forecast period, owing to modern electronic devices requiring high-performance plastic materials and specialty petrochemicals. Smartphones, computers, data centers, communication equipment, semiconductors, and household electronics all depend on lightweight, durable, and heat-resistant materials produced from petrochemicals. Growing investment in artificial intelligence infrastructure, advanced electronics manufacturing, electric vehicles, and semiconductor production is expected to increase demand for these materials.
U.S. Petrochemicals Market Share, By End-Use, 2025(%)
| By End-Use | Market Share (%) |
| Packaging | 37% |
| Electronics | 14% |
| Construction | 20% |
| Automotive | 18% |
| Others | 11% |
Recent Development
- In February 2026, ExxonMobil established its third recycling unit in Baytown, United States. Also, the newly established facility is able to recycle 250 million pounds of plastic annually, which defines the companys goals towards sustainability as per the published report.(Source: www.chemanalyst.com )
- In May 2026, Chevron introduced its latest technology, which is specifically designed for Chevron and Texaco Gasolines, as per the companys claim. Furthermore, the newly launched technology is known as Techron, as per the published report. (Source: www.businesswire.com)
Competitive Analysis
The United States petrochemicals industry is becoming more competitive as manufacturers focus on increasing production, improving plant efficiency, and developing higher-value chemical products. Many companies are upgrading existing manufacturing facilities instead of building entirely new plants. They are also introducing digital technologies, automation, and advanced recycling solutions to improve productivity and reduce operating costs.
ExxonMobil is strengthening its petrochemical business by expanding production at its Baytown manufacturing complex in Texas. The company has introduced new chemical production units to increase the supply of high-value materials used in industries such as packaging, automotive, construction, and consumer goods.
Dow continues to strengthen its petrochemical business by improving manufacturing efficiency and developing lower-emission production technologies. The company is investing in modern production processes, expanding circular economy initiatives, and increasing the use of recycled materials across its product portfolio.(Source: lowcarbon.exxonmobil.com)(Source: www.dow.com)
Top Vendors in the U.S. Petrochemicals Market & Their Offerings:
| Company | Company Type/Position | Major Headquarters | Geographic Presence | Offerings | Key Strength |
| Dow Inc. | Materials Science Leader & Top-Tier Volume Producer | Midland, Michigan, United States | Highly dense production networks in Texas and Louisiana (U.S. Gulf Coast) | Extensive ranges of high-density/low-density polyethylene (PE), industrial ethylene oxide intermediates, polyurethane raw materials, and specialized performance packaging silicones. | Massive global R&D ecosystem and unparalleled manufacturing scale for architectural coatings and high-performance industrial barriers. |
| ExxonMobil Chemical | Integrated Downstream Energy & Olefins Titan | Spring, Texas, United States | Heavy baseline infrastructure concentration across North America (Gulf Coast hubs) | Massive-scale outputs of basic chemical building blocks like ethylene, propylene, and butadiene, alongside premium butyl rubber, aromatics (benzene/toluene), and high-grade plasticizers. | Industry-leading expertise in high-performance eco-friendly coatings designed to comfortably pass hyper-strict global VOC and environmental regulations. |
| LyondellBasell Industries N.V | Polyolefins & Chemical Technology Pioneer |
Houston, Texas, United States | Core manufacturing cluster based in the United States (Texas coast) | The global gold-standard portfolio of polypropylene (PP) resins, advanced polyolefins, propylene oxide, ethylene glycol derivatives, and highly specialized automotive polymer compounds. | Vertical raw-material integration (controlling its own acetyl chain inputs), which protects margins from raw material price volatility. |
Other Key Players
- Chevron Phillips Chemical
- Westlake Corporation
- Formosa Plastics Corporation, U.S.A.
- Eastman Chemical Company
- INEOS Olefins & Polymers USA
- Occidental Chemical Corporation (OxyChem)
- Segments Covered in the Report
Segments Covered in the Report
By Product
- Ethylene
- Polyethylene Feedstock
- Ethylene Oxide Feedstock
- Ethylbenzene Feedstock
- Propylene
- Polypropylene Feedstock
- Propylene Oxide Feedstock
- Acrylonitrile Feedstock
- Butadiene
- Synthetic Rubber
- ABS Resins
- Latex
- Benzene
- Styrene
- Cumene
- Cyclohexane
- Xylene
- Para-Xylene
- Ortho-Xylene
- Mixed Xylene
- Toluene
- TDI Production
- Solvents
- Gasoline Blending
- Methanol
- Formaldehyde
- Acetic Acid
- Fuel & Energy
By Manufacturing Process
- Fluid Catalytic Cracking (FCC)
- Refinery Integrated FCC
- Petrochemical FCC
- Steam Cracking
- Ethane Cracking
- Naphtha Cracking
- LPG Cracking
- Catalytic Reforming
- Aromatics Production
- Hydrogen Generation
By End-use
- Packaging
- Flexible Packaging
- Rigid Packaging
- Electronics
- Semiconductor Materials
- Electrical Components
- Construction
- Pipes & Fittings
- Insulation
- Coatings
- Automotive
- Interior Components
- Exterior Components
- Under-the-Hood Parts
- Others
- Agriculture
- Healthcare
- Consumer Goods
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.