
Recycled Plastics In Green Building Materials Market Size and Forecast 2024 to 2034
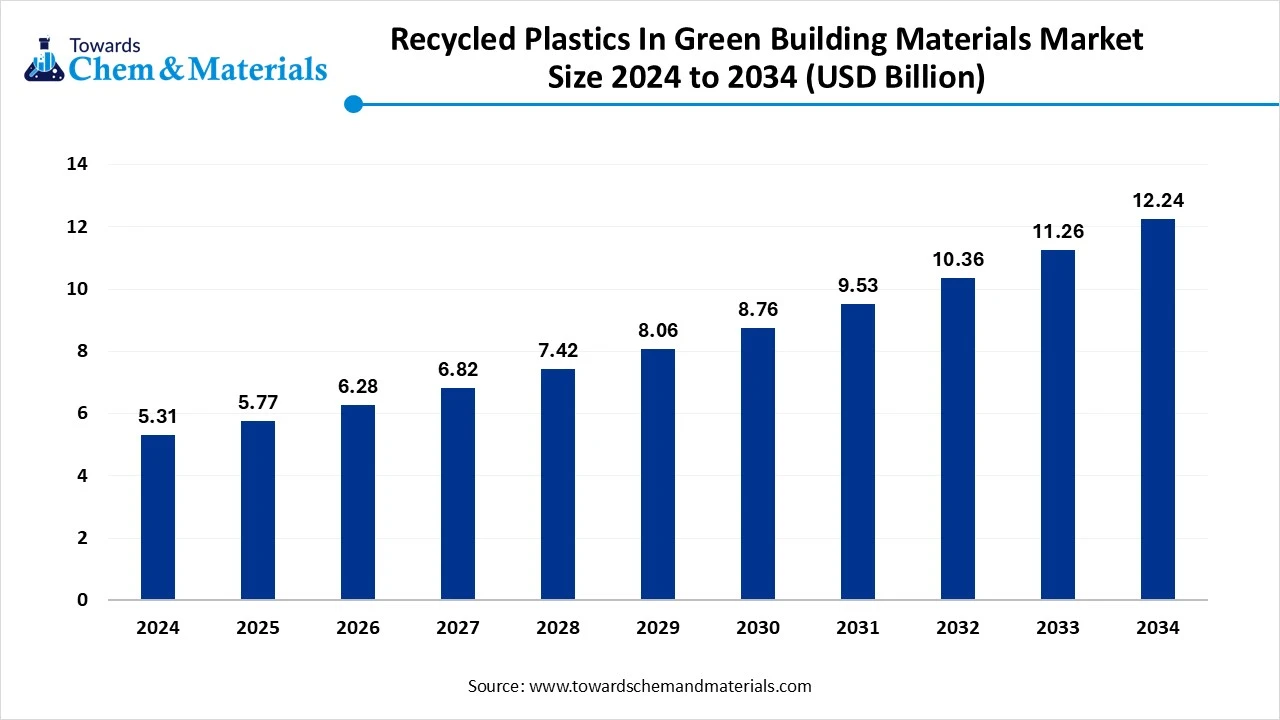
The global recycled plastics in green building materials market size was reached at USD 5.31 billion in 2024 and is expected to be worth around USD 12.24 billion by 2034, growing at a compound annual growth rate (CAGR) of 8.71% over the forecast period 2025 to 2034. The growing demand for sustainable construction practices is the key factor driving market growth. Also, innovations in recycling technologies coupled with the increasing demand for green buildings can fuel market growth further.
Key Takeaways
- By region, Asia Pacific dominated the market with a 40% market share in 2024. The dominance of the segment can be attributed to the surge in sustainability mandates.
- By region, Europe is expected to grow at the fastest CAGR over the forecast period. The growth of the region can be credited to the surge in corporate sustainability initiatives, along with increasing environmental awareness.
- By product type, the plastic lumber & decking segment dominated the market with a 28% share in 2024. The dominance of the segment can be attributed to the growing demand for sustainable construction alternatives.
- By product type, the composite building components segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be credited to the growing demand for sustainable construction practices.
- By polymer feedstock, the recycled HDPE segment led the market by holding 30% market share in 2024. The dominance of the segment can be linked to the unique properties of recycled HDPE.
- By polymer feedstock, the recycled PET segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by increasing consumer demand for transparency in material sourcing.
- By application, the residential construction segment held a 33% market share in 2024. The dominance of the segment is owed to the growing trend towards remodeling projects and home renovation.
- By application, the commercial & institutional segment is expected to grow at the fastest CAGR over the projected period. The growth of the segment is due to the cost-effectiveness of recycled plastics.
- By certification, the certified recycled content segment held a 42% market share in 2024. The dominance of the segment can be attributed to the rising environmental awareness.
- By certification, the LCA-verified segment is expected to grow at the fastest CAGR over the study period. The growth of the segment can be credited to the shifting sustainability standards and building codes.
- By end user, the homeowners & residential contractors segment held a 38% market share in 2024. The dominance of the segment can be linked to the rising consumer awareness regarding sustainability.
- By end user, the architects & specifiers segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by innovations in material science and changing building codes.
- By distribution channel, the building materials distributors & wholesalers segment dominated the market with 48% market share in 2024. The dominance of the segment is owed to the rapid research and development activities in the industry.
By distribution channel, the B2B direct contracts segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment is due to the unique benefits of recycled plastic in building materials.
Advancements in Recycling Technologies are Expanding Market Growth
The recycled plastics in green building materials market covers the production, processing, and utilization of post-consumer and post-industrial recycled polymers to manufacture sustainable building products worldwide. Key materials include recycled HDPE, PET, PVC, PP, mixed PCR blends, and bio-based/recycled hybrid resins, which are converted into plastic lumber, cladding, roofing, insulation facings, pavers, geosynthetics, and interior panels.
Globally, demand is driven by circular economy policies, extended producer responsibility (EPR) regulations, plastic waste bans, and rising adoption of green building certification systems such as LEED, BREEAM, Green Star, and WELL. Recycled-plastic-based building products are valued for durability, weather/moisture resistance, low maintenance, and their ability to reduce embodied carbon while promoting closed-loop resource use.
What Are the Key Trends Influencing the Recycled Plastics In Green Building Materials Market?
- The growing product demand in the packaging sector is the latest trend in the market. The recycled polymers have the capability to replace their conventional plastics, which acts as an obstacle between various environmental factors and food. Hence, recycled plastic is considered a preferred material in the packaging industry.
- The supportive government regulations and policies aiming at promoting plastic waste recycling are another trend shaping a positive market trajectory further. Recycled plastic building materials provide durable and cost-effective solutions to traditional materials, contributing to their rapidly growing popularity.
- Innovations in recycling technologies and the development of cutting-edge composite materials utilizing recycled plastics are increasingly expanding the range of applications by enhancing their overall performance. Also, recycled plastics are extensively used in interior finishing, insulation, and composite materials for construction purposes.
Report Scope
| Report Attribute | Details |
| Market Size in 2025 | USD 5.77 billion |
| Expected Size by 2034 | USD 12.24 billion |
| Growth Rate from 2025 to 2034 | CAGR 8.71% |
| Base Year of Estimation | 2024 |
| Forecast Period | 2025 - 2034 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Product Type, By Polymer Feedstock, By Application, By Certification, By End-User, By Distribution Channel, By region |
| Key Companies Profiled | Trex Company, Inc., Fiberon, AZEK Company Inc., Envirodeck, Composite Decking SA, Ecodek Outdoor Living, Terafest |
Market Opportunity
The Integration of Circular Economy Initiatives
The ongoing integration of circular economy principles into the production process and product design is a major factor creating lucrative opportunities in the market. Major market players are increasingly aligning with ESG goals, where products are manufactured for recyclability from inception. Furthermore, the rapid development of innovative recycling technologies like AI-based sorting systems and chemical recycling is anticipated to drive market growth soon.
- In October 2024, CRH Ventures, a major building materials solution company, introduced a new accelerator, the Sustainable Building Materials Program, to boost innovations in building materials. The program aims to detect advanced materials and applications to lessen environmental impact.(Source: www.businesswire.com)
Market Challenges
Lack of Standardisation
A lack of understanding and standardisation regarding the behavior and performance of recycled plastic building materials can affect their adoption by the construction sector. Moreover, establishing clear guidelines and standards for the utilization of recycled plastics in construction is important. The high cost associated with collecting, sorting, and processing plastic waste can hinder market growth further.
Regional Insight
Asia Pacific Recycled Plastics in Green Building Materials Market Trends
Asia Pacific dominated the market with a 40% market share in 2024. The dominance of the segment can be attributed to the surge in sustainability mandates and ongoing urbanization, especially in emerging economies such as China and India. In addition, the increased public awareness of sustainable building practices, along with subsidies for green construction, is leading to regional growth in the near future.
China Recycled Plastics In Green Building Materials Market
In the Asia Pacific, China led the market due to the rising environmental awareness, ongoing government initiatives, and innovations in recycling technology. Also, enhancements in additive technologies and polymer reclamation have increased the adoption of recycled plastics in the country.
Europe is expected to grow at the fastest CAGR over the forecast period. The growth of the region can be credited to the surge in corporate sustainability initiatives, along with increasing environmental awareness. Furthermore, European governments are increasingly implementing initiatives and regulations to promote recycling and minimize plastic waste, further fuelling the demand for recycled plastics in construction.
Segmental Insight
Product Type Insight
Which Product Type Segment Dominated the Recycled Plastics In Green Building Materials Market in 2024?
The plastic lumber & decking segment dominated the market with a 28% share in 2024. The dominance of the segment can be attributed to the growing demand for sustainable construction alternatives and the high durability and low maintenance of recycled plastic products as compared to conventional materials. The ability to recycle an extensive range of plastics into high-grade lumber contributes to segment expansion further.
The composite building components segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be credited to the growing demand for sustainable construction practices, coupled with the rising sustainability awareness. Recycled plastics are utilized in a range of composite building components such as decking, cladding, insulation, roofing, and fencing.
Polymer Feedstock Insight
Why Recycled HDPE Segment Dominated the Recycled Plastics In Green Building Materials Market in 2024?
The recycled HDPE segment dominated the market by holding 30% market share in 2024. The dominance of the segment can be linked to the unique properties of recycled HDPE and the rising need for sustainable construction practices. Also, innovations in recycling technologies are enhancing the efficiency and quality of recycled HDPE, making it more competitive with virgin materials.
The recycled PET segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by increasing consumer demand for transparency in material sourcing, which has raised rPET's appeal in the market. Rapid innovations in recycling technologies, particularly for PET bottles, are making it more convenient to produce high-quality rPET for building materials.
Application Insight
How Much Share Did the Residential Construction Segment Held in 2024?
The residential construction segment held a 33% market share in 2024. The dominance of the segment is owing to the growing trend towards remodelling projects and home renovation, along with the growing awareness regarding green building practices. Moreover, recycled plastics have applications in different residential construction areas such as decking, fencing, siding, and insulation.
The commercial & institutional segment is expected to grow at the fastest CAGR over the projected period. The growth of the segment is due to the cost-effectiveness of recycled plastics as compared to other virgin materials and government regulations supporting sustainability. Recycled plastics are used in an extensive range of building applications such as wall panels, decking, and insulation.
Certification Insight
Which Certification Segment Dominated the Recycled Plastics In Green Building Materials Market in 2024?
The certified recycled content segment held a 42% market share in 2024. The dominance of the segment can be attributed to the rising environmental awareness and other government initiatives supporting sustainable construction. In addition, the ongoing shift towards circular economy initiatives, where waste is reduced and resources are reused, is increasingly gaining traction during the forecast period.
The LCA-verified segment is expected to grow at the fastest CAGR over the study period. The growth of the segment can be credited to the shifting sustainability standards and building codes, and ongoing government subsidies and incentives promoting the market. Advancements in additive technologies and polymer modification are optimising the development of highly efficient recycled plastic composites.
End-User Insight
Which End User Segment Dominated the Recycled Plastics In Green Building Materials Market in 2024?
The homeowners & residential contractors segment held a 38% market share in 2024. The dominance of the segment can be linked to the rising consumer awareness regarding sustainability and increasing demand for green building practices. Furthermore, ongoing innovations in recycling technologies and the rapid development of cutting-edge applications for recycled plastics in the construction sector are driving the segment's growth soon.
The architects & specifiers segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by innovations in material science and changing building codes. Moreover, Architects are rapidly adopting recycled plastic products in their construction designs to fulfill client demand for sustainable buildings.
Distribution Channel Insight
How Much Share Did the Building Materials Distributors & Wholesalers Segment Held in 2024?
The building materials distributors & wholesalers segment dominated the market with 48% market share in 2024. The dominance of the segment is owed to the rapid research and development activities in the industry, along with the surge in green building initiatives. Additionally, many regions are offering tax breaks, incentives, and green building certifications that boost the use of recycled plastics in the construction sector.
The B2B direct contracts segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment is due to the unique benefits of recycled plastic in building materials. Governments across the globe are implementing policies and offering incentives to promote green building, which will impact positive market expansion shortly.
Recent Developments
- In April 2025, T2Earth introduced an OnWood Plywood, a sustainable fire-retardant treated wood. Created without toxic chemicals, it delivers a sustainable and fire retard design, providing developers and builders with healthier, higher-performing products.(Source: www.woodworkingnetwork.com)
Recycled Plastics In Green Building Materials Market Top Companies
- Trex Company, Inc.
- Fiberon
- AZEK Company Inc.
- Envirodeck
- Composite Decking SA
- Ecodek Outdoor Living
- Terafest
Segments Covered
By Product Type
- Plastic Lumber & Decking
- Exterior Cladding & Siding Panels
- Roofing Components (underlayments, tiles with recycled content)
- Insulation Facings & Vapor Barriers
- Pavers, Tiles & Hardscape Elements
- Interior Panels, Acoustic & Ceiling Tiles
- Window & Door Profiles (recycled PVC/UPVC blends)
- Geosynthetics & Landscape Products (weed barriers, drainage mats)
- Composite Building Components (structural insulated panels, façade modules)
By Polymer Feedstock
- Recycled HDPE (High-Density Polyethylene)
- Recycled PET (Polyethylene Terephthalate)
- Recycled PVC (Polyvinyl Chloride)
- Recycled PP (Polypropylene)
- Mixed/Reprocessed Plastics (regrind, PCR blends)
- Bio-plastic blends / recycled content blends
By Application
- Residential Construction (decking, siding, flooring)
- Commercial & Institutional Buildings (facades, ceiling systems)
- Infrastructure & Public Works (noise barriers, bridge components, pavers)
- Landscaping & Hardscape (pavers, edging)
- Industrial Buildings & Warehouses (cladding, vapor barriers)
- Renovation & Retrofit Projects (replacement decking, cladding)
By Certification
- Certified Recycled Content (e.g., PCR percentage certified)
- Low-VOC / Indoor Air Quality Rated
- LCA-verified Products
- Non-certified / Standard recycled content
By End-User
- Residential Homeowners & Contractors
- Commercial Developers & General Contractors
- Architects, Specifiers & AEC Firms
- Public Sector / Municipal Procurement
- Landscape Architects & Municipal Agencies
- Building Product Distributors & Retailers
By Distribution Channel
- B2B Direct Contracts (spec & bulk orders)
- Building Materials Distributors & Wholesalers
- Home Improvement Retailers (big-box & specialty)
- Online Marketplaces & OEM partnerships
- Recycling-to-manufacturing vertical supply agreements
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.