
Biaxially Oriented Polypropylene (BOPP) Market Size Analysis Report 2035
The global biaxially oriented polypropylene (BOPP) market size was estimated at USD 128.54 billion in 2025 and is expected to increase from USD 135.91 billion in 2026 to USD 224.40 billion by 2035, growing at a CAGR of 5.73% from 2026 to 2035. In terms of volume, the market is projected to grow from 10.2 million tons in 2025 to 14.8 million tons by 2035. growing at a CAGR of 3.87% from 2026 to 2035. Asia Pacific dominated the biaxially oriented polypropylene (BOPP) market with the largest volume share of 46% in 2025.The market is growing due to rising demand for flexible packaging, improved barrier properties, and increasing applications in food, labeling, and industrial sectors.
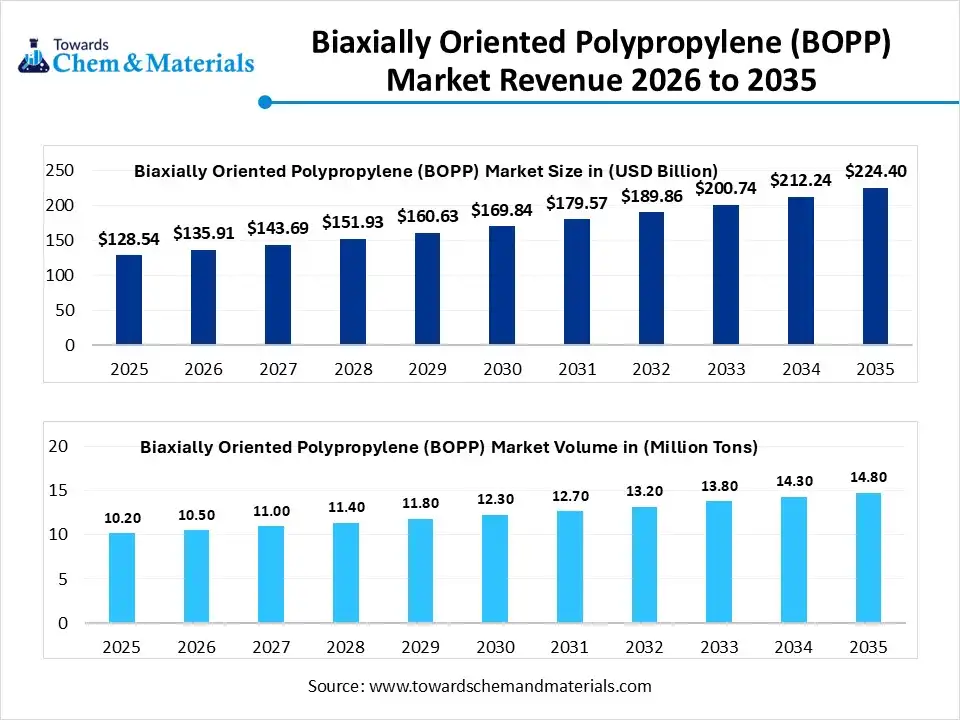
Market Highlights
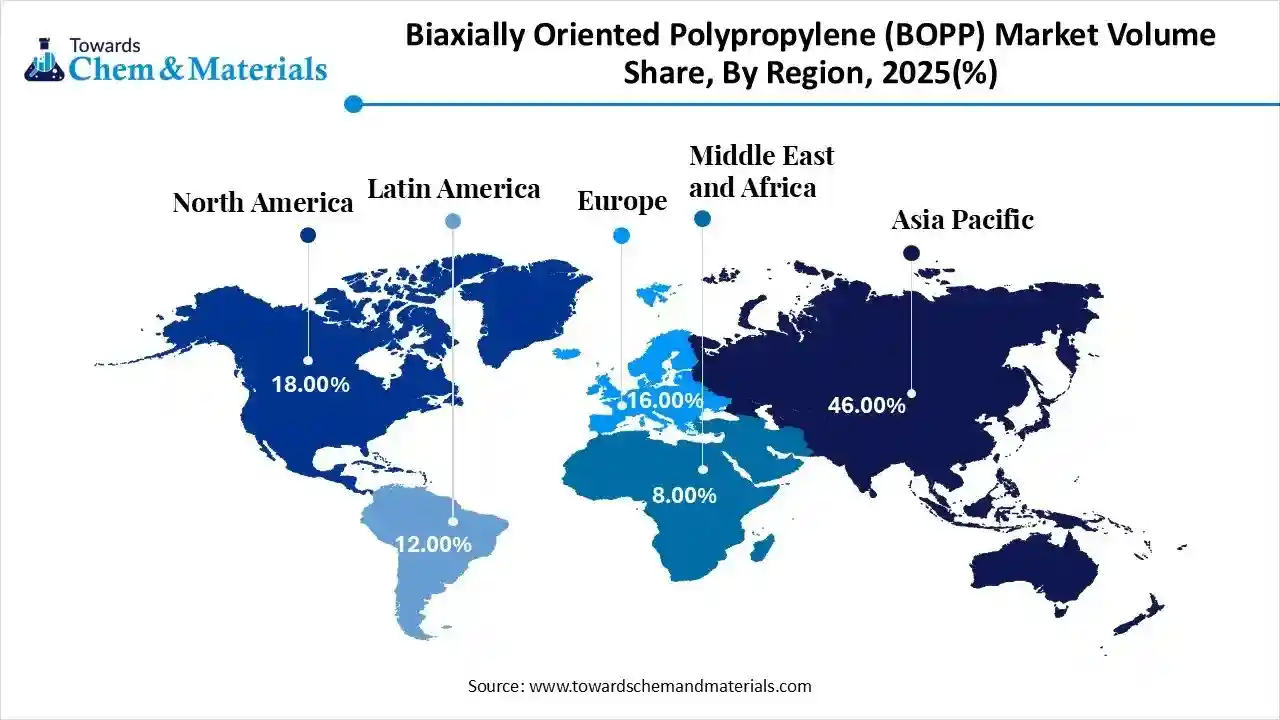
- The Asia Pacific dominated the global biaxially oriented polypropylene (BOPP) market with the largest volume share of 46.00% in 2025.
- The biaxially oriented polypropylene (BOPP) market in North America is expected to grow at a substantial CAGR of 4.39% from 2026 to 2035.
- The Europe biaxially oriented polypropylene (BOPP) market segment accounted for the major volume share of 16.00% in 2025.
- By type, the plain films segment dominated the market and accounted for the largest volume share of 58% in 2025.
- By type, the metallized films segment is expected to grow at the fastest CAGR of 5.03% from 2026 to 2035 in terms of volume.
- By thickness, the 15–30-micron segment led the market with the largest revenue volume share of 64% in 2025.
- By production process, the tenter process segment dominated the market and accounted for the largest volume share of 85% in 2025.
- By application, the wraps segment led the market with the largest revenue volume share of 35% in 2025.
- By end user industry, the food packaging segment dominated the market and accounted for the largest volume share of 48% in 2025.
Market Overview
Why is the Biaxially Oriented Polypropylene (BOPP) Market Expanding Rapidly?
The BOPP market is witnessing strong growth driven by its exceptional strength of clarity, and moisture barrier qualities, which make it perfect for flexible packaging. Adoption is also being accelerated by rising demand from industrial applications of food and beverage, and labeling.
The demand for long-lasting and aesthetically pleasing packaging solutions is also being driven by the rapid growth of e-commerce and urbanization. Furthermore, product performance and versatility are being improved by technological developments in coating and film production.
Market Key Trends
- Rising Demand in Food & Beverage Packaging: BOPP films are increasingly used for snacks, confectionery, and frozen foods due to their excellent barrier and clarity properties.
- Growth in Labeling Applications: BOPP films are preferred for self-adhesive and shrink labels because of durability, printability, and resistance to moisture.
- Technological Advancements in Coating & Metallization: Enhanced coating and metallized BOPP films improve barrier properties and extend the shelf life of packaged goods.
- E-commerce & Retail Packaging Expansion: The rise of online retail is driving demand for lightweight, tear-resistant, and visually appealing packaging solutions.
- Sustainability & Recyclable Packaging Focus: Manufacturers are increasingly offering recyclable and eco-friendly BOPP films to meet regulatory requirements and consumer demand.
Report Scope
| Report Attribute | Details |
| Market Size and Volume in 2026 | USD 135.91 Billion / 10.5 Million Tons |
| Revenue Forecast in 2035 | USD 224.40 Billion / 14.8 Million Tons |
| Growth Rate | CAGR 5.73% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Units Considered | Value (Billion / Million), Volume (Million Tons) |
| Dominant Region | Asia Pacific |
| Segment Covered | By Type, By Thickness, By Production Process, By Application, By End-User Industry, By Region |
| Key companies profiled | Jindal Poly Films Ltd., Taghleef Industries, Cosmo First (formerly Cosmo Films), UFlex Limited, Oben Holding Group, CCL Industries (Innovia Films), Toray Industries, Inc., Mitsubishi Chemical Group, Inteplast Group, Poligal S.A., Sibur Holding, Polibak, Zhejiang Kinlead Innovative Materials, Ganesha Ecosphere (Bio-BOPP focus), Manucor S.p.A. |
Market Opportunities
- Expansion in the Food & Beverage Sector: Growing packaged food consumption and demand for extended shelf-life products present significant opportunities for BOPP film adoption.
- Emerging Markets Growth: Rapid urbanization, increasing disposable income, and retail expansion in the Asia-Pacific, Latin America, and MEA regions can drive strong market growth.
- Sustainable & Eco-Friendly Packaging Solutions: Rising consumer awareness and government regulations create opportunities for recyclable and biodegradable BOPP films.
- Technological Innovations: Development of metallized, coated, and high-barrier BOPP films enables new applications in premium and specialty packaging.
- E-commerce & Modern Retail Packaging: The surge in online shopping and retail packaging demands lightweight, durable, and visually appealing BOPP films, expanding market potential.
Value Chain Analysis
- Raw Material Sourcing: Polypropylene resin used in BOPP film manufacturing is sourced from large petrochemical producers with integrated refining and polymer operations. Stable raw material availability and price competitiveness are critical for consistent BOPP film production.
- Key Players: LyondellBasell, SABIC, ExxonMobil Chemical, Reliance Industries Limited
- Logistics and Distribution: Efficient logistics and distribution networks ensure smooth transportation of BOPP films from manufacturers to converters and end-use industries. Strong warehousing, cold-chain-free handling, and global shipping capabilities support timely delivery.
- Key Players: DHL Supply Chain, Maersk, Kuehne+Nagel, DB Schenker
- Recycling and Waste Management: Recycling and waste management focus on collecting, reprocessing, and reducing BOPP film waste through mono-material and circular economy initiatives. Increasing investment in recycling infrastructure supports sustainable packaging goals.
- Key Players: Veolia, SUEZ, Waste Management Inc., Indorama Ventures
Segmental Insights
By Type
What Made The Plain Films Segment Dominate The Biaxially Oriented Polypropylene (BOPP) Market?
The plain films segment volume was valued at 5.9 million tons in 2025 and is projected to reach 8.4 million tons by 2035, expanding at a CAGR of 3.98% during the forecast period from 2025 to 2035. The plain films segment dominates the biaxially oriented polypropylene (BOPP) market, accounting for 58% of the total share because of their superior mechanical qualities, clarity, and adaptability. These films are highly favored for industrial food packaging and labeling applications because plain films are affordable and widely used in a variety of end-use industries. Manufacturers continue to concentrate on them.
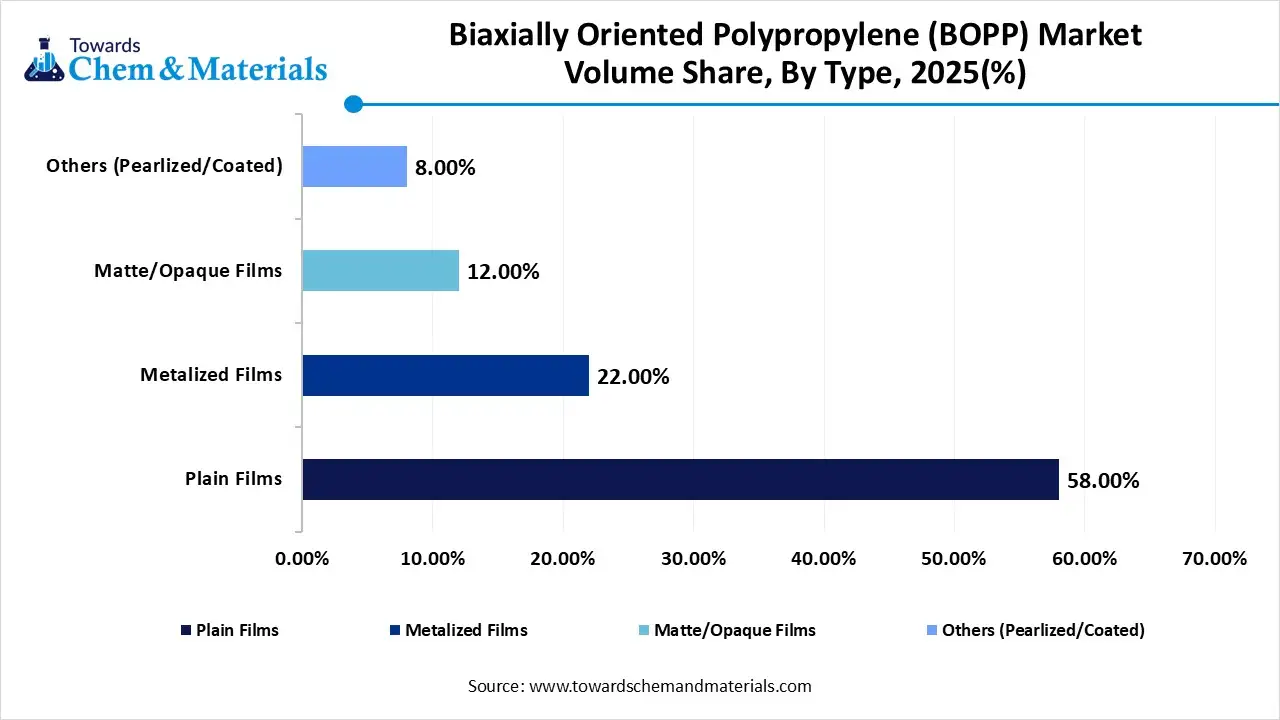
The Metallized BOPP films segment volume was valued at 2.2 million tons in 2025 and is projected to reach 3.5 million tons by 2035, expanding at a CAGR of 5.03% during the forecast period from 2025 to 2035. The Metallized BOPP films segment is expected to experience the fastest growth with 22% in the market during the forecast period, driven by their superior appeal and improved barrier qualities. Snacks, candies, and other perishable items that need long shelf lives, and eye-catching designs are increasingly being packaged in these films.
Biaxially Oriented Polypropylene (BOPP) Market Volume and Share By Type, 2025-2035
| By Type | Market Volume Share (%), 2025 | Market Volume ( Million Tons)2025 | Market Volume (Million Tons)2035 | CAGR(%) 2026-2035 | Market Volume Share (%), 2035 |
| Plain Films | 58.00% | 5.9 | 8.4 | 3.98% | 56.39% |
| Metalized Films | 22.00% | 2.2 | 3.5 | 5.03% | 23.41% |
| Matte/Opaque Films | 12.00% | 1.2 | 1.9 | 4.83% | 12.55% |
| Others (Pearlized/Coated) | 8.00% | 0.8 | 1.1 | 3.79% | 7.65% |
By Thickness
What Made 15-30 Microns Segment Dominate The Biaxially Oriented Polypropylene (BOPP) Market?
The 15–30-micron segment dominates the biaxially oriented polypropylene (BOPP) market, accounting for 64% of the total share. For the majority of packaging and labeling applications, this range is the recommended option because it strikes a balance between strength, flexibility, and printability. Its dominant position is strengthened by its steady performance and broad industry adoption.
The segment below 15 microns segment is expected to experience the fastest growth with 18% in the market during the forecast period, as producers look for lightweight options to reduce costs and promote sustainability. These thinner films are becoming more popular in contemporary retail applications and e-commerce packaging, where minimizing material consumption is a top concern.
By Production Process
What Makes Tenter Process Segment Dominate The Biaxially Oriented Polypropylene (BOPP) Market?
Tenter process segment dominates the biaxially oriented polypropylene (BOPP) market, accounting for 85% of the total share, because of its capacity to create superior dimensionally stable films. Tentered BOPP films are ideal for a variety of packaging and labelling applications because of their consistent thickness and superior mechanical qualities.
The tubular (bubble) process segment is expected to experience the fastest growth with 15% in the market during the forecast period, because it facilitates flexible film applications and low-cost production, emerging markets, and rising demand for specialty and lightweight films are driving its increasing uptake.
By Application
Why Did Wraps Segment Dominate The Biaxially Oriented Polypropylene (BOPP) Market?
The wraps segment dominates the biaxially oriented polypropylene (BOPP) market, accounting for 35% of the total share, mostly driven by the specifications for food packaging. The clarity, strength, and barrier qualities of BOPP make wraps ideal for safeguarding packaged and perishable foods. Its dominant share is reinforced by fast-moving consumer goods brands in steady demand.
The labels segment is expected to experience the fastest growth with 15% in the market during the forecast period, driven by the growing demand for superior eye-catching long-lasting packaging labels. The growth is especially noticeable in FMCG, personal care, and beverage products. The market is expanding more quickly due to the growing demand for high-end and ornamental labeling solutions.
By End User Industry
What Made The Food Packaging Segment Dominate The Biaxially Oriented Polypropylene (BOPP) Market?
The food packaging segment dominates the biaxially oriented polypropylene (BOPP) market, accounting for 48% of the total share, reflecting the widespread use of BOPP films in protecting perishable goods and extending shelf life. The global rise in packaged food consumption is the driving force behind this dominance. The demand for packaged and ready-to-eat foods is still being driven by fast urbanization and shifting lifestyles.
The pharmaceuticals segment is expected to experience the fastest growth with 10% in the market during the forecast period, since BOPP films are utilized for labels, protective wraps, and blister packs, guaranteeing product safety and adherence to legal requirements. Growth in this market is being driven by the rise in pharmaceutical production and the emphasis on safe packaging.
By Region
The Asia Pacific biaxially oriented polypropylene (BOPP) market size was valued at USD 56.20 billion in 2025 and is expected to be worth around USD 98.30 billion by 2035, exhibiting at a compound annual growth rate (CAGR) of 5.75% over the forecast period from 2026 to 2035.
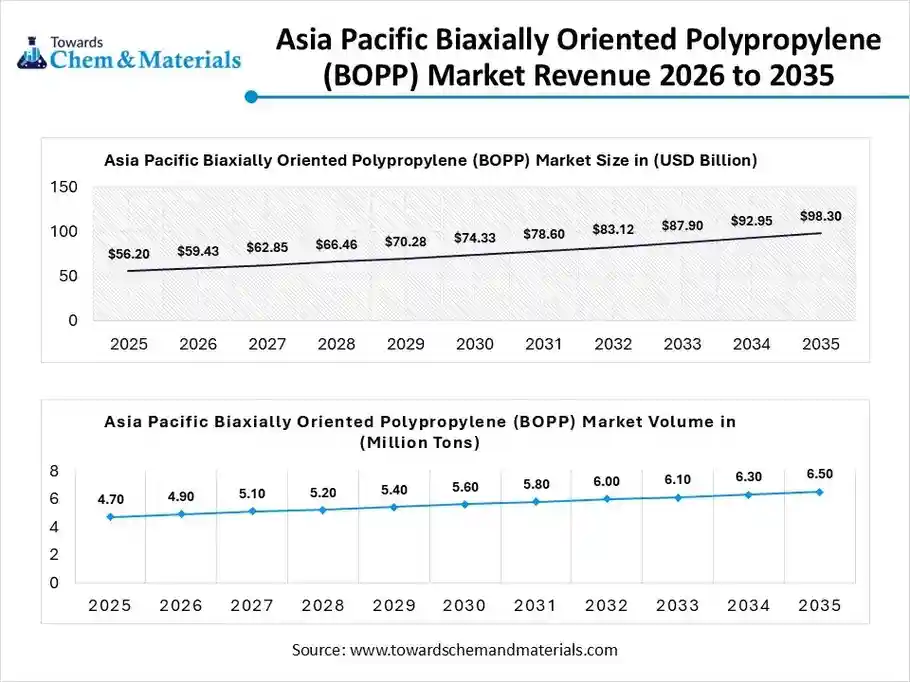
The Asia Pacific biaxially oriented polypropylene (BOPP) market volume was estimated at 4.7 million tons in 2025 and is projected to reach 6.5 million tons by 2035, growing at a CAGR of 3.83% from 2026 to 2035. Asia Pacific dominates the biaxially oriented polypropylene (BOPP) market, accounting for 46% of the total share, driven by strong growth in the FMCG and retail sectors, rapid industrialization, and high consumption of packaged foods. The area gains growing demand for flexible packaging, economic production, and large-scale manufacturing capabilities. To increase shelf life and aesthetic appeal, nations in the region are also implementing cutting-edge packaging technologies. Sustained market growth is further supported by robust export activity.
India Biaxially Oriented Polypropylene (BOPP) Market Trends
India is a key growth engine within the Asia Pacific because of the growing demand for packaged foods and pharmaceuticals, rising urbanization, and rising disposable income. BOPP films are being used more often in wraps and labels as organized retail and e-commerce grow. Investment in packaging materials is also being encouraged by government support for domestic manufacturing and food processing. Long-term demand is also supported by the move to recyclable and lightweight packaging.
Latin America Biaxially Oriented Polypropylene (BOPP) Market Trends
The Latin America biaxially oriented polypropylene (BOPP) market volume was estimated at 1.2 million tons in 2025 and is projected to reach 1.9 million tons by 2035, growing at a CAGR of 5.25% from 2026 to 2035.South America fastest growing with 10% market share, supported by growing retail infrastructure and an increase in packaged food consumption. The demand for premium and eye-catching packaging is driven by the growing presence of multinational FMCG brands. Additionally, the region is seeing a slow modernization of packaging standards. Adoption is further accelerated by growing awareness of adaptable and affordable packaging options.
Brazil Biaxially Oriented Polypropylene (BOPP) Market Trends
Brazil leads the South American BOPP market due to its sizable consumer base and robust food and beverage industry. BOPP films are becoming more and more popular in the nation for labeling snacks and confectionery. Supply capabilities are being strengthened by investments in innovative packaging and regional films production. Furthermore, BOPP film producers continue to have new opportunities due to the expansion of exports and contemporary retail formats.
Biaxially Oriented Polypropylene (BOPP) Market Volume and Share, By Region, 2025-2035
| By Region | Market Volume Share (%), 2025 | Market Volume ( Million Tons)2025 | Market Volume (Million Tons)2035 | CAGR(%) 2026-2035 | Market Volume Share (%), 2035 |
| North America | 18.00% | 1.8 | 2.7 | 4.39% | 18.12% |
| Europe | 16.00% | 1.6 | 2.5 | 4.88% | 16.81% |
| Asia Pacific | 46.00% | 4.7 | 6.5 | 3.83% | 44.12% |
| Latin America | 12.00% | 1.2 | 1.9 | 5.25% | 13.01% |
| Middle East & Africa | 8.00% | 0.8 | 1.2 | 4.22% | 7.94% |
Recent Developments
- In September 2025, to meet increasing demand for high-quality labels, new data highlighted how BOPP's treated surfaces strengthen adhesion, positioning it as a preferred option for food and beverage packaging where visual clarity and protection are essential.(Source: www.poly-source.com)
- In December 2025, The BOPP market size was expected to reach $31.27 billion in 2025, a strong growth trajectory from 2024, driven by advancements in technology and a shift towards sustainable packaging.(Source: www.einpresswire.com)
Top Companies
- Jindal Poly Films Ltd.
- Taghleef Industries
- Cosmo First (formerly Cosmo Films)
- UFlex Limited
- Oben Holding Group
- CCL Industries (Innovia Films)
- Toray Industries, Inc.
- Mitsubishi Chemical Group
- Inteplast Group
- Poligal S.A.
- Sibur Holding
- Polibak
- Zhejiang Kinlead Innovative Materials
- Ganesha Ecosphere (Bio-BOPP focus)
- Manucor S.p.A.
Segments Covered in the Report
By Type
- Plain Films
- Metalized Films
- Matte/Opaque Films
- Others (Pearlized/Coated)
By Thickness
- 15–30 Microns
- Below 15 Microns
- 30–45 Microns
- Above 45 Microns
By Production Process
- Tenter Process
- Tubular (Bubble) Process
By Application
- Wraps
- Bags & Pouches
- Tapes
- Labels
By End-User Industry
- Food Packaging
- Tobacco Packaging
- Consumer Goods & Personal Care
- Industrial & Electrical
- Pharmaceuticals
By Region
- North America
- Europe
- Asia Pacific
- South America
- Middle East & Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.