
U.S. Surfactants Market Size Analysis Report 2035
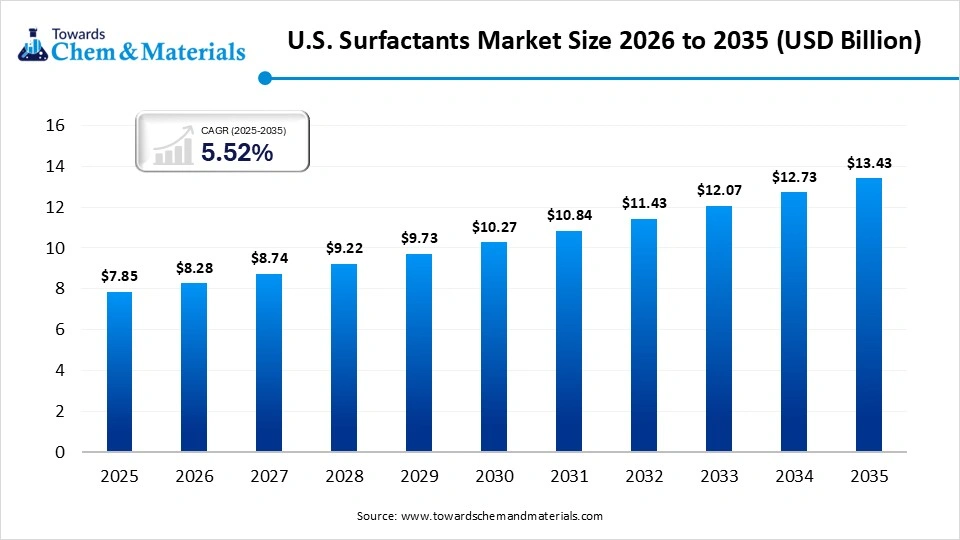
The U.S. surfactants market size is expected to reach USD 7.85 billion in 2025 and is expected to be worth around USD 11.63 billion by 2035, growing at a compound annual growth rate (CAGR) of 5.52% over the forecast period 2025 to 2035. The growing adoption of bio-based surfactants and the increasing demand for personal care drive the market growth.
Key Takeaways
- Midwest held approximately a 35% share in the U.S. surfactants market in 2024 due to the strong presence of the agricultural sector.
- South is growing at the fastest CAGR in the market during the forecast period due to the well-established oil & gas industry.
- By type, the anionic surfactants segment held approximately a 45% share in the U.S. surfactants market in 2024 due to the increasing demand for cleaning products.
- By type, the nonionic surfactants segment is expected to grow at the fastest CAGR in the market during the forecast period due to the rising environmental concerns.
- By origin, the synthetic surfactants segment held approximately a 70% share in the U.S. surfactants market in 2024 due to the growing production of industrial cleaning.
- By origin, the bio-based/green surfactants segment is expected to grow at the fastest CAGR in the market during the forecast period due to the increasing preference for organic products.
- By form, the liquid surfactants segment held approximately a 60% share in the U.S. surfactants market in 2024 due to the growing utilization of shampoos and body washes.
- By form, the powder/granular surfactants segment is expected to grow at the fastest CAGR in the market during the forecast period due to the better emulsification properties.
- By end user industry, the consumer goods manufacturers segment held approximately a 55% share in the U.S. surfactants market in 2024 due to the growing demand for cosmetics & personal care products.
- By end user industry, the agriculture & food industry segment is expected to grow at the fastest CAGR in the market during the forecast period due to the increasing demand for food.
Role of U.S Surfactants in Industrial Applications & Everyday Life
The U.S. Surfactants Market covers the production, distribution, and application of surface-active agents used to reduce surface tension between liquids, solids, or gases. Surfactants are widely used as dispersing, cleaning, and emulsifying agents. Surfactants are categorized into different types, like cationic, amphoteric, anionic, and nonionic.
They are derived from synthetic petrochemical feedstocks or bio-based renewable sources. Surfactants are widely used in detergents, personal care products, industrial cleaners, agricultural formulations, oilfield chemicals, and various specialty applications. The growing consumer focus on environmental impact increases demand for bio-based surfactants.
Factors like strong demand for household cleaning products, increasing consumption of personal care products, growing demand for biodegradable surfactants, and growth in the industrial applications contribute to the growth of the U.S. surfactants market.
- According to OEC World, the United States exported $1.02B of organic surfactant for washing, cleaning preparations nes in 2023.(Source: oec.world)
- According to Volza’s Export data, The Dow Chemical Company C O Laticr accounted maximum export share of surfactants with 1106 shipments.(Source: www.volza.com)
- According to Volza’s Export data, from April 2024 to March 2025, the United States exported 333 shipments of the chemical surfactant with a growth rate of 22%.(Source: www.volza.com)
- According to OEC World, the United States exported $3.81B of cleaning products in 2024.(Source: oec.world)
Growing Personal Care Industry Surges Demand for Surfactants
The growing personal care industry and increasing focus on personal hygiene increase demand for various personal care products that require surfactants. The strong consumer focus on grooming and increasing spending on personal care items increases demand for surfactants. The high demand for items like lotions, shampoos, and body washes increases the adoption of surfactants for properties like emulsifying, cleansing, and foaming. The increasing shift towards natural and organic products increases demand for bio-based surfactants. The increasing consumer demand for skin-compatible, foaming, and conditioning products fuels demand for surfactants.
The increasing spending on premium personal care products increases demand for specialized surfactants. The strong consumer focus on specialty cosmetics, skincare, and haircare increases demand for diverse products. The growing utilization of products like soaps, creams, makeup, shampoos, and lotions increases demand for surfactants. The growing personal care industry is a key driver for the growth of the U.S. surfactants market.
Market Trends
- Growing Demand for Home Care Products:- The increasing demand for various home care products like all-purpose cleaners, laundry detergents, bathroom cleaners, and dishwashing liquids increases demand for surfactants for removing dirt and stains from surfaces.
- Increasing demand for Bio-Based Surfactants:- The growing environmental concerns and increasing focus on sustainability increase demand for bio-based surfactants. The utilization of bio-based surfactants helps in reducing the carbon footprint.
- Growing Oil & Gas Industry:- The growing expansion of the oil & gas industry increases demand for surfactants for applications like oil spill remediation, enhanced oil recovery, and drilling operations.
Report Scope
| Report Attribute | Details |
| Market Size in 2025 | USD 7.85 billion |
| Expected Size by 2035 | USD 13.43 billion |
| Growth Rate from 2025 to 2034 | CAGR 5.52% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Segment Covered | By Type, By Origin, By Form, By End-User Industry, By region |
| Key Companies Profiled | Chemical Associates, Air Products and Chemicals, BASF, Kraton Corporation, Evonik Industries, SABIC, Univar Solutions, Clariant, Solvay, Croda International, Stepan Company, Eastman Chemical Company, Dow, Nouryon, Huntsman Corporation |
Market Opportunity
Growing Expansion of the Healthcare Industry Unlocks Market Opportunity
The growing expansion of the healthcare sector in the United States and the increasing demand for healthcare services fuel the adoption of surfactants for healthcare applications. The increasing demand for an efficient drug delivery system increases the adoption of surfactants for enhancing the bioavailability and solubility of drugs. The growing development of new drugs and the creation of various pharmaceutical products increases demand for surfactants.
The growing adoption of disinfectants in healthcare facilities like clinics & hospitals increases demand for surfactants. The growth in disinfection and sterilization procedures increases the adoption of surfactants. The increasing production of pharmaceutical products like injectable solutions, creams, and lotions increases demand for surfactants. The growth in the development of diagnostic tools and medical devices increases demand for surfactants. The growing expansion of the healthcare industry creates an opportunity for the growth of the U.S. surfactants market.
Market Challenge
Fluctuations in Raw Material Prices Limit the Expansion of the Market
Despite several benefits of the surfactants in the United States in various industries, the fluctuations in raw material prices restrict the growth of the market. Factors like supply chain disruptions, volatility in crude oil prices, and stricter environmental regulations are responsible for fluctuations in raw materials prices. The increasing demand for crude oil derived from fatty alcohols and petrochemicals increases the cost.
The stricter environmental regulations for the production of surfactants and regulations on the use of palm oil increase the raw materials cost. The fluctuations in the prices of raw materials like petrochemicals, natural oils, and fatty acids directly affect the market. Supply chain disruptions due to factors like unforeseen circumstances, natural disasters, and political instability increase the cost of raw materials. The fluctuations in raw material prices hamper the growth of the U.S. surfactants market.
Regional Insights
Midwest U.S. Surfactants Market Trends
The Midwest region dominated the U.S. surfactants market in 2024. The well-established agriculture sector increases demand for agrochemicals like fungicides & herbicides that require surfactants. The increasing demand for automotive lubricants, textile treatments, and other products increases the adoption of surfactants. The growing demand for food processing and manufacturing increases demand for surfactants for use as processing aids & food additives.
The increasing adoption of personal care products increases demand for surfactants. The growing manufacturing in sectors like chemicals, automotive, and plastics increases demand for surfactants, driving the overall growth of the market.
South U.S. Surfactants Market Trends
The South region is the fastest-growing in the market during the forecast period. The well-developed oil & gas sector increases demand for surfactants for drilling fluids & enhanced oil recovery. The growing expansion of the agriculture sector and the focus on enhancing crop yields increase demand for surfactants. The increasing demand for home care & personal care products like shampoos, detergents, and soaps increases the adoption of surfactants. The growing development of green surfactants and advancements in surfactant production support the overall growth of the market.
Segmental Insights
By Type
Why did the Anionic Surfactants Segment Dominate the U.S. Surfactants Market?
The anionic surfactants segment dominated the U.S. surfactants market in 2025, The growing demand for cleaning products like dish soaps & laundry detergents increases demand for anionic surfactants. The increasing adoption of linear alkylbenzene sulfonate anionic surfactant in cleaning products helps market growth. The growing spending on personal care products like body washes and shampoos increases demand for anionic surfactants. The growing demand for home care products and the affordability of anionic surfactants drive the overall growth of the market. The nonionic surfactants segment is the fastest-growing in the market during the forecast period. The stringent environmental regulations and growing environmental concerns increase demand for nonionic surfactants.
The increasing consumer preference for eco-friendly products increases the adoption of nonionic surfactants in various products. The increasing demand for hard surface cleaners & laundry detergents increases the adoption of nonionic surfactants. The growing demand for nonionic surfactants in applications like industrial cleaning, personal care, and agrochemicals supports the overall growth of the market.
By Origin
How Synthetic Surfactants Segment Held the Largest Revenue Share of the U.S. Surfactants Market?
The synthetic surfactants segment held the largest revenue share of the U.S. surfactants market in 2024. The increasing demand for household cleaning products and detergents increases the demand for synthetic surfactants. The strong focus on removing stains and dirt increases demand for synthetic surfactants, helping the market growth. Synthetic surfactants have properties like dispersing abilities, foaming, and emulsification. They are made up of petrochemicals and are suitable for large applications. The growing demand for industrial cleaning and personal care products drives the overall growth of the market.
The bio-based/green surfactants segment is experiencing the fastest growth in the market during the forecast period. The growing consumer shift towards natural and clean-label products increases demand for bio-based/green surfactants. The growing consumer awareness about environmental impact and focus on biodegradability increases the adoption of bio-based/green surfactants. The growing demand for organic personal care products like soaps, shampoos, and lotions increases demand for bio-based/green surfactants. The increasing demand for bio-based surfactants in home care, industrial cleaning, and agricultural products supports the overall growth of the market.
By Form
What Made the Liquid Surfactants Segment Dominate the U.S. Surfactants Market?
The liquid surfactants segment dominated the U.S. surfactants market in 2024. The growing demand for various cleaning agents like detergents, soaps, and other products increases demand for liquid surfactants. The increasing spending on personal care products like body washes & shampoos increases the adoption of liquid surfactants, helping the overall growth of the market. Liquid surfactants are easily combined with any formulation, and they enable effective cleaning. The growing expansion of the food & beverage industry increases demand for liquid surfactants, driving the overall growth of the market.
The powder/granular surfactants segment is the fastest-growing in the market during the forecast period. The strong focus on removing grime, dirt, and grease increases demand for powder/granular surfactants. The growing awareness about personal hygiene and the increasing demand for grooming products increase the adoption of powder surfactants. These surfactants offer better emulsification and wetting. The growing demand for powder surfactants across applications like pharmaceuticals, textiles, oil & gas, food & beverages, and home care supports the overall growth of the market.
By End-User Industry
Which End-User Industry Held the Largest Share of the U.S. Surfactants Market?
The consumer goods manufacturers segment held the largest revenue share of the U.S. surfactants market in 2024. The growing demand for industrial cleaning & household cleaning products like dishwashing liquids, disinfectants, laundry detergents, and surface cleaners increases demand for surfactants. The increasing importance of sanitization and growing demand for premium cleaning products increase the adoption of surfactants. The strong focus on grooming increases demand for personal care items like body washes, shampoos, and facial cleansers that require surfactants. The growth in online buying of cosmetic products and home care products increases the adoption of surfactants, driving the overall growth of the market.
The agriculture & food industry segment is experiencing the fastest growth in the market during the forecast period. The increasing demand for food and the growing demand for higher crop yields increase the demand for surfactants for various agricultural applications. The growing utilization of surfactants in agrochemicals like fungicides, pesticides, and herbicides helps the market growth. The ongoing advancements in farming, like drip irrigation and precision farming, increase demand for surfactants. The growing expansion of the food & beverage industry and increasing demand for various food products like salad dressings, baked goods, mayonnaise, and ice cream increase demand for surfactants, supporting the overall growth of the market.
U.S. Surfactants Market Value Chain Analysis
Chemical Synthesis and Processing
The chemical synthesis of surfactants involves the combination of certain compounds or molecules with hydrophobic and hydrophilic properties.
- Key Players:- Stephan Company, Ashland Global Holdings, Dow, and Huntsman
Distribution to Industrial Users
Surfactants are delivered to industries through various distribution channels, including direct sales, online marketplaces, specialized chemical suppliers, and distributors.
- Key Players:- BASF Corporation, Stephan Company, and Huntsman Corporation.
Regulatory Compliance and Safety Monitoring
The Environmental Protection Agency provides regulations for surfactants in the United States under the Toxic Substances Control Act. TSCA mandates reports on the environmental and human health hazards.
Recent Developments
- In May 2025, Pilot Chemical collaborated with Novvi to launch biobased surfactants, alpha olefin sulfonate, in the United States. The surfactants are useful in industries like personal care, household, and institutional & industrial purposes.(Source: www.fuelsandlubes.com)
- In June 2025, AmphiStar collaborated with Kensing to launch biosurfactants in North America’s personal care market. The product range is widely used in creams, body wash, body lotions, make-up removers, shampoos, and other products.(Source: www.ofimagazine.com)
Top Companies List
- Chemical Associates
- Air Products and Chemicals
- BASF
- Kraton Corporation
- Evonik Industries
- SABIC
- Univar Solutions
- Clariant
- Solvay
- Croda International
- Stepan Company
- Eastman Chemical Company
- Dow
- Nouryon
- Huntsman Corporation
Segments Covered
By Type
- Anionic Surfactants
- Cationic Surfactants
- Nonionic Surfactants
- Amphoteric/Zwitterionic Surfactants
By Origin
- Synthetic Surfactants
- Bio-Based/Green Surfactants
By Form
- Liquid Surfactants
- Powder/Granular Surfactants
- Paste/Gel Surfactants
By End-User Industry
- Consumer Goods Manufacturers
- Industrial & Institutional Cleaning Service Providers
- Agriculture & Food Industry
- Oil & Gas Industry
- Chemical Formulators
By region
- Midwest
- Northeast
- South
- West
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.