
U.S. Nitrogenous Fertilizer Market Size, Competitive Landscape Analysis Report 2035
The U.S. nitrogenous fertilizer market size is projected to reach USD 12.19 billion by 2025 to USD 21.52 billion by 2035, growing at a CAGR of 5.85%. In terms of volume, the market is projected to grow from 12,460.76 kilo tons in 2025 to 16,503.93 kilo tons by 2035. growing at a CAGR of 2.85% from 2026 to 2035.The increasing need for better crop yield and ongoing government initiatives towards modern farming is fueling the industry's growth in the current period.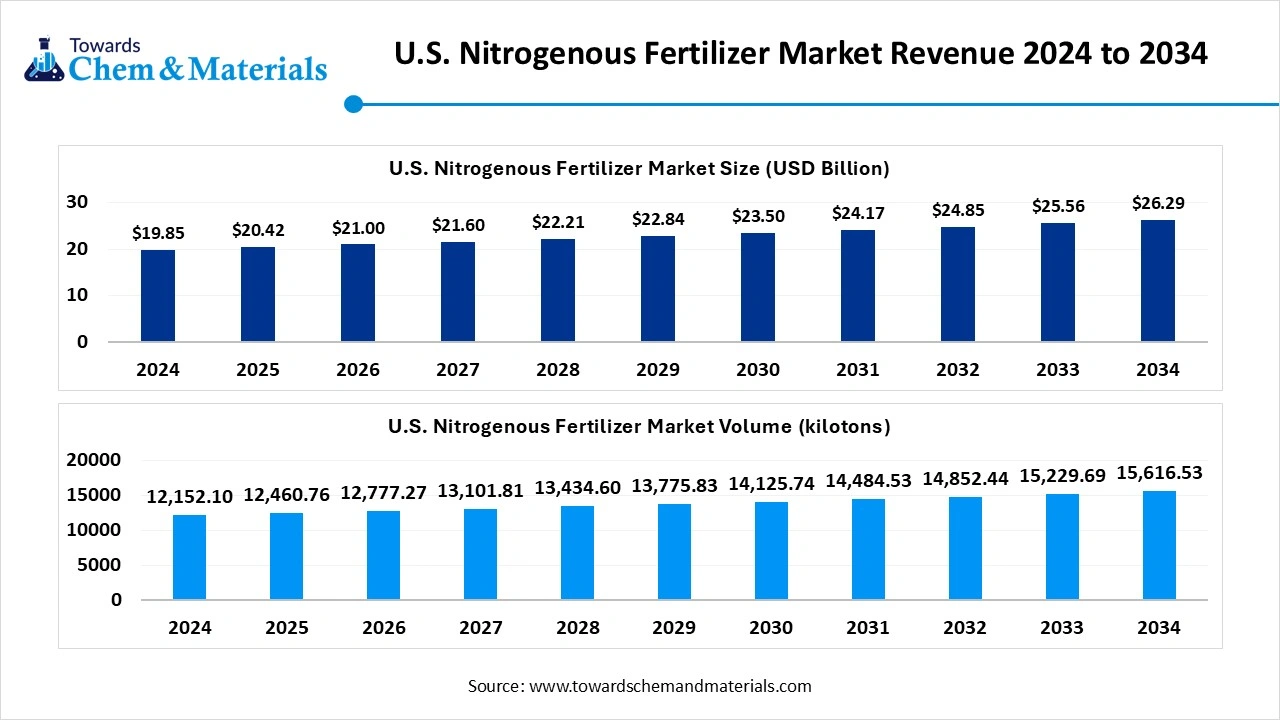
Key Takeaways
- By type, the urea segment emerged as the top-performing segment in 2025 due to its high nitrogen content at a lower cost.
- By type, the NPK segment is likely to experience notable growth during the forecast period, akin to its balanced mix of essential nutrients.
- By application, the agriculture application segment dominated the market in 2025, owing to farming is the largest consumer of nitrogen-based products.
- By application, the industrial application segment is projected to grow significantly over the forecast period due to the expanding applications beyond farming.
Market Overview
Nutrient-Rich Fertilizers Drive the Strong Adoption Across U.S. Farmlands
The U.S. nitrogenous fertilizers market is expected to see rapid growth owing to the increasing need for better crop yield in the current period. Having enriched nutrient qualities is specifically driving the demand for nitrogenous fertilizers in the region, as nitrogenous fertilizers have played a major role in healthy crop development in recent years. Also, the farmers who produce wheat, soybeans, and corn have increasingly been using this fertilizer in recent years, which is continuously providing a higher consumer base in the current period. Furthermore, the steady governmental support and technology advancements are anticipated to lead the future industry growth in the coming years.
What is Driving the Growth of the Nitrogenous Fertilizers Industry in the United States?
The increased governmental subsidies and support for the farming sector are driving U.S. nitrogenous fertilizers market growth in the current period. Moreover, several federal and state programs are actively providing attractive subsidies in the region nowadays while promoting sustainable farming practices. Also, several fertilizer producers have been increasingly observed in research and have launched innovative and effective product lines in the past few years. Furthermore, these supportive policies can reduce the farmers' burden on farmers’ components like the cost of fertilizers, funding for soil improvement, and others, while creating stable demand for this essential fertilizer, like nitrogen-based fertilizers, in recent years, as industry has grown.
Market Trends
- The increasing adoption of precision agriculture tools is spearheading the industry growth in the current period. Moreover, farmers are increasingly using these tools for the application of fertilizers efficiently. Also, it includes technology-advanced equipment like drones, smart sensors, and others, which can guide farmers in the use of nitrogen at the right time with the right amount.
- The sudden surge of eco-friendly nitrogen fertilizers has increasingly driven industry growth in recent years. Also, governments are heavily promoting sustainable agriculture practices, which are heavily contributing to the growth of the market. Also, several companies are developing nitrogen fertilizers that release nitrogen slowly after the application, which supports eco-friendly farming in the current period.
- The introduction of digital platforms can immediately contribute to market growth, as per the recent industry observation. Several farmers are increasingly using mobile applications and various software to track their crop yield. Thus, these digital platforms can help and suggest to farmers a better application of nitrogen with data data-driven approach in the future.
Report Scope
| Report Attributes | Details |
| Market size and volume in 2026 | USD 12.90 billion / 12,815.89 Kilo Tons |
|
Market size and volume in 2035 |
USD 21.52 billion / 16,503.93 Kilo Tons |
| Growth Rate from 2025 to 2035 | 5.85% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Segment Covered | By Product Type, By End Use |
| Key Companies Profiled | CF Industries Holdings, Inc., The Mosaic Company, Yara International, Koch Fertilizer, LLC, LSB Industries, Inc. |
Market Opportunity
Tailored Fertilizer Strategies Poised to Build Loyal Consumer Base
The development of the customized fertilizer blend is expected to create lucrative opportunities for U.S. nitrogenous fertilizers market in the coming years. This fertilizer blend depends on the soil and crop type for the individual farmer's community. Also, this initiative is likely to build a strong relationship between cooperatives and farmers, which is anticipated to lead the heavy consumer base to the industry in the upcoming years. Moreover, this advancement can open the roadmap for premium pricing and the value-added service in the coming years, as per future expectations.
Market Challenge
Natural Gas Price Swings Threaten Stability in Nitrogen Fertilizer Market
The price volatility of natural gas is projected to hamper the U.S. nitrogenous fertilizers market growth during the forecast period. Natural gas plays a major role in the production of nitrogen fertilizers, specifically in production and ammonia. This price fluctuation can impact the whole product pricing, which is expected to create cost challenges for the farmers and sales challenges for the producers in the coming years. Furthermore, companies can face delays and supply chain disruptions, which are likely to impact the overall industry environment in the future.
Segmental Insights
Product Type Insights
How Has Urea Maintained Its Top Position in the U.S. Nitrogenous Fertilizers Market?
The urea segment held the largest share of the market in 2024, due to its high nitrogen content at a lower cost in the current period. Also, it is easy to produce, store, and transport, making it a preferred choice for farmers across the country. Moreover, urea quickly provides nitrogen to crops, which helps boost plant growth and yields. It can also be applied in different ways by spreading, spraying, or through irrigation systems, which adds to its flexibility. In recent years, the affordability and fast-acting results of urea have made it a go-to fertilizer for major crops like corn and wheat. Moreover, farmers trust it because it’s effective and widely available.
The NPK compound segment expects substantial growth in the market during the forecast period, owing to its balanced mix of three essential nutrients, such as nitrogen (N), phosphorus (P), and potassium (K). Also, these blends help crops grow stronger and healthier by supporting root development, flowering, and disease resistance. Moreover, as farmers move toward more efficient and smart farming practices, they prefer fertilizers that give complete nutrition in one application. NPK compounds reduce the need for multiple products, saving time and labor. With precision farming tools and soil testing becoming more common, customized NPK blends that match specific crop and soil needs are gaining popularity.
End Use Insights
What Makes Agriculture Use Segment the Top Contributor to U.S. Nitrogenous Fertilizer Sales?
The agriculture use segment held the dominant share of the U.S. nitrogenous fertilizers market in 2024 due as farming is the largest consumer of nitrogen-based products. Crops like corn, wheat, and soybeans need high amounts of nitrogen to grow well and produce more yield. Farmers across the U.S., especially in the Midwest, rely on fertilizers to meet growing food and biofuel demands. Nitrogen fertilizers help increase crop quality, support healthy plant growth, and make land use more efficient. In recent years, due to rising population and food export needs, farmers have focused on improving productivity per acre, which increases the use of fertilizers. Agricultural subsidies and crop insurance programs also support fertilizer use. Since nitrogen is essential for plant growth, its importance in daily farming operations remains high, as per the observation.
The industrial use segment expects significant growth in the market during the predicted timeframe, owing to expanding applications beyond farming. Industries use nitrogen products like urea and ammonium nitrate in making resins, adhesives, plastics, and pollution control chemicals. As manufacturing, construction, and automotive sectors grow, so does the need for these chemical ingredients. Urea is also used in diesel exhaust fluid (DEF), which helps reduce vehicle emissions, a growing need with stricter air quality regulations. Additionally, nitrogen-based chemicals are used in mining, refrigeration, and textile industries. Industrial buyers prefer consistent supply and high-quality materials, which encourages long-term contracts and stable demand. With farming practices becoming more efficient and regulated, the non-agricultural demand for nitrogen products offers a strong growth path.
Manufacturers Perspective
After the country’s industry observation, demand for nitrogen fertilizers is strong due to the country's large-scale farming infrastructure, and the increasing need for high-yield crops like wheat and corn. Moreover, the manufacturers must adopt sustainable production facilities as the government is increasingly implementing tighter, environmentally friendly rules, and ongoing raw materials price fluctuation. Also, manufacturers can create products that can match the modern precision farming tools, which is expected to create significant opportunities for manufacturers in the coming years. Furthermore, investment in research and development activities can give the first mover advantages to the producers, as per the observation of ongoing industry advancements.
Recent Developments
- In February 2025, Ther Willbur-Ellis unveiled their latest production of the organic nitrogen fertilizer recently. Moreover, fertilizer includes ammonium nitrate for a greater crop yield, as per the company's claim. Also, this sustainable-derived product is named Ben Vireo Terra Lux as per the report published by the company. (Source: growingproduce )
- In October 2024, the USDA introduced its latest fertilizer transportation dashboard to guide the transportation market with publicly available data. The dashboard includes innovative features like indicators for fertilizer production and others, as per the published report.(Source: farmweekknow )
Top Companies list
- CF Industries Holdings, Inc.
- The Mosaic Company
- Yara International
- Koch Fertilizer,
- LLC
- LSB Industries, Inc.
Segment Covered in the report
By Product Type
- Urea
- NPK Compound
- Nitrates
- Ammonium Phosphate
- Others
By End Use
- Agricultural Use
- Industrial Use
- Residential And Consumer Use
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.
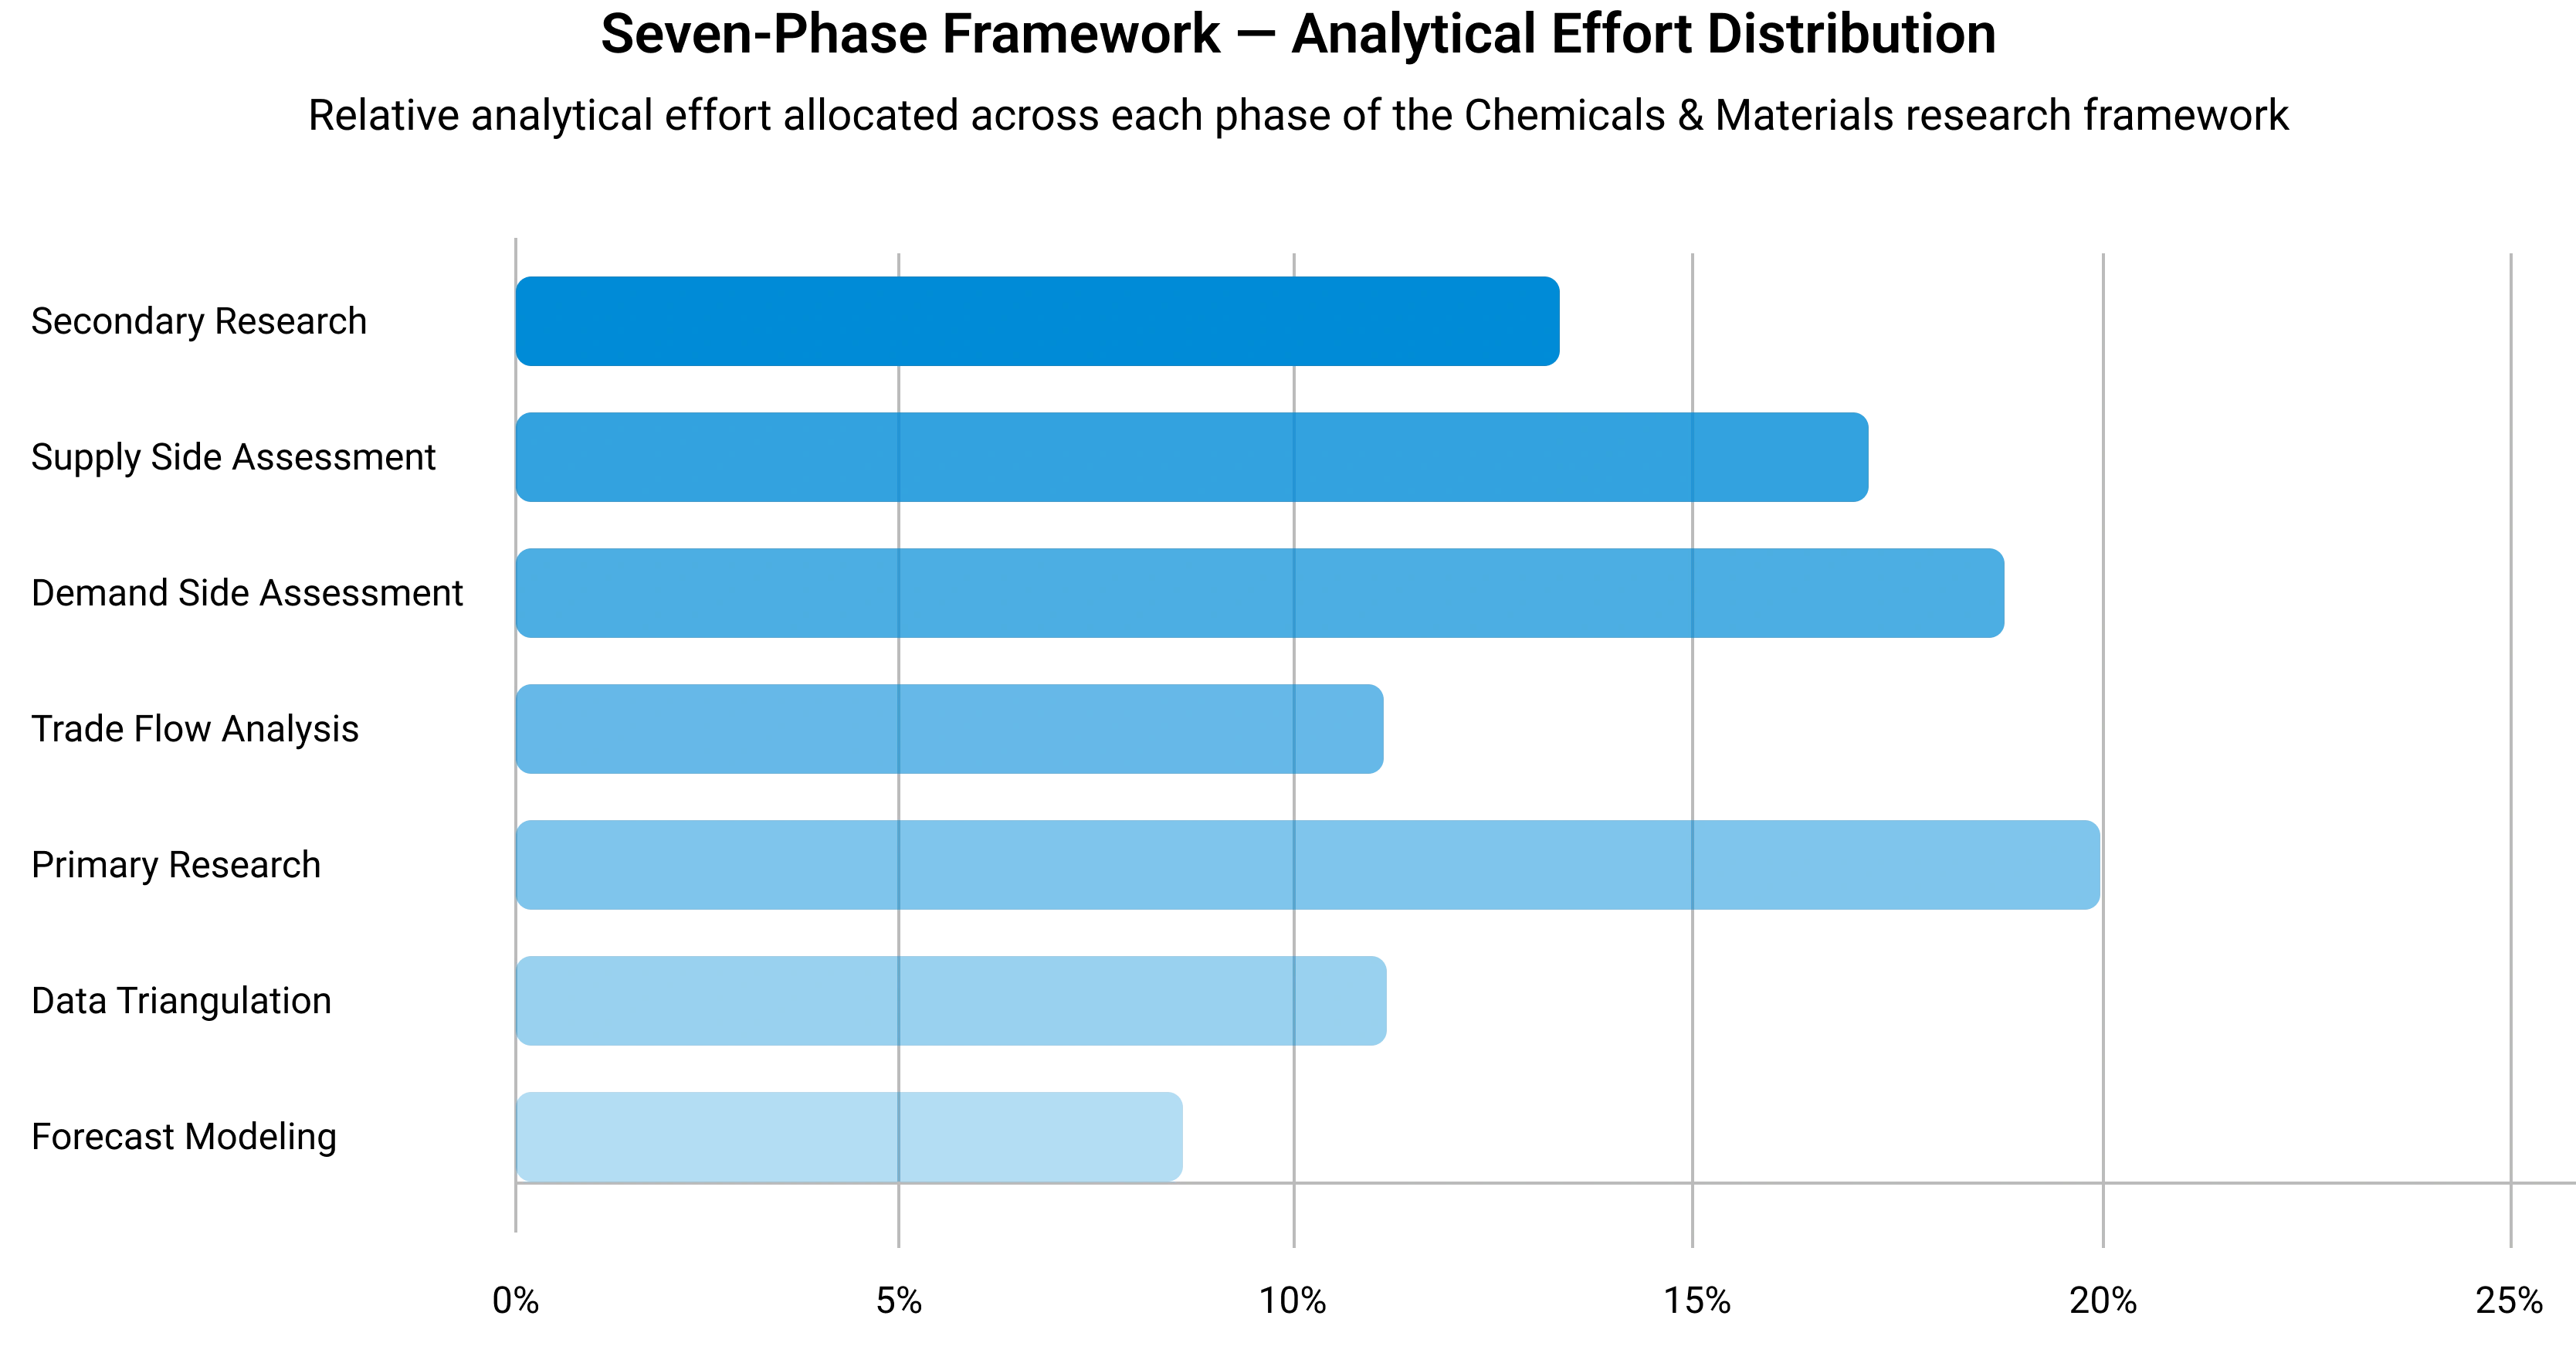
Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework
Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
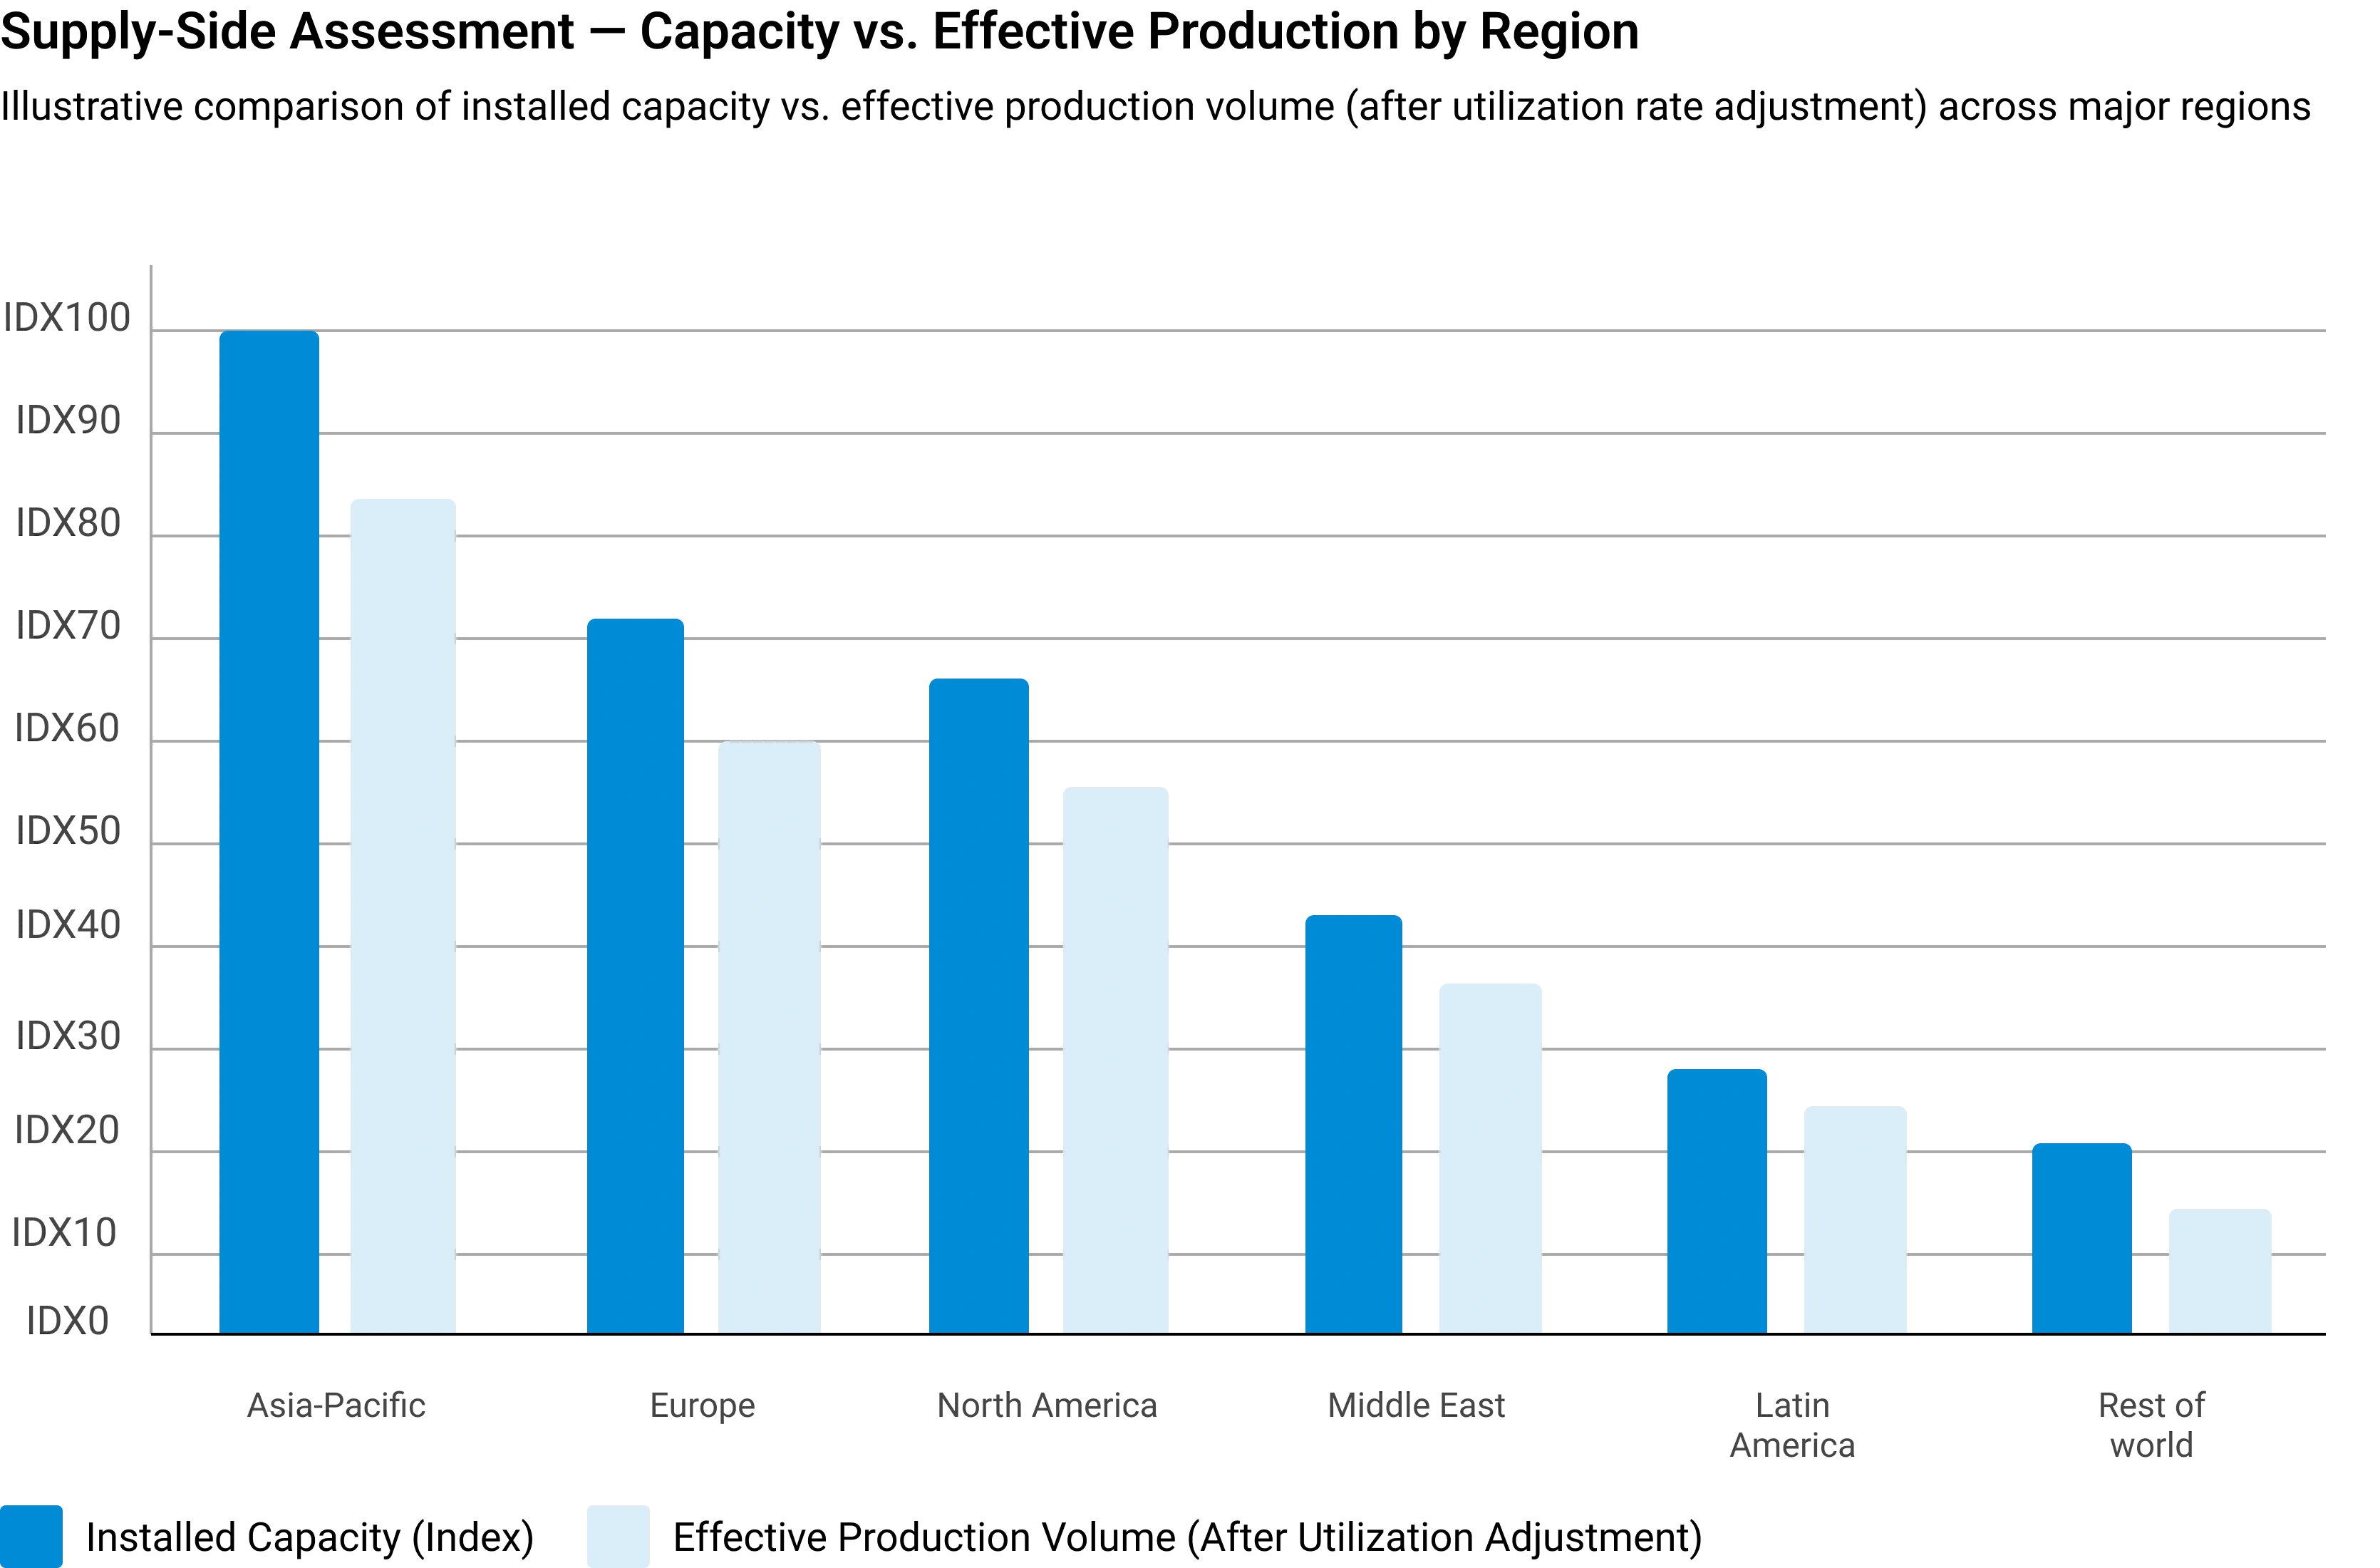
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions
Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
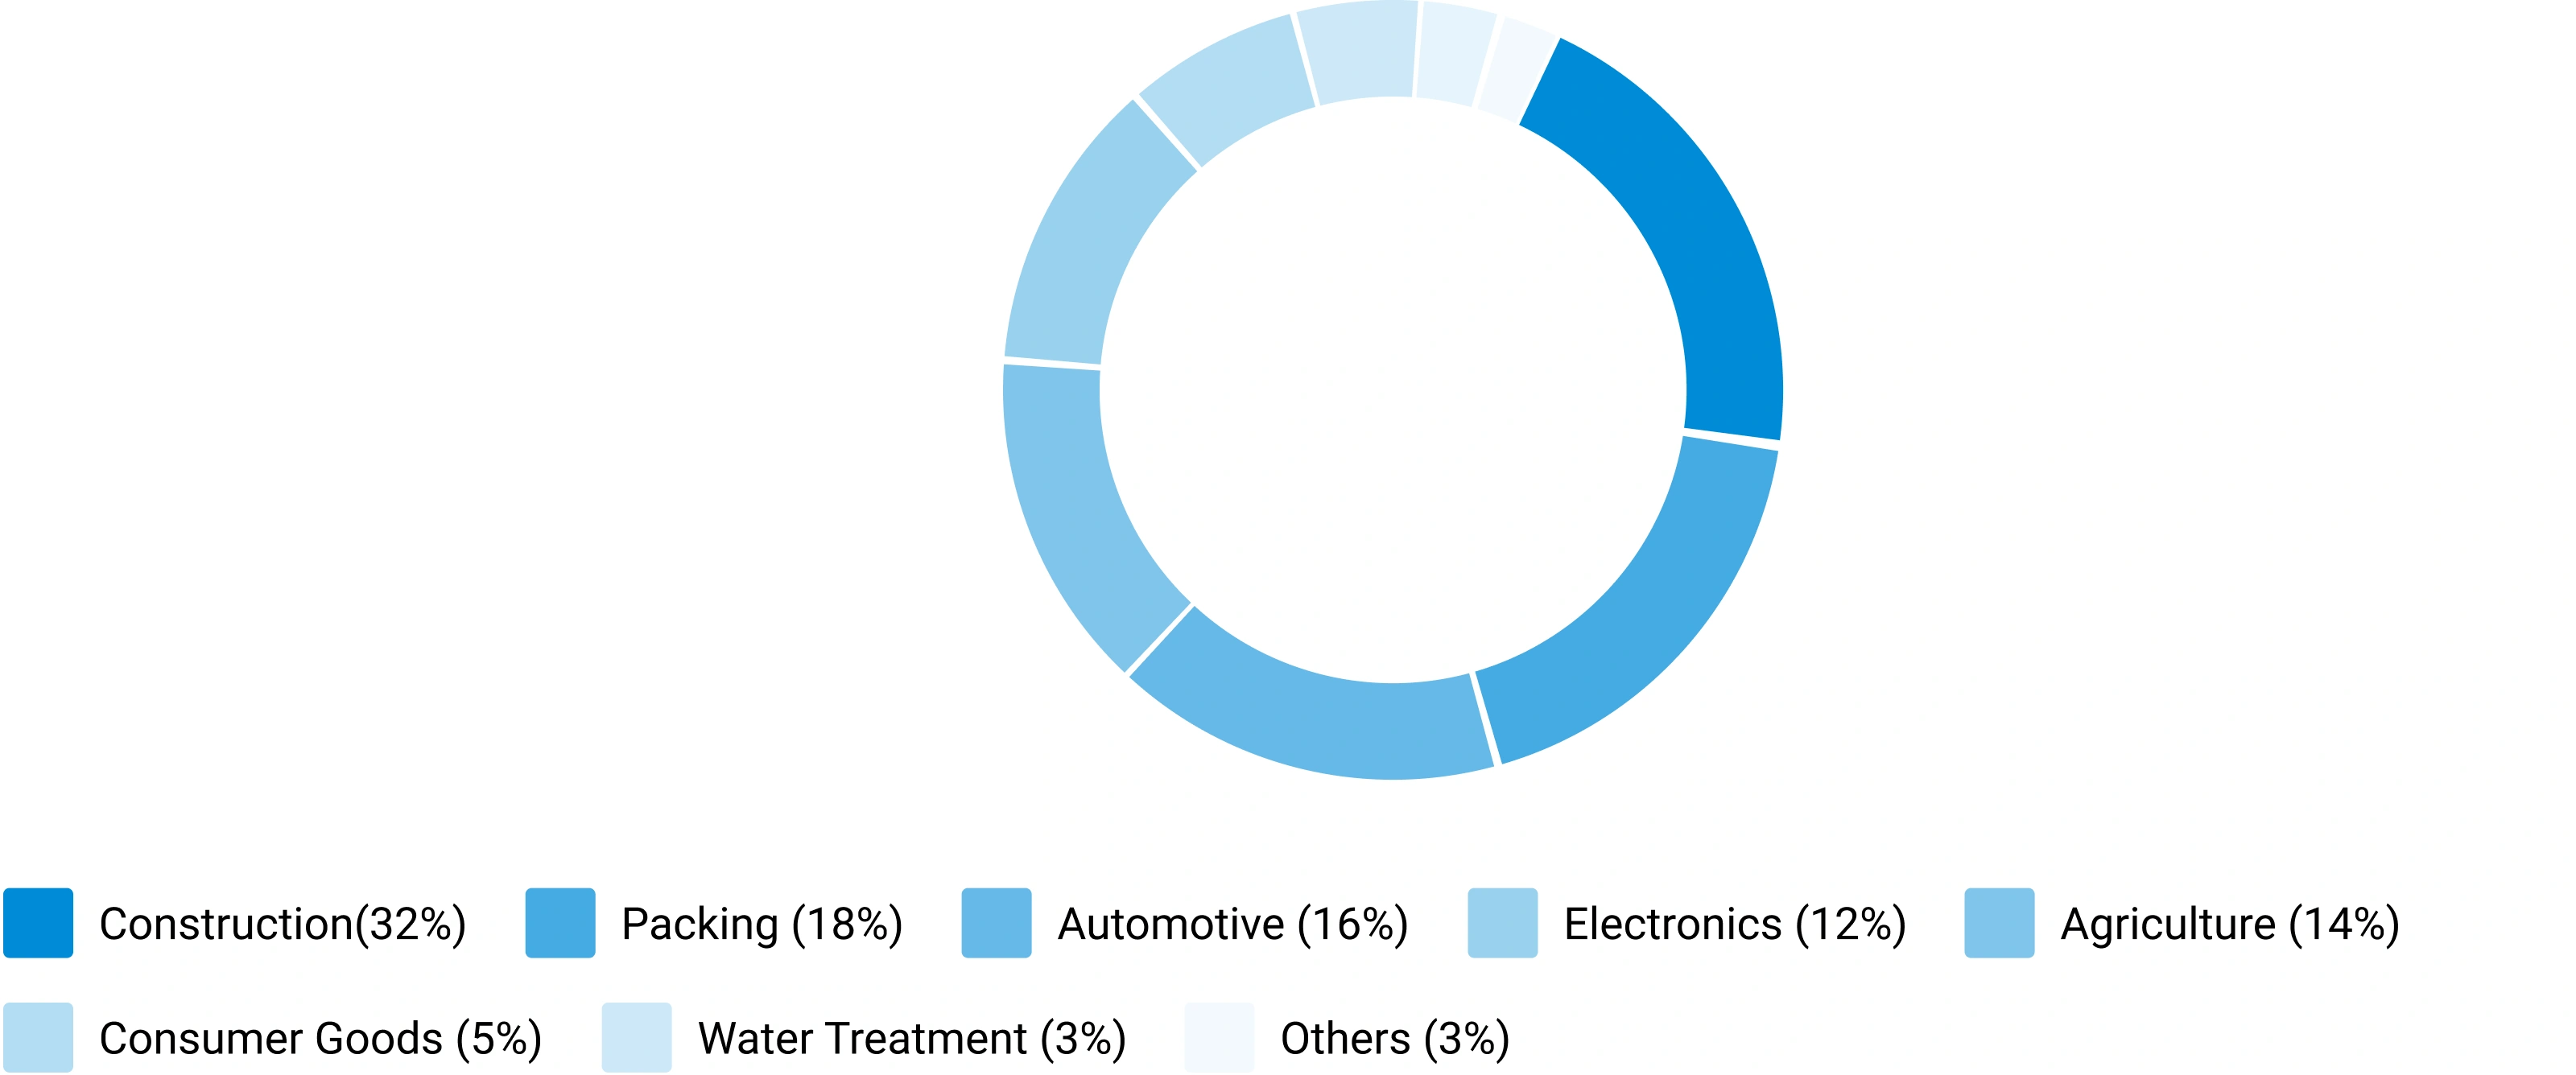
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries
Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
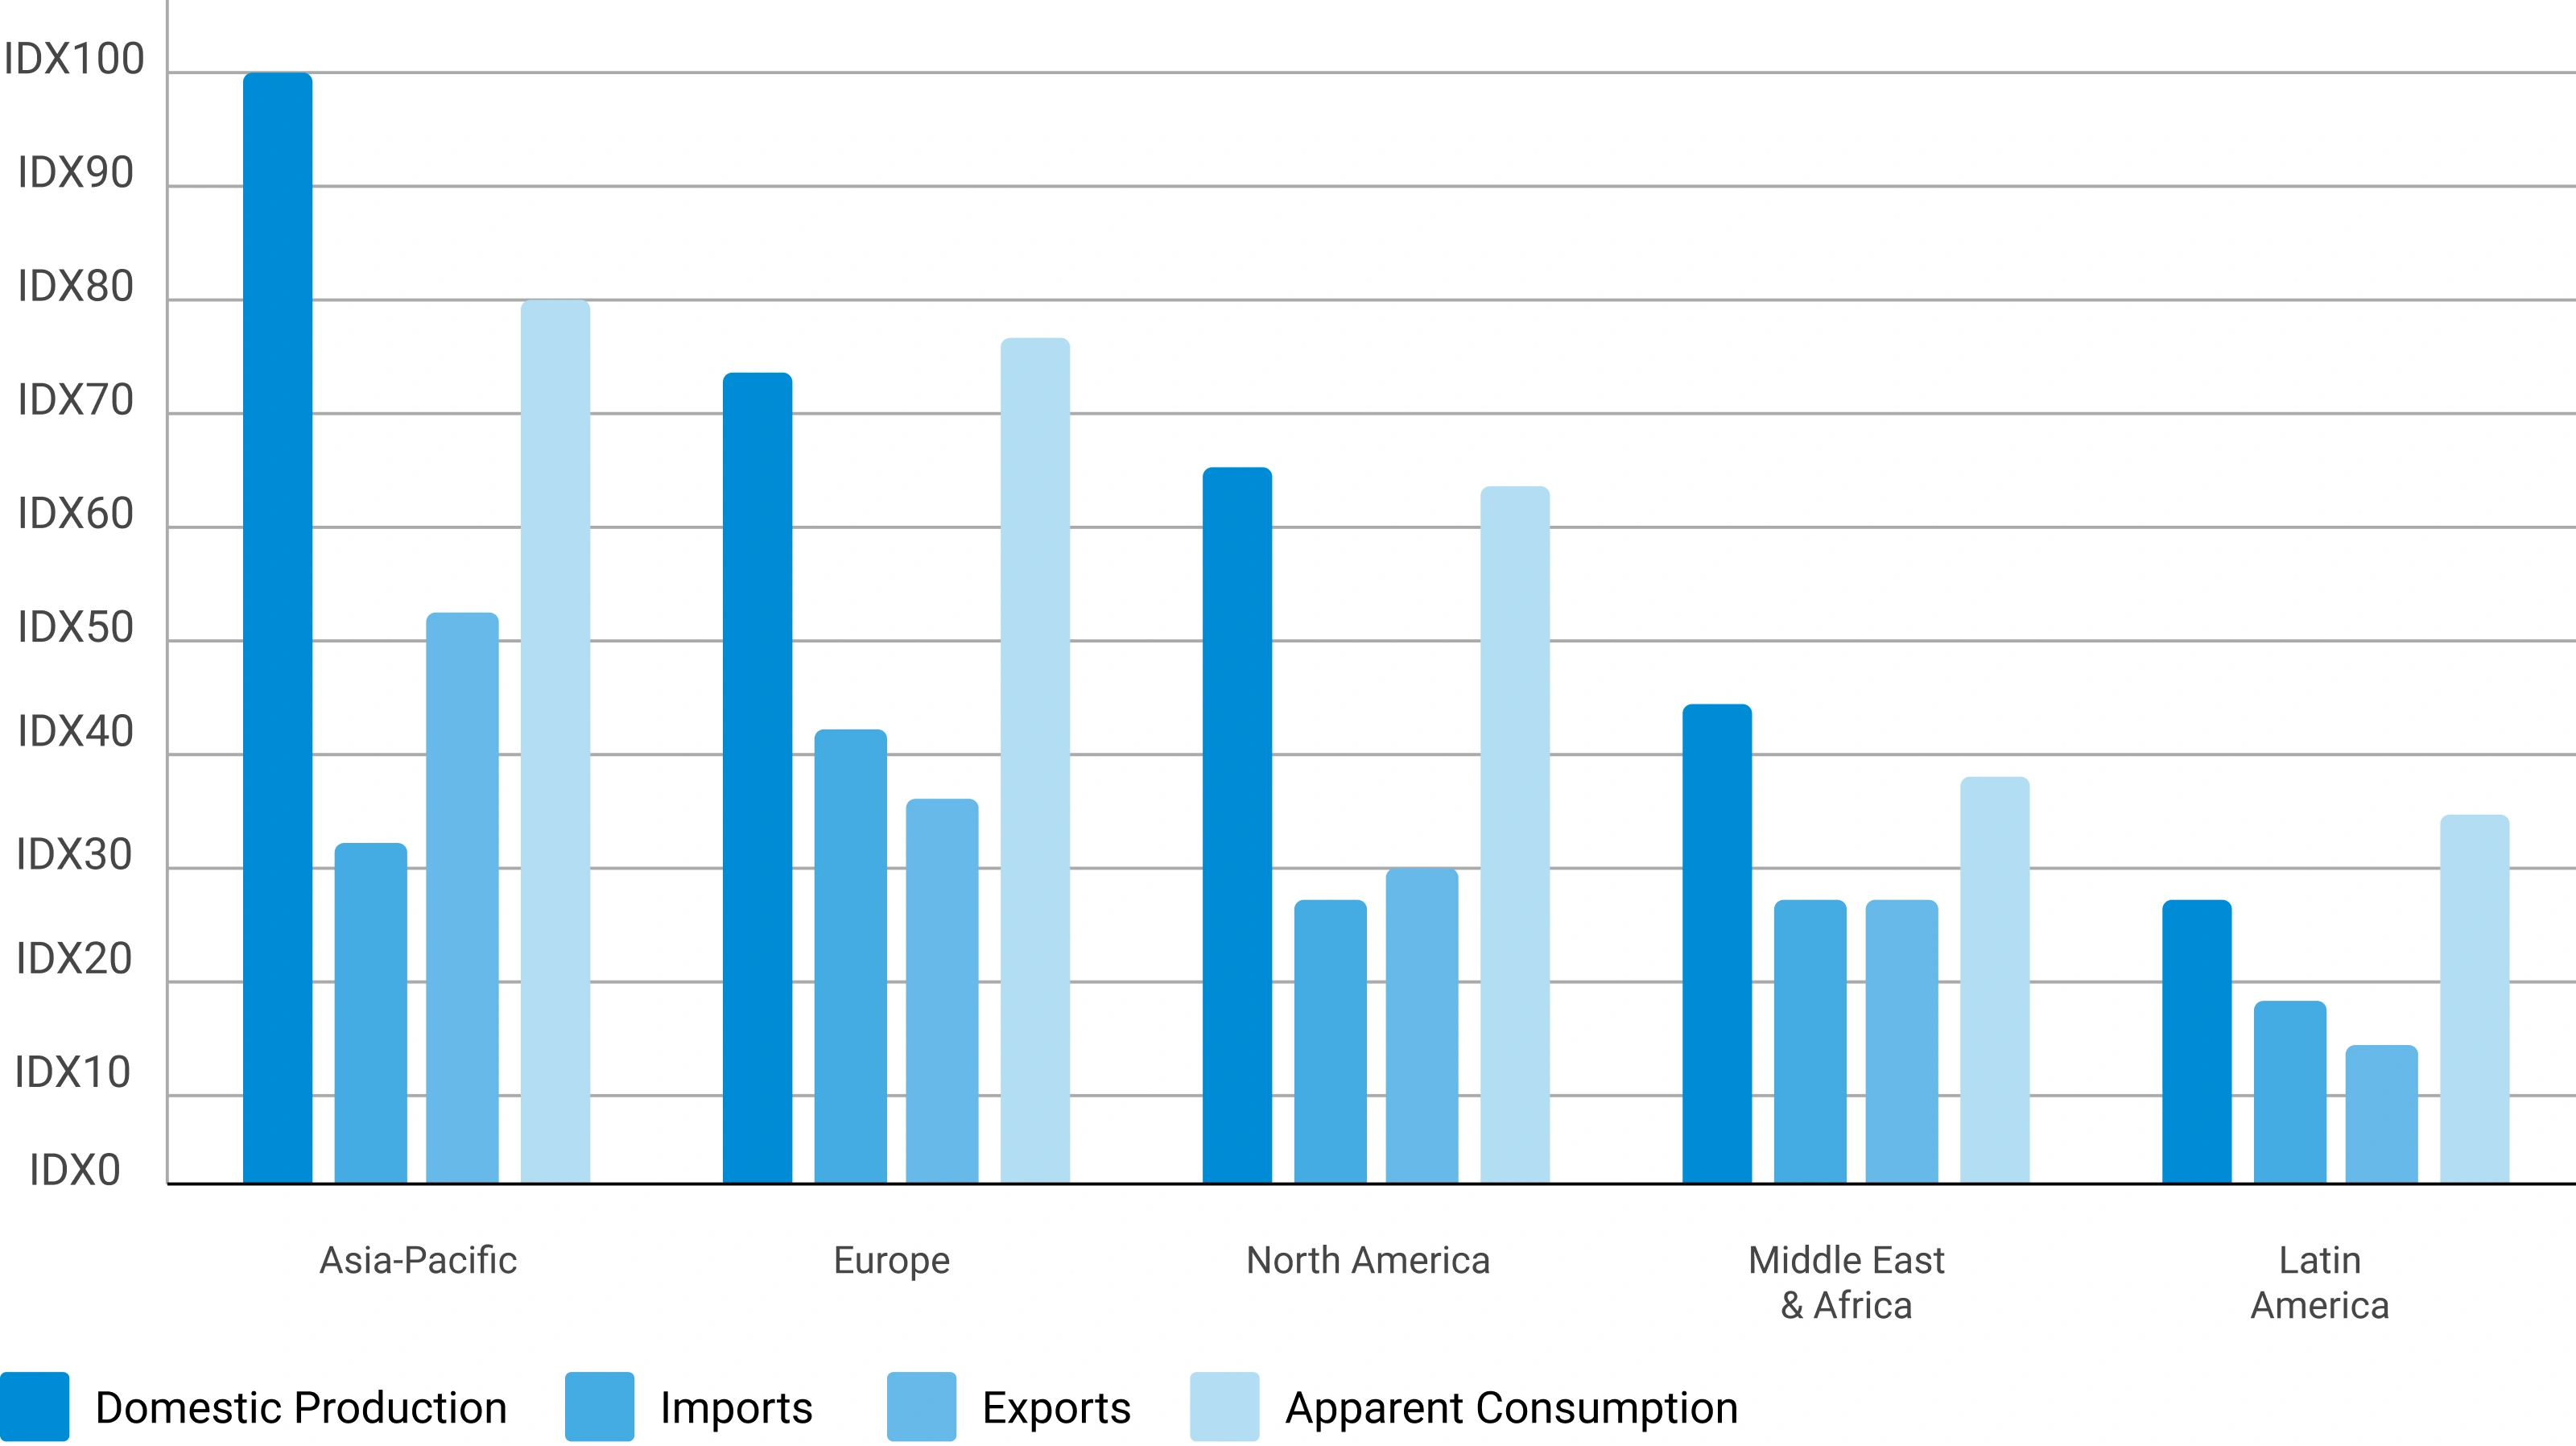
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency
Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.
Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.
Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.
Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
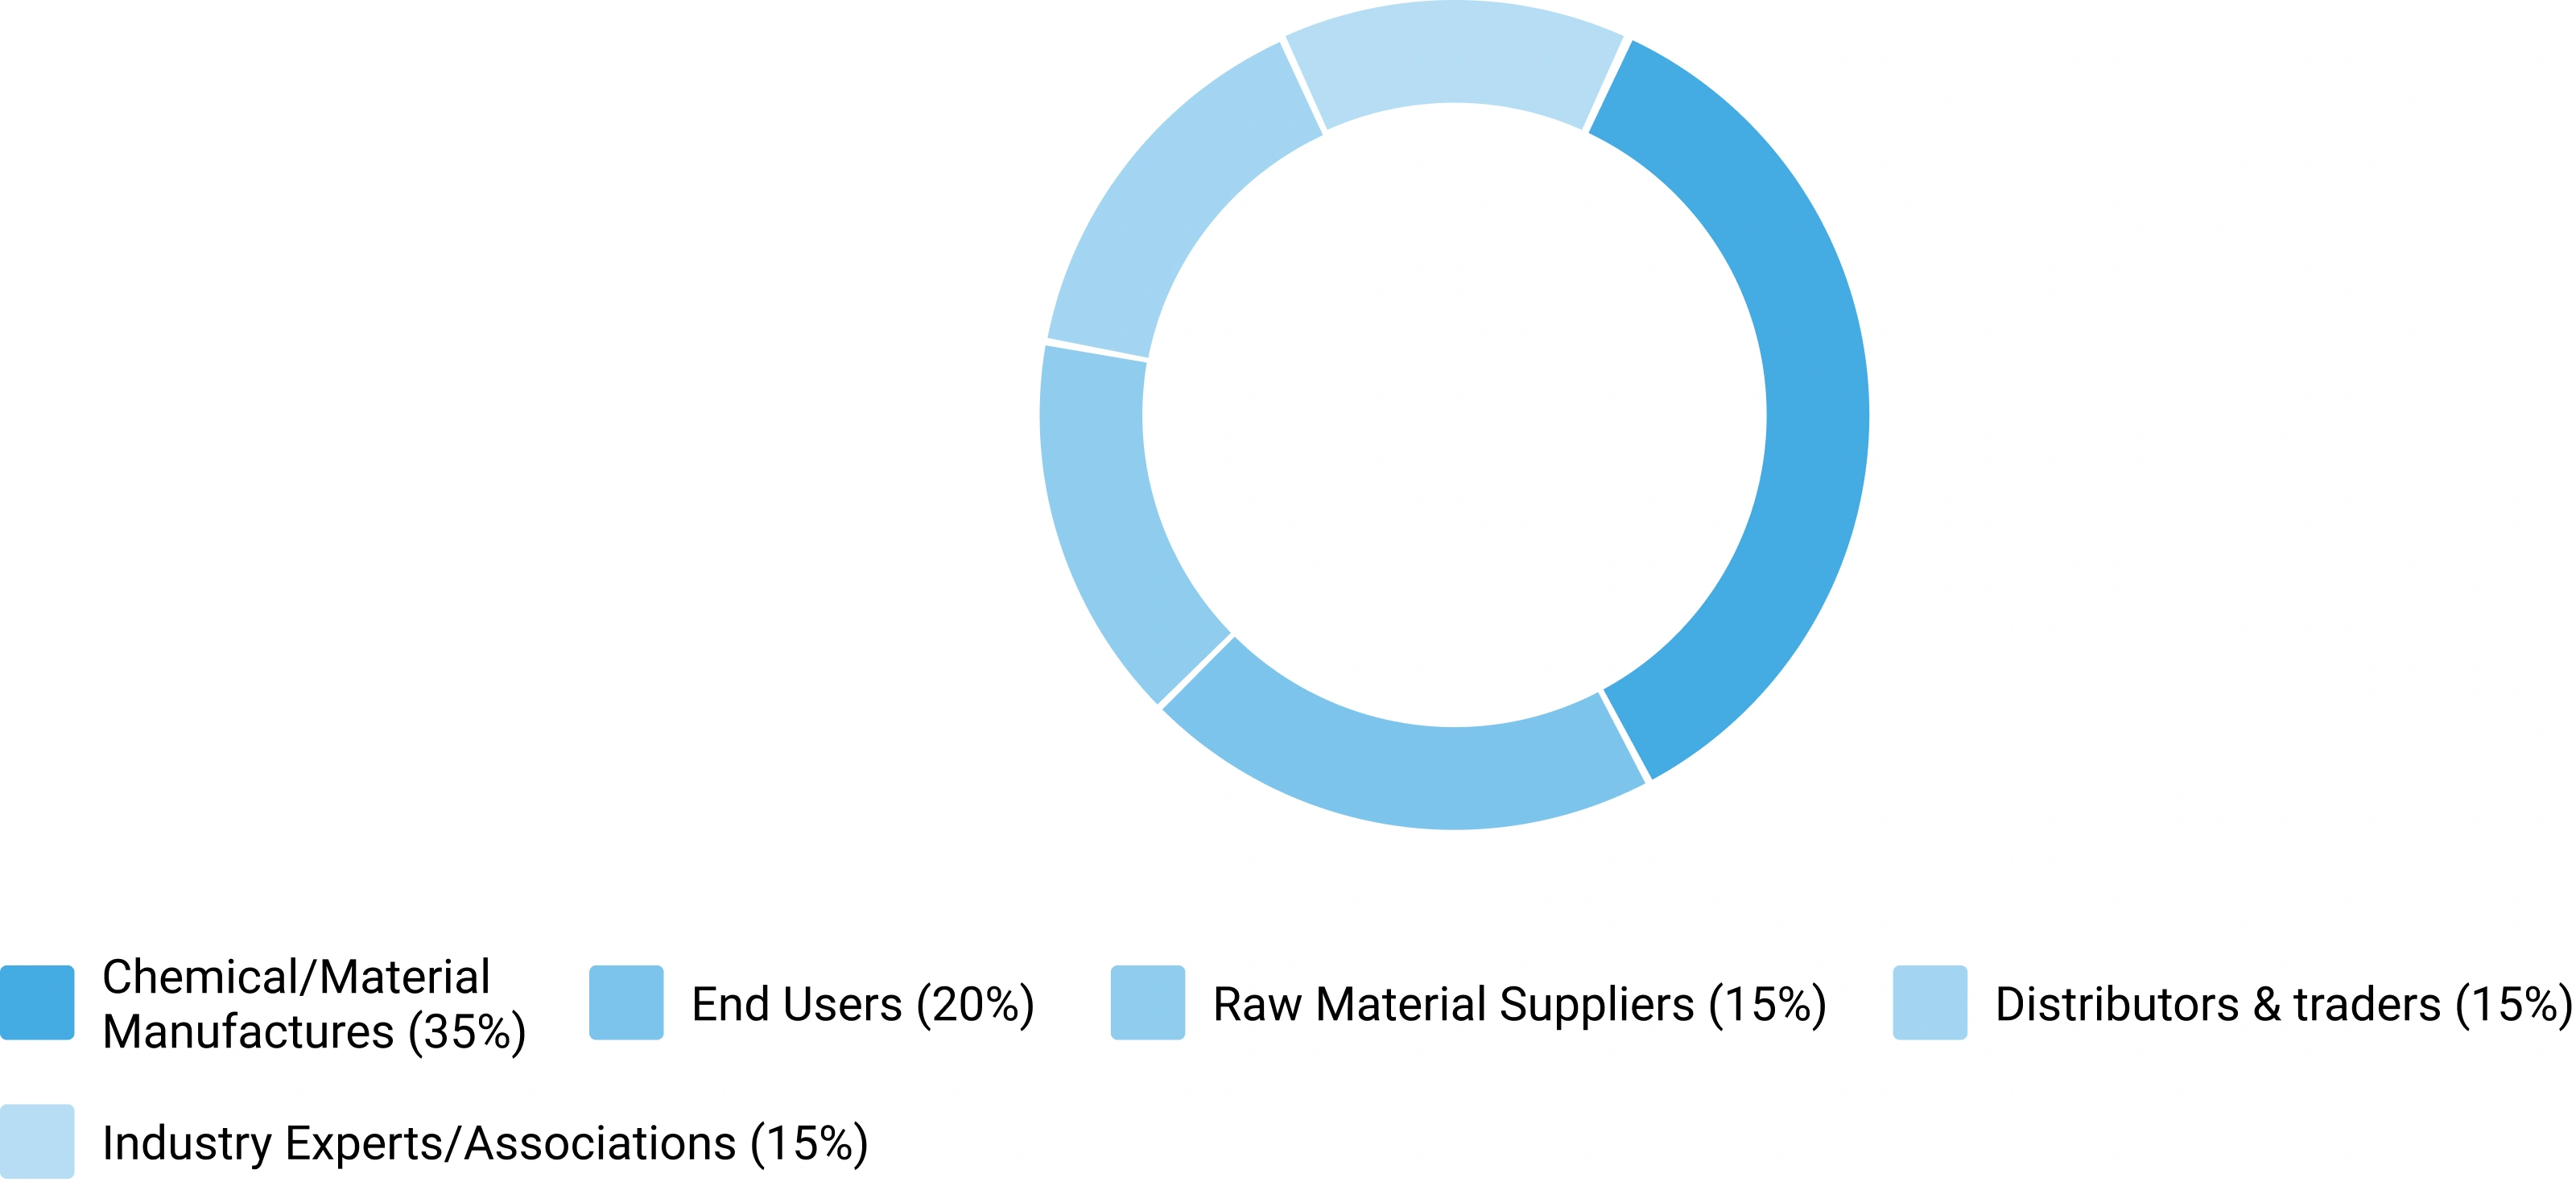
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)
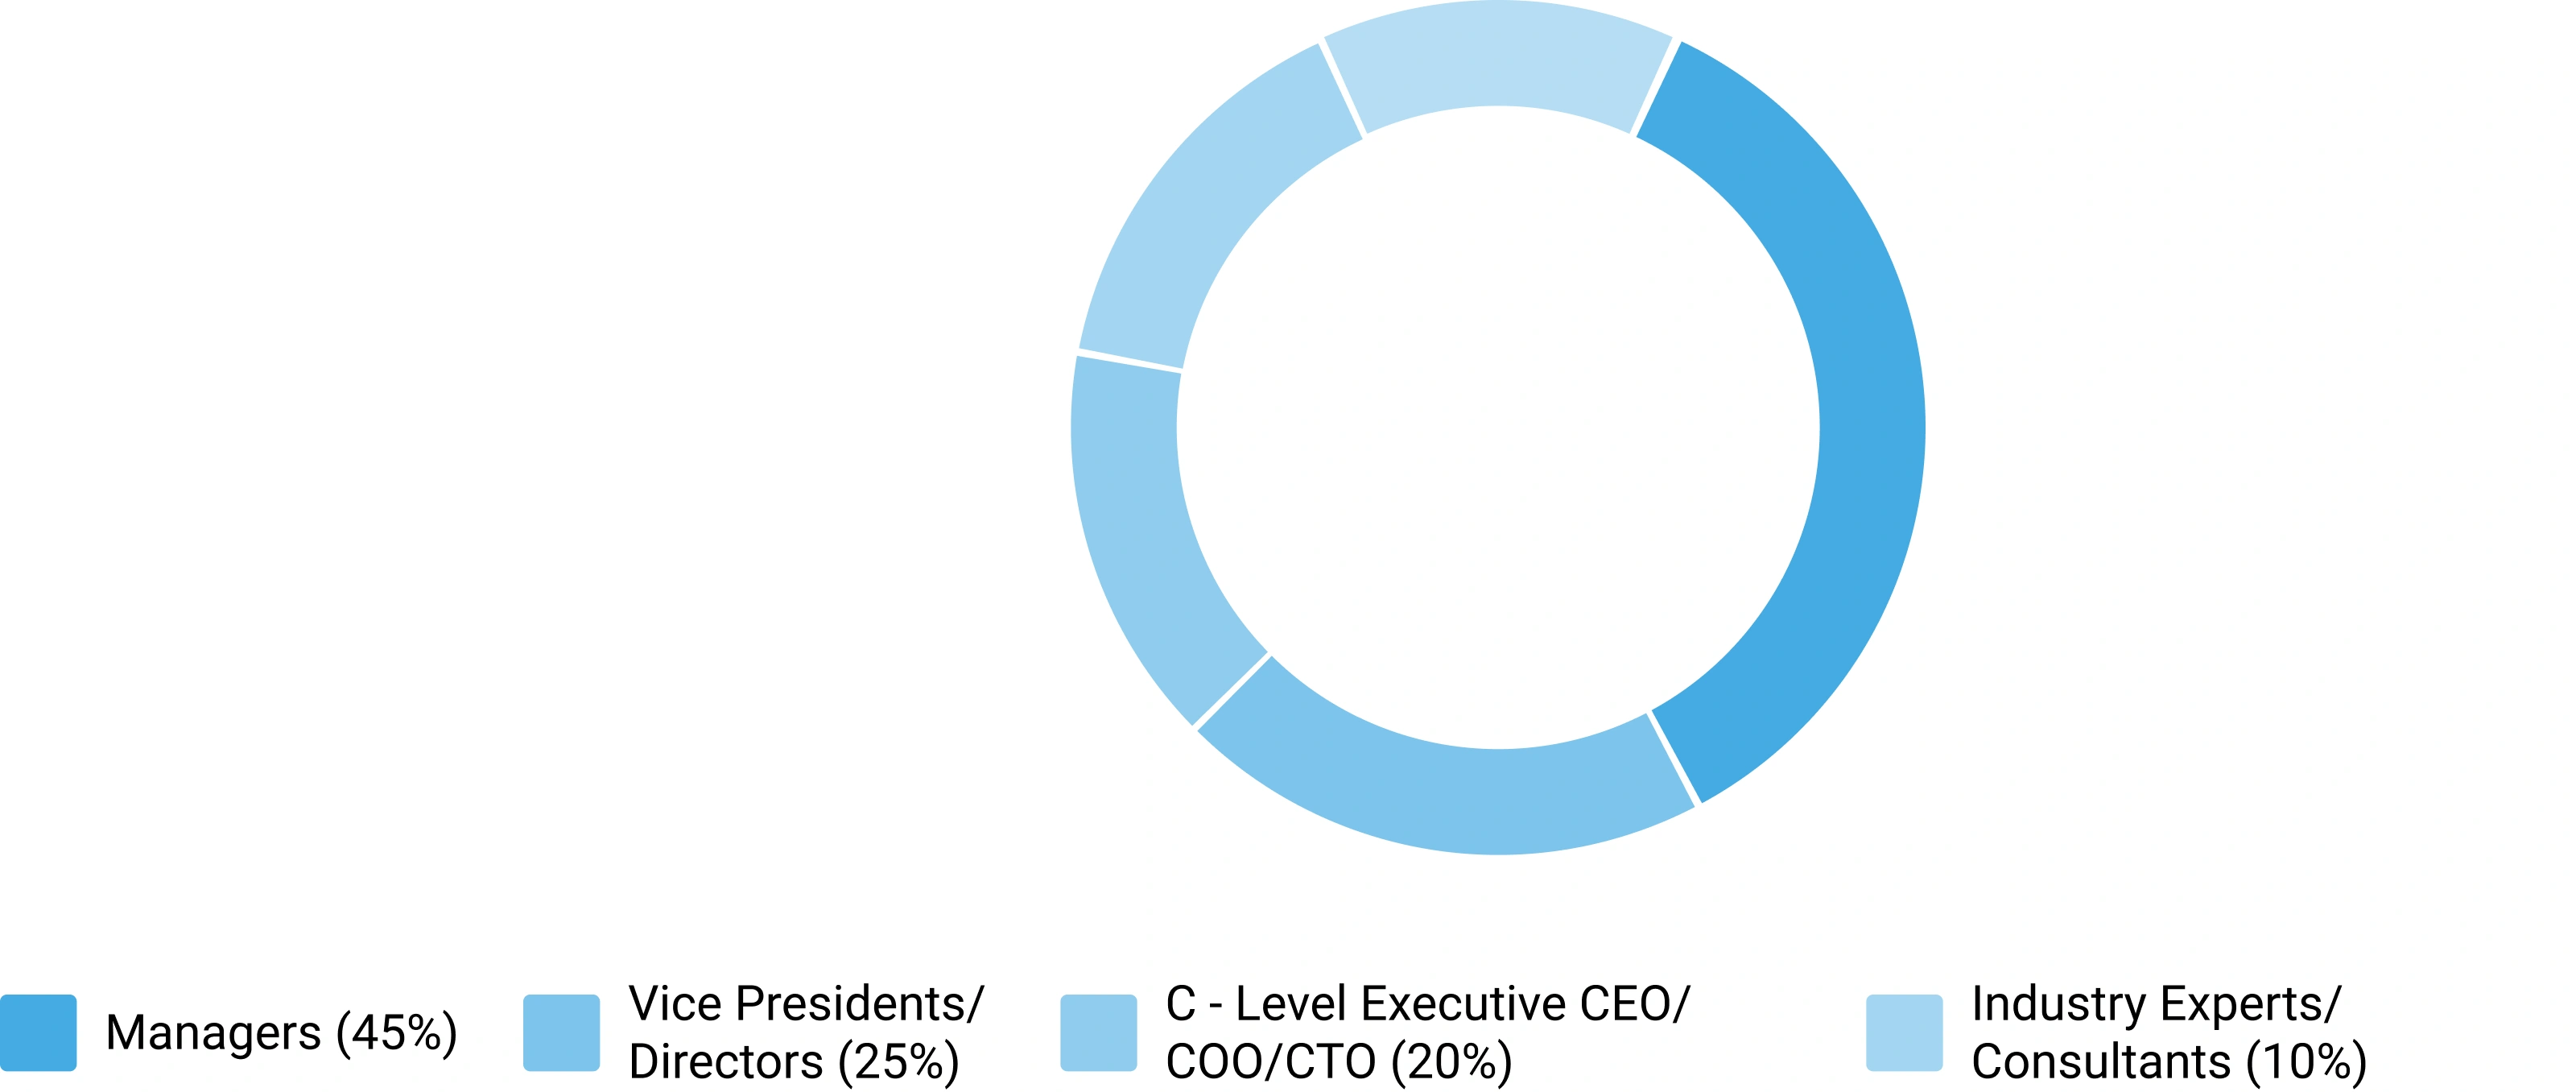
Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)
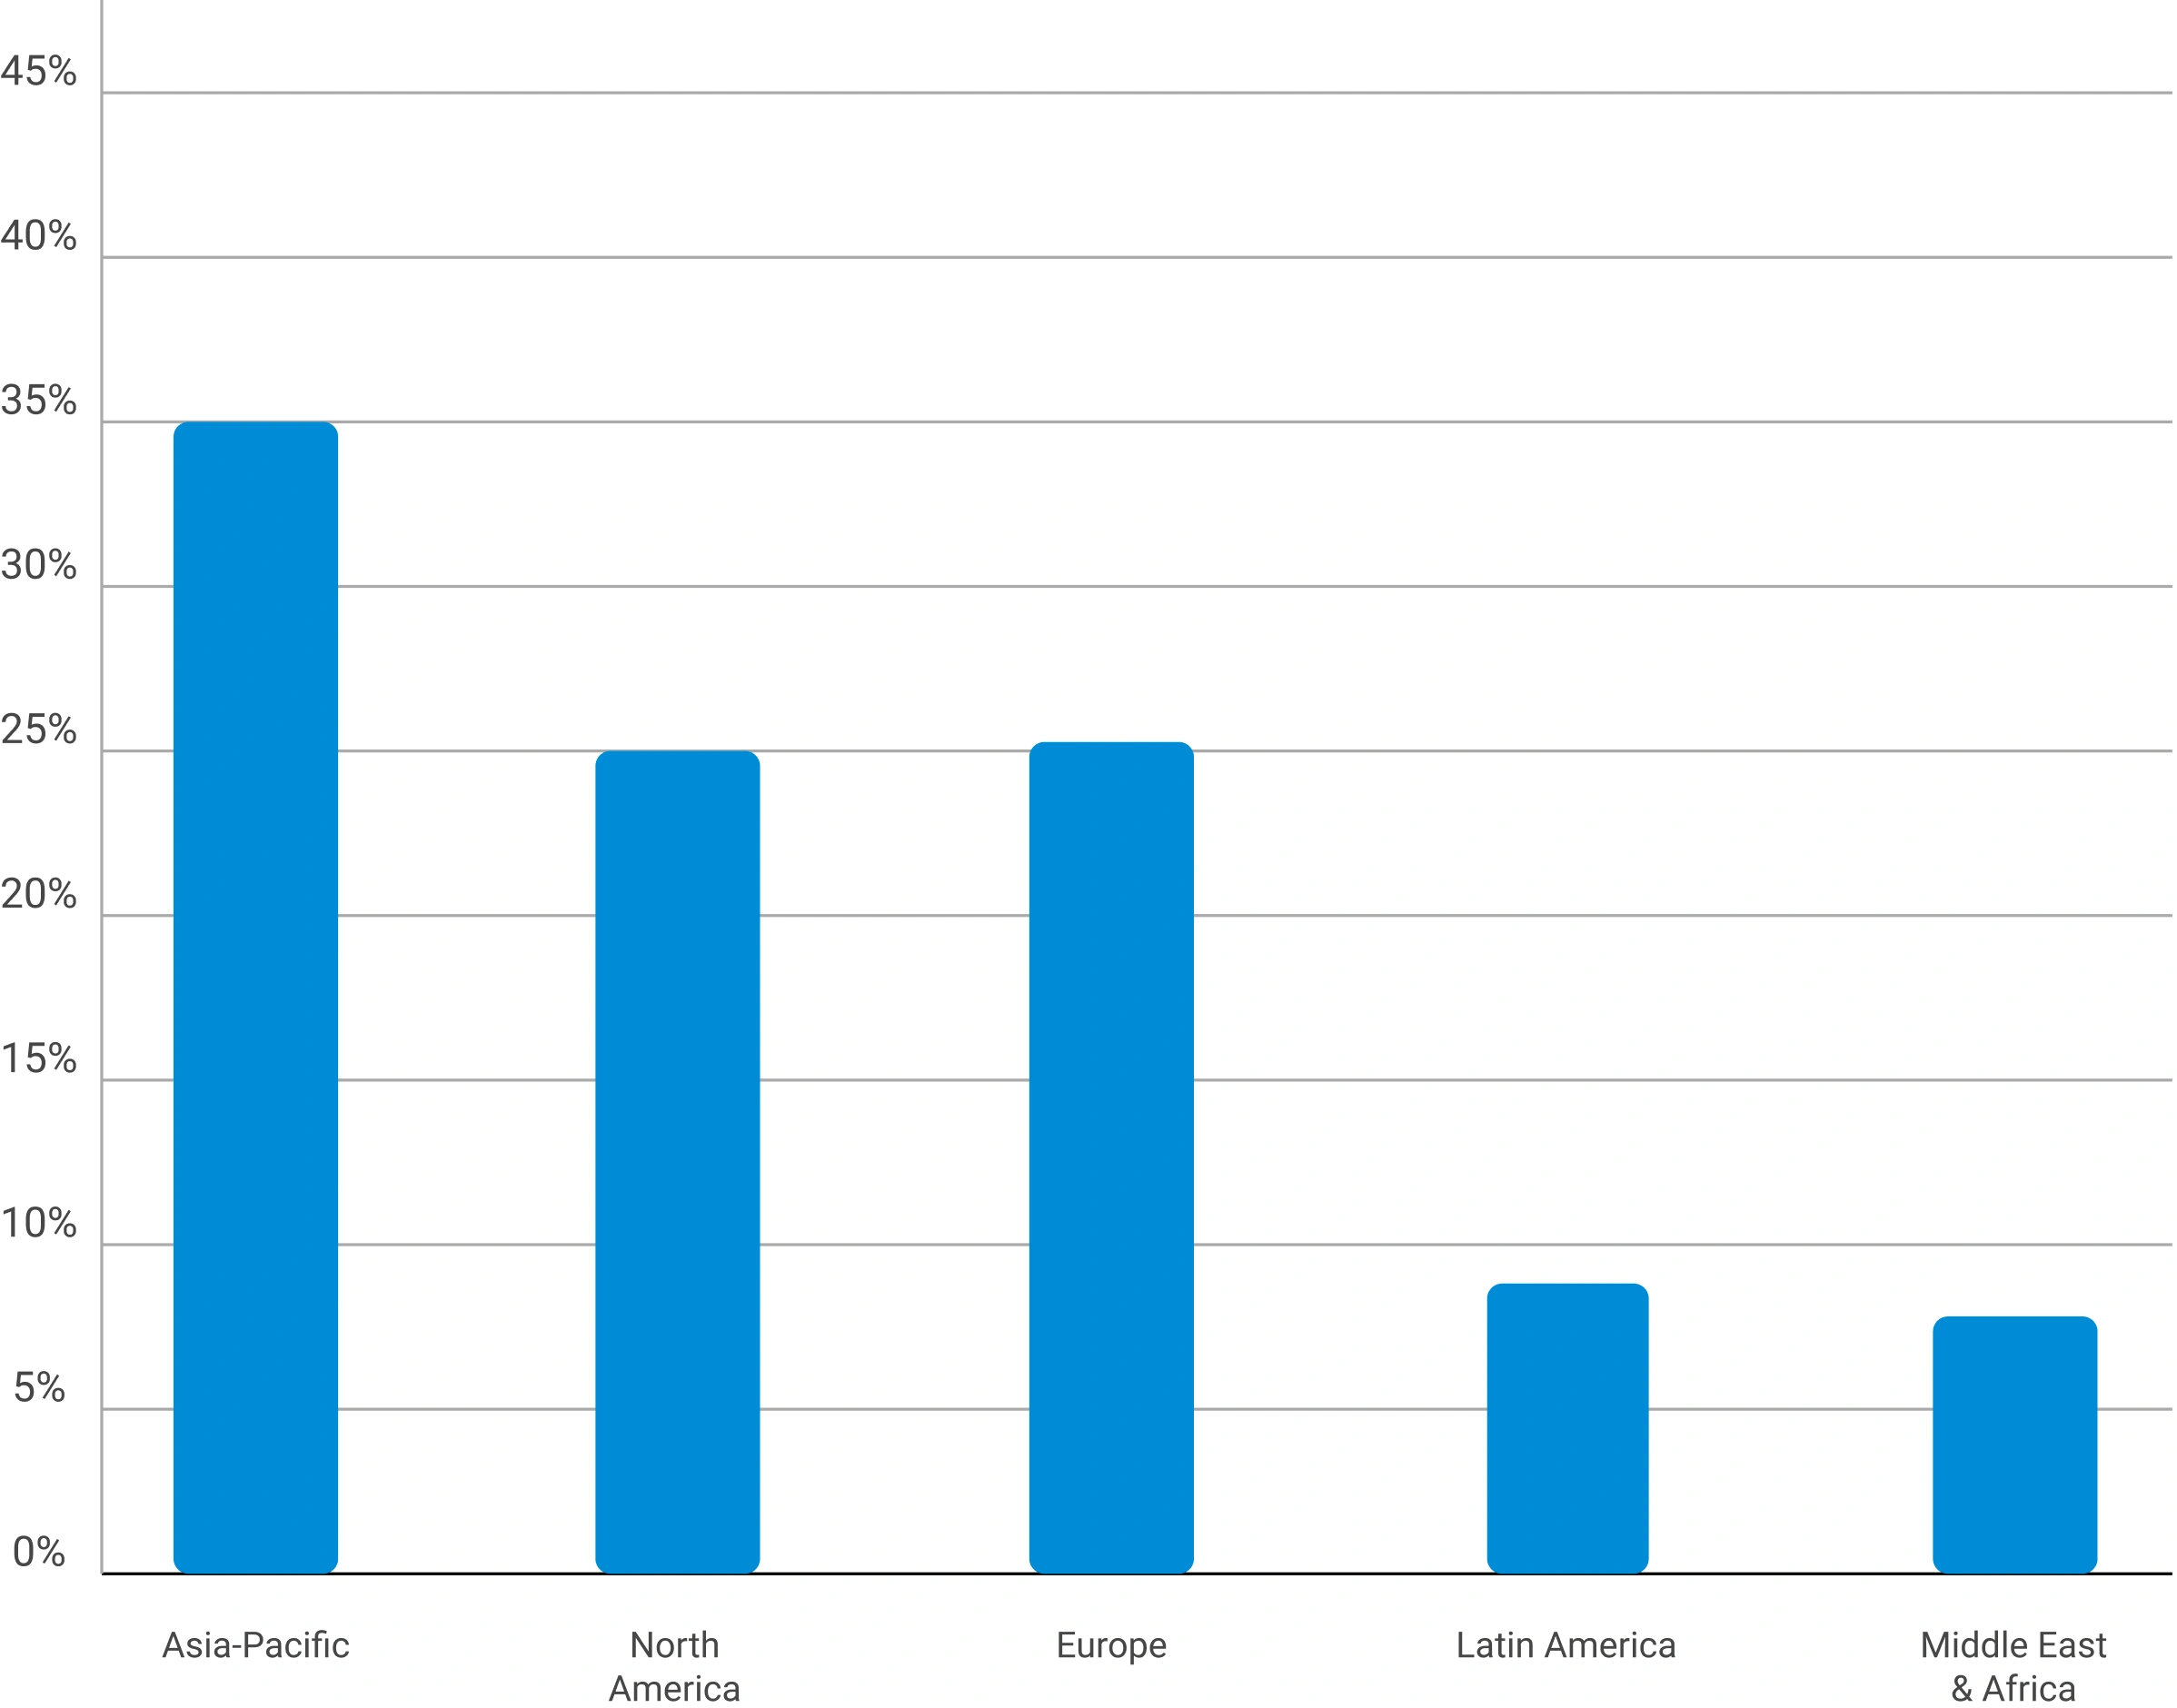
Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)
Phase 6 — Data Triangulation and Market Validation
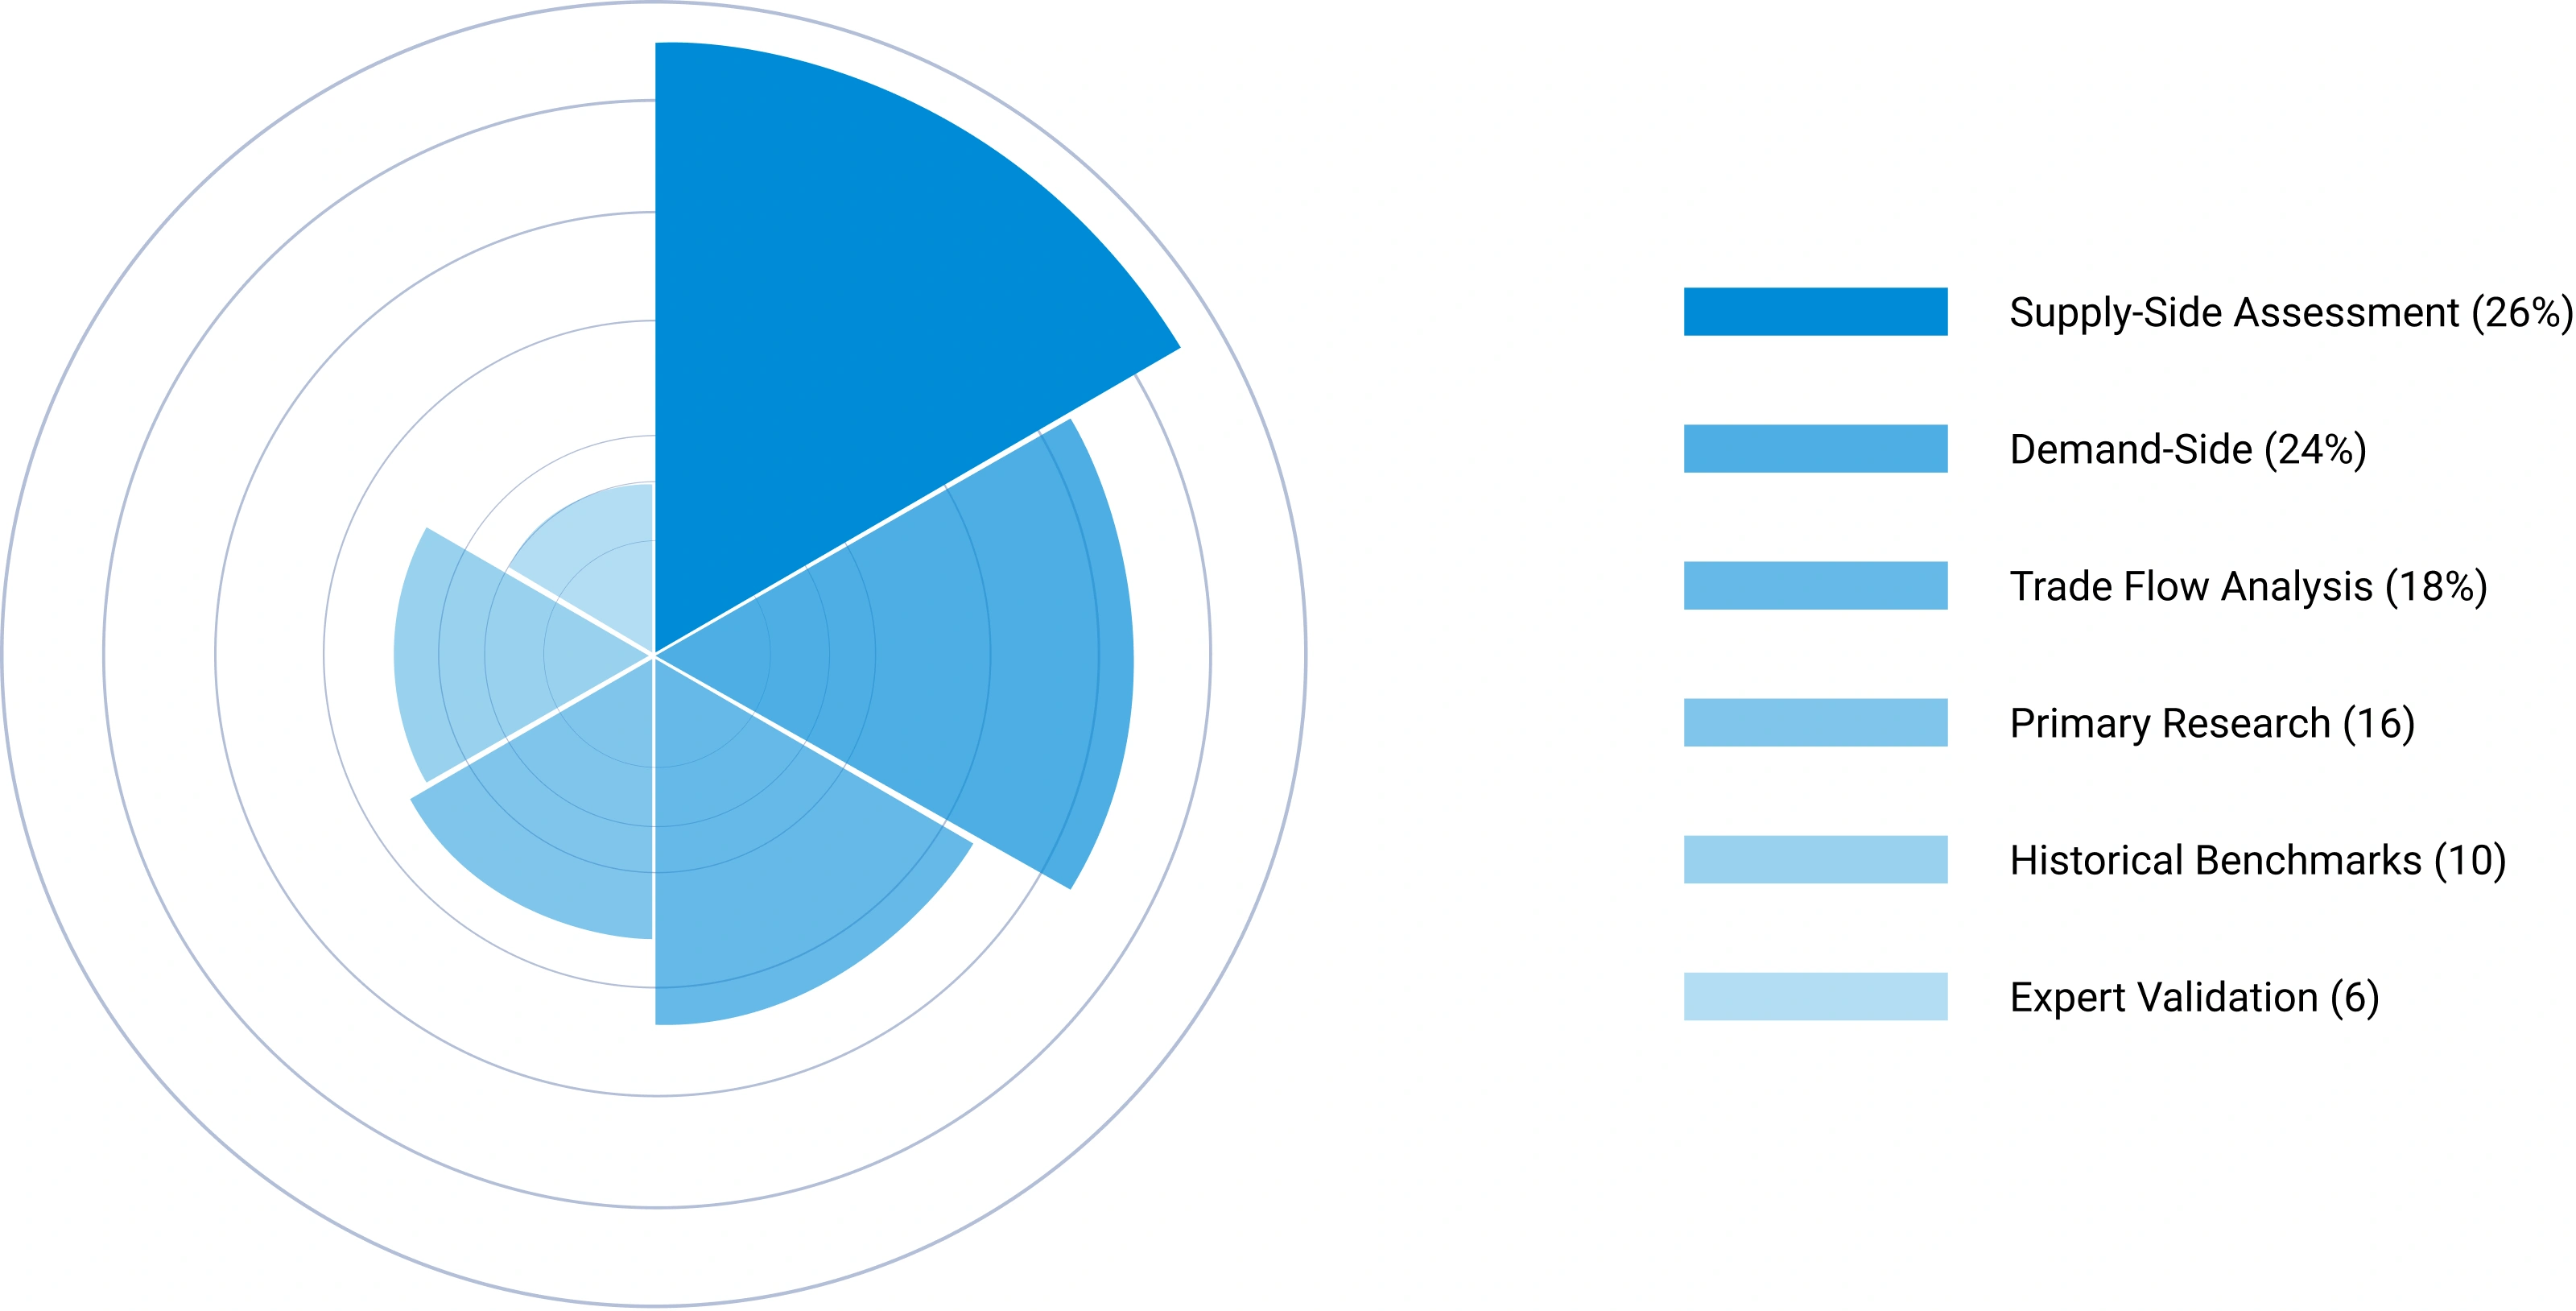
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate
Phase 7 — Forecast Modeling: Projecting Future Market Evolution
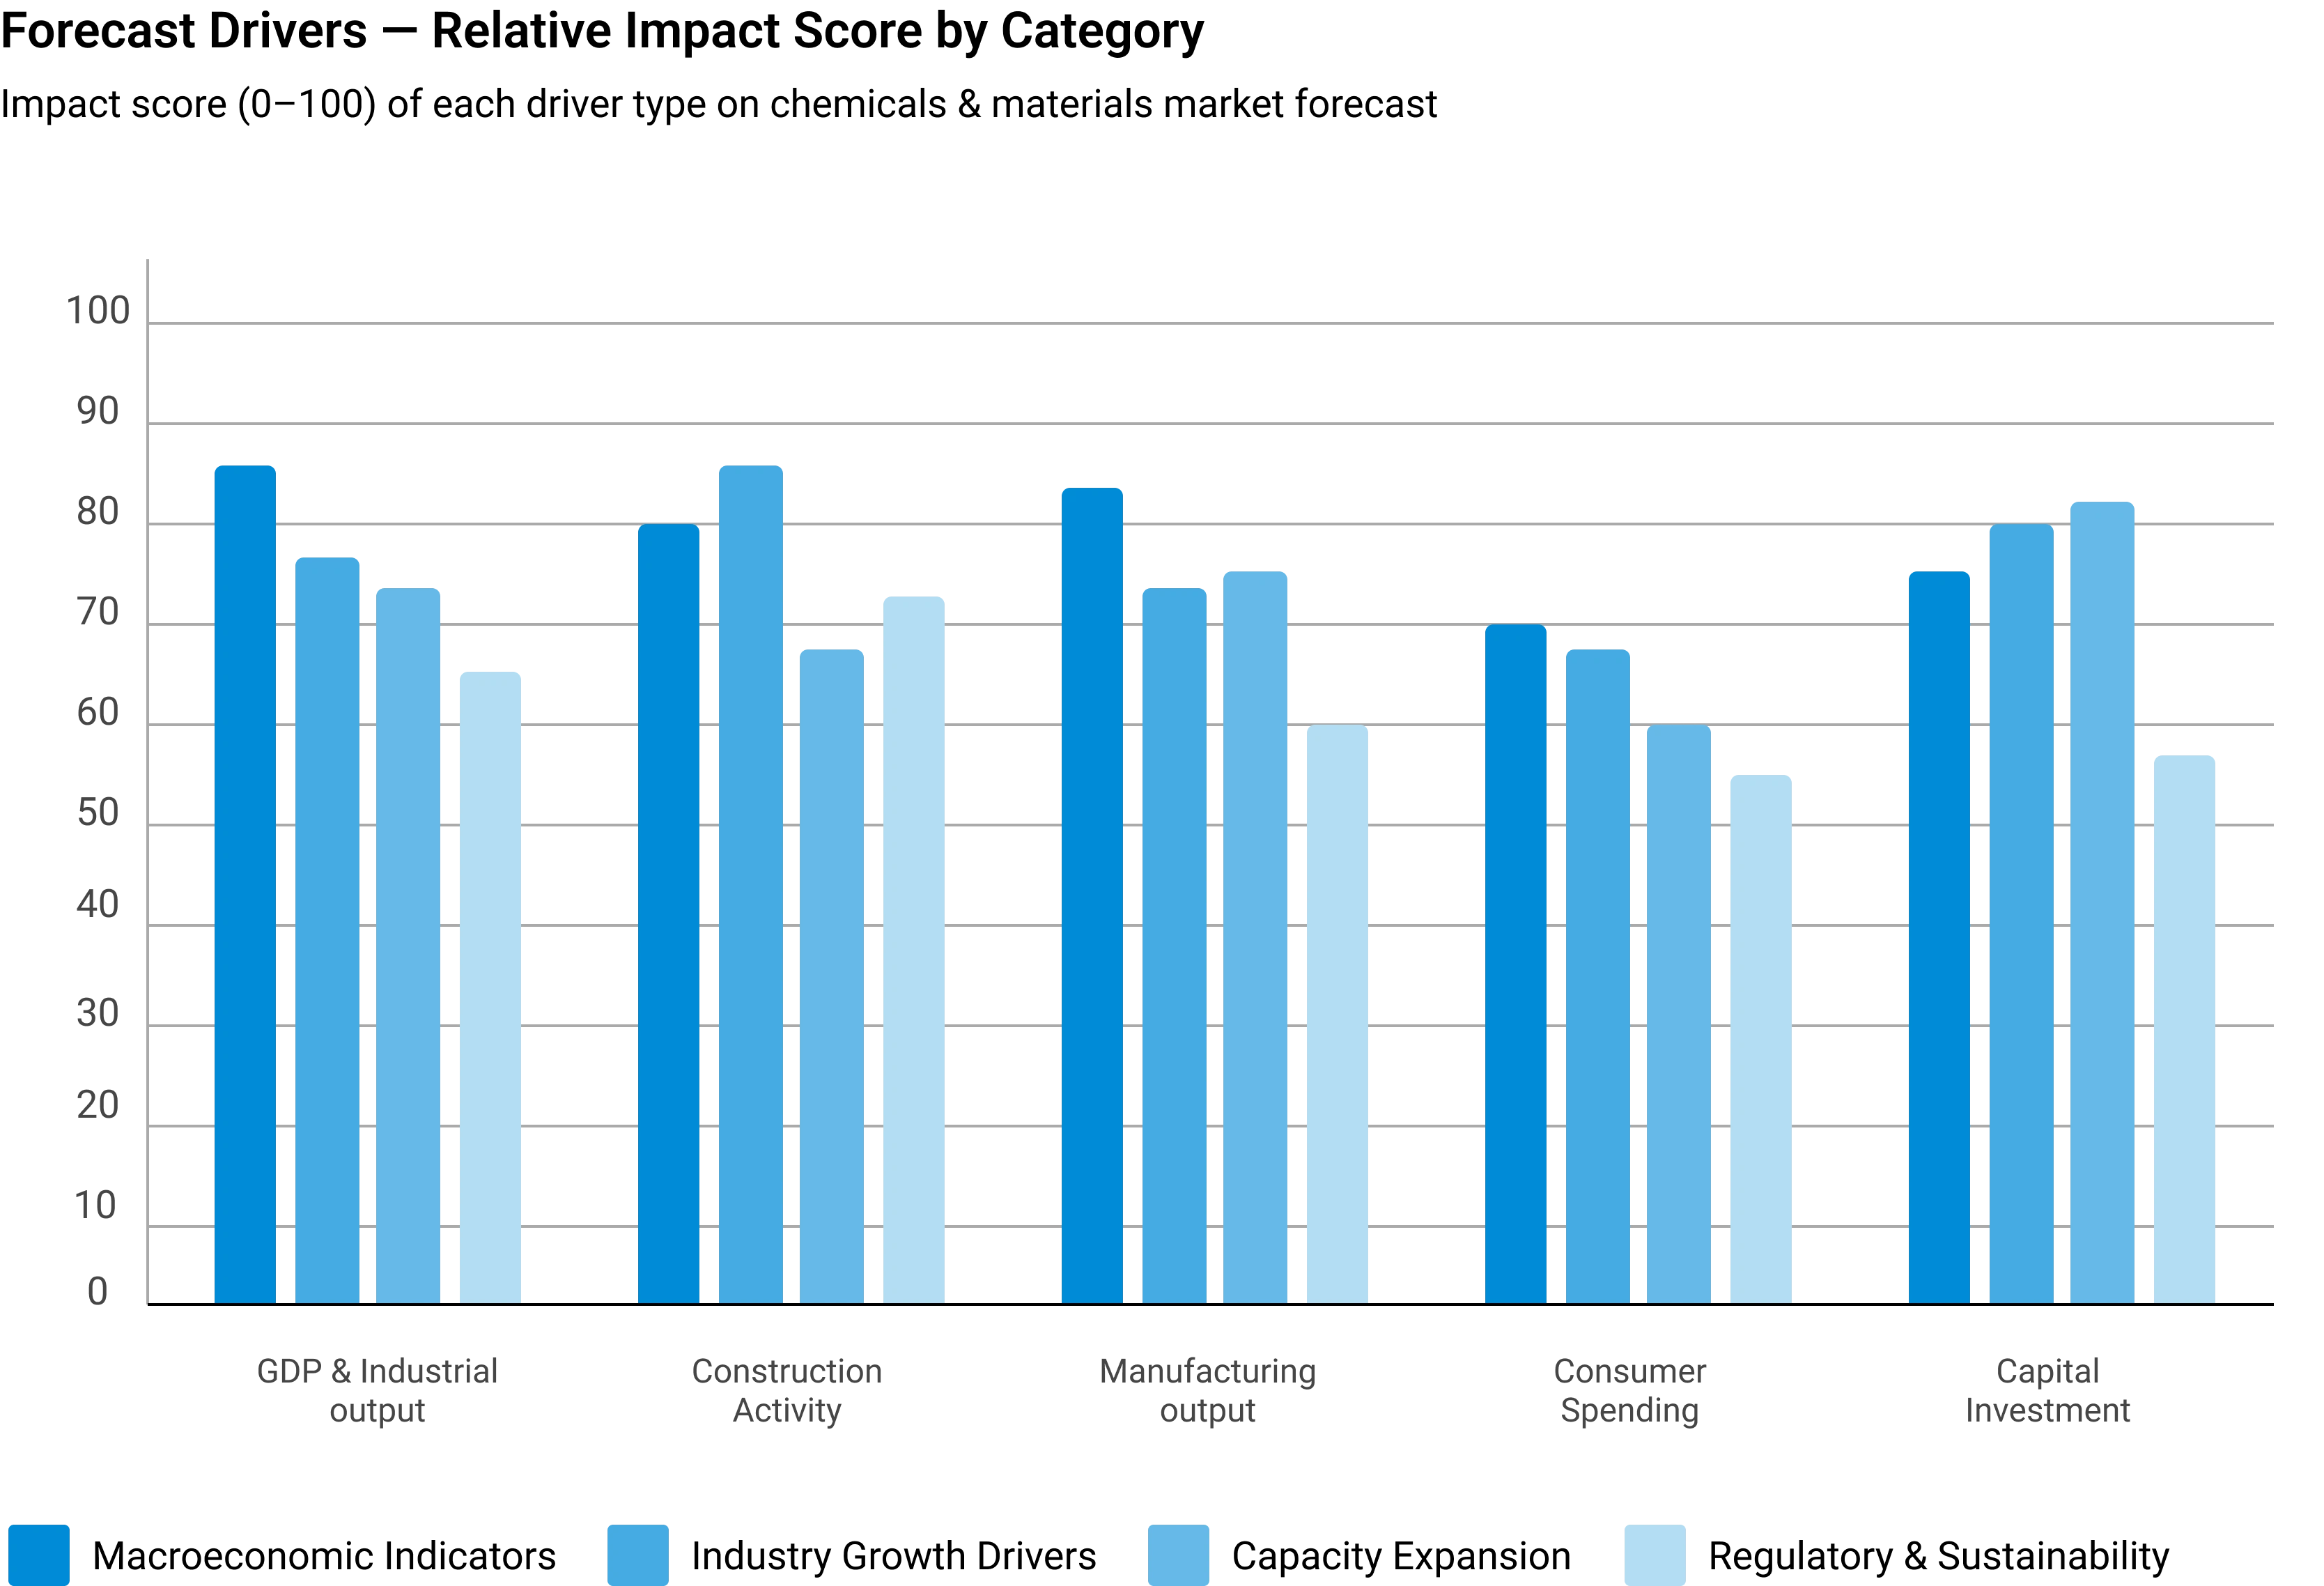
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
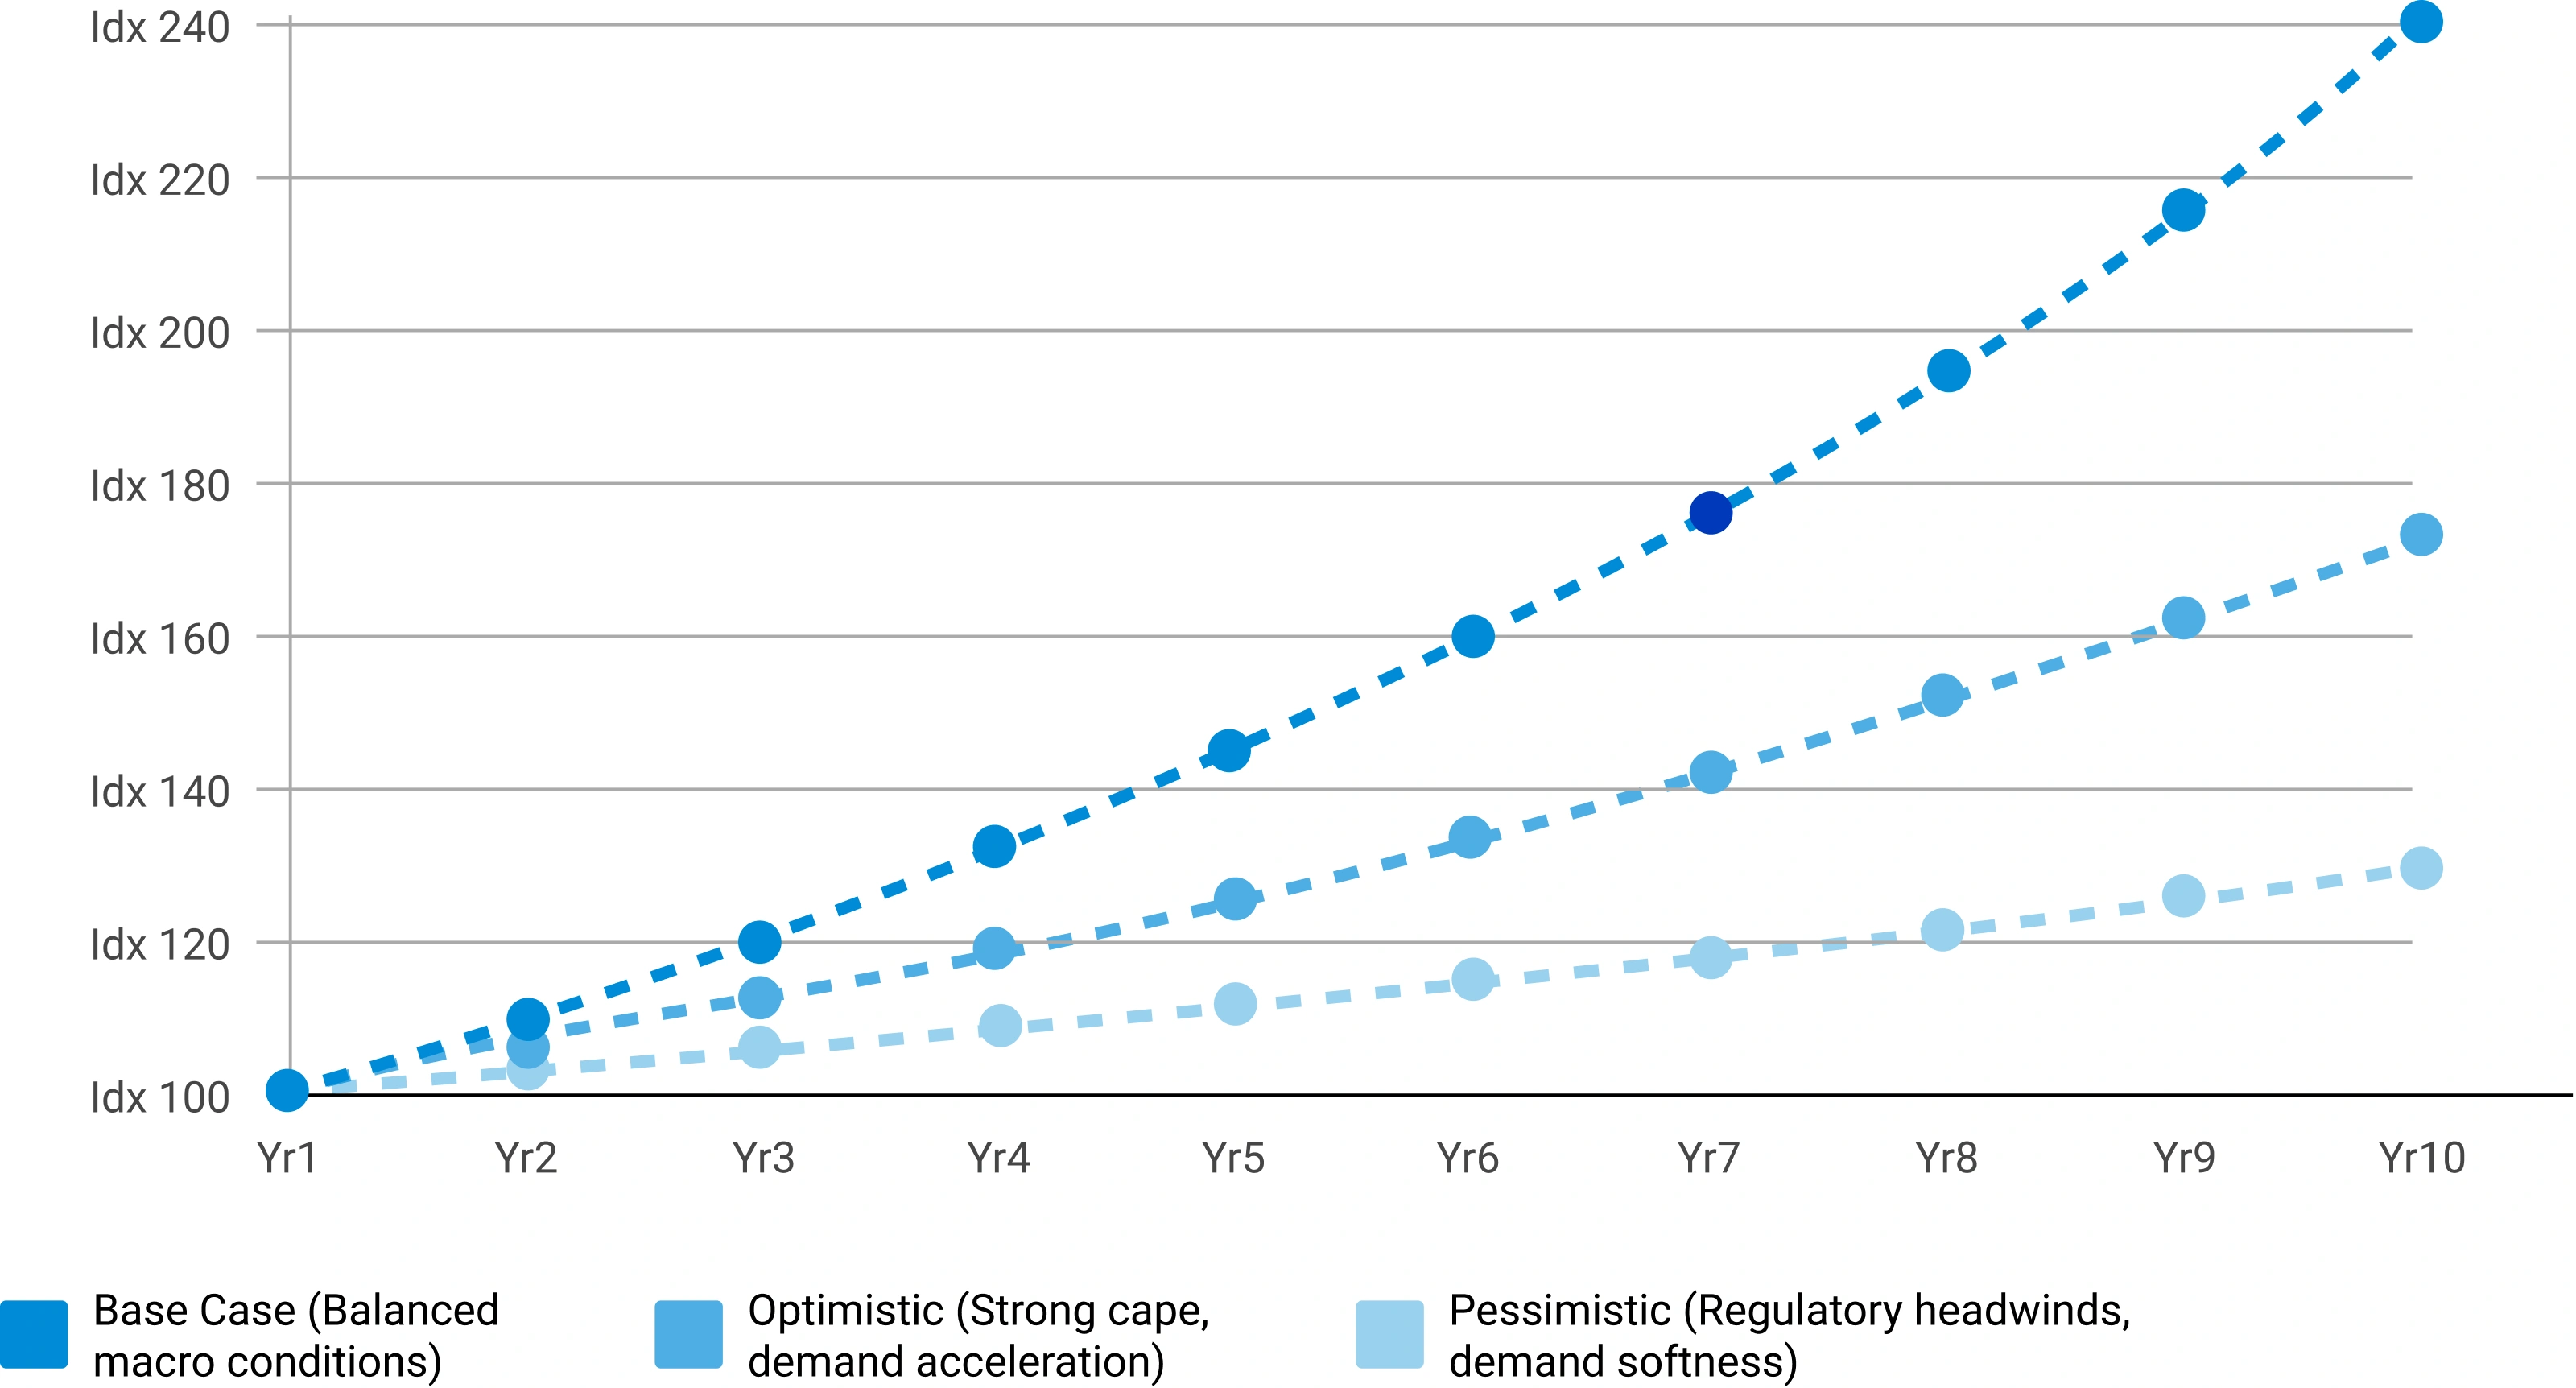
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon
Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast
Comments
Share your thoughts, ask a question, or provide feedback about this report.