
Microspheres Market Size Analysis Report 2035
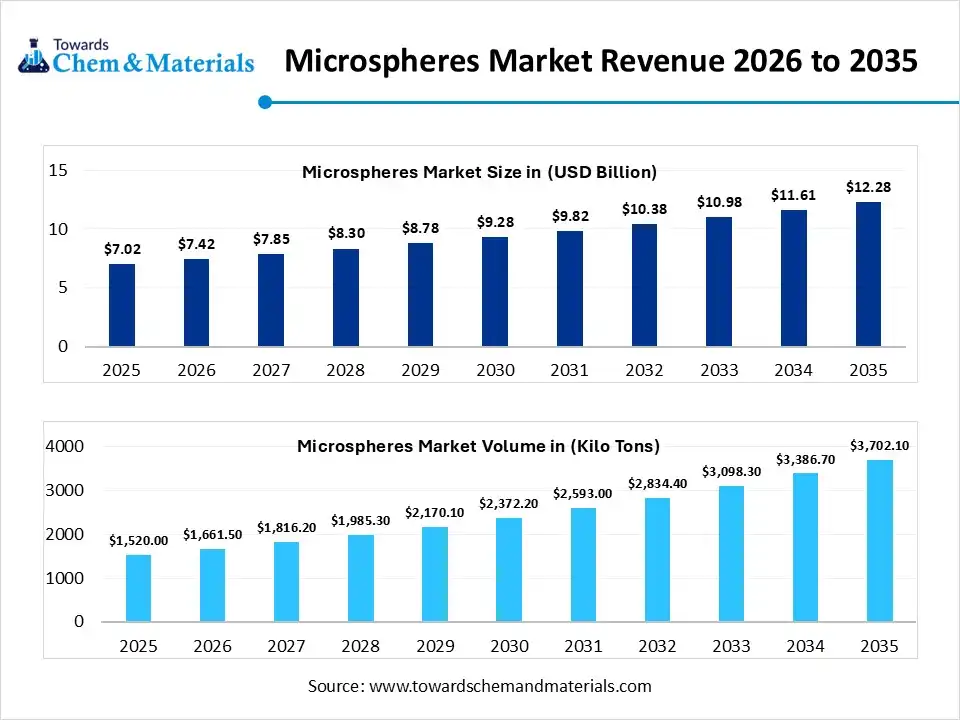
The global microspheres market size was estimated at USD 7.02 billion in 2025 and is expected to increase from USD 7.42 billion in 2026 to USD 12.28 billion by 2035, growing at a CAGR of 5.75% from 2026 to 2035. In terms of volume, the market is projected to grow from 1520 kilo tons in 2025 to 3702.1 kilo tons by 2035. growing at a CAGR of 9.31% from 2026 to 2035. North America dominated the microspheres market with the largest volume share of 42% in 2025. The market is driven by a sustainability focus, innovation in healthcare, the adoption of automation and rising industrial demand.
Market Highlights
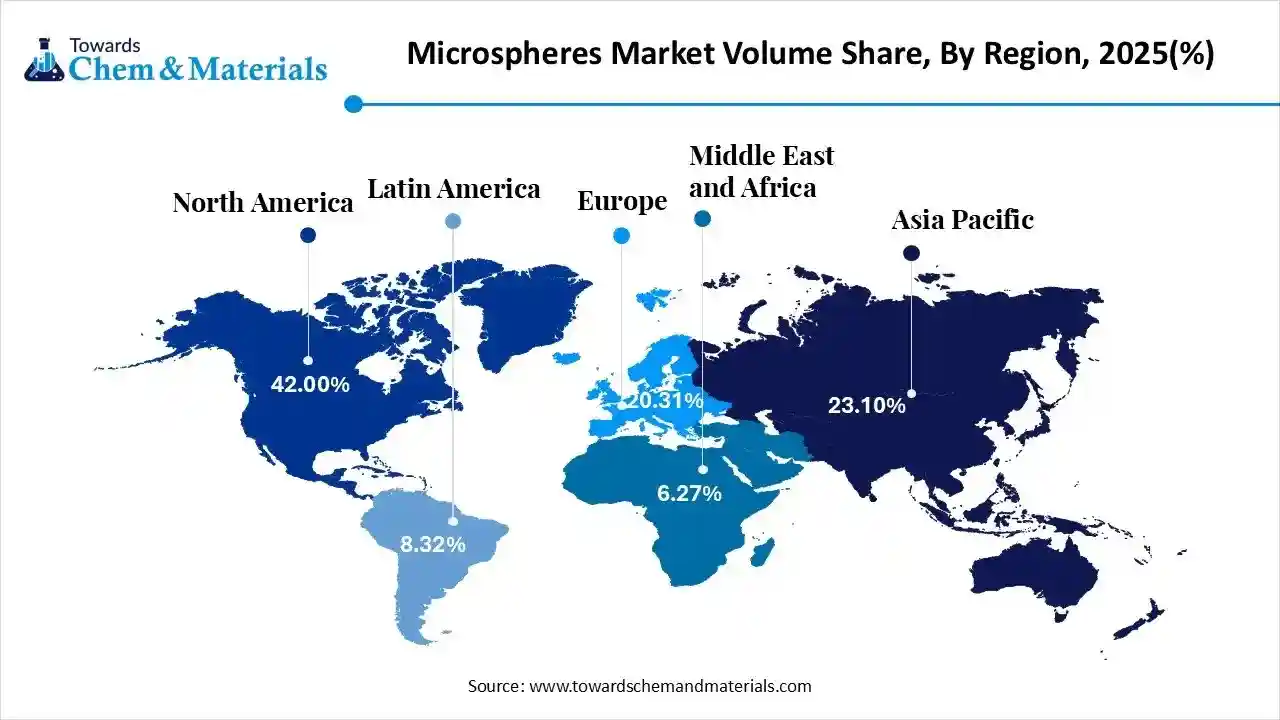
- The North America dominated the microspheres market with the largest volume share of 60% in 2025.
- The microspheres market in Asia Pacific is expected to grow at a substantial CAGR of 11.69% from 2026 to 2035.
- The Europe microspheres market segment accounted for the major volume share of 20.31% in 2025.
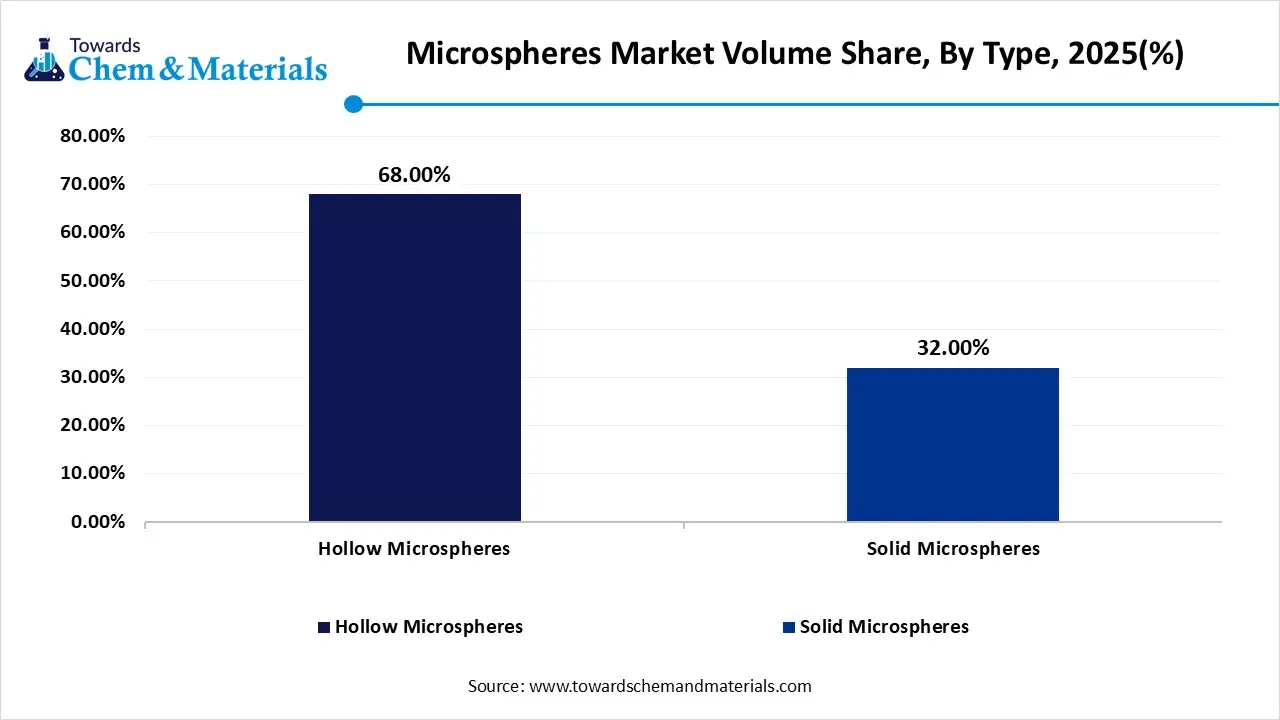
- By type, the hollow microspheres segment dominated the market and accounted for the largest volume share of 68.00% in 2025.
- By type, the solid microspheres segment is expected to grow at the fastest CAGR of 11.50% from 2026 to 2035 in terms of volume.
- By material, the glass segment led the market with the largest revenue volume share of 41% in 2025.
- By application, the construction composites segment dominated the market and accounted for the largest volume share of 29% in 2025.
Market Overview
The microspheres market is driven by innovation in material science, sustainability requirements, and industrial applications, especially in the medical and biotechnology sectors. The growth is driven by government mandates for weight reduction to reduce carbon footprint and improve fuel efficiency. Additionally, the AI integration supports novel materials formation and accelerates R&D.
The industry shift towards improvement of functional efficiency and energy conservation, fostering the demand for microspheres in construction, automotive, healthcare, aerospace, biotechnology, personal care and cosmetics that strengthening the market and driving expansion.
Microspheres Market Trends
- Emerging Shift to Sustainability: The rising focus on bio-based and biodegradable microspheres aligns with stringent regulatory pressure and industrial application especially for cosmetics, shaping the trend.
- Healthcare Expansion: The microspheres act as a crucial material for targeted drug delivery, tissue engineering and diagnostics, driving innovation in personalized medicine, which is accelerating expansion.
- Innovation in Hydrogen Storage: The research focuses on specialized hollow glass microspheres with safety, scalability and energy density for hydrogen storage and electrode materials for energy applications.
Report Scope
| Report Attribute | Details |
| Market Size and Volume in 2026 | USD 7.42 Billion / 1661.5 Kilo Tons |
| Revenue Forecast in 2035 | USD 12.28 Billion / 3702.1 Kilo Tons |
| Growth Rate | CAGR 5.75% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Units Considered | Value (Billion / Million), Volume (Kilo Tons) |
| Dominant Region | North America |
| Segment Covered | By Type, By Material, By Application, By Region |
| Key companies profiled | 3M Company, Potters Industries LLC, Nouryon (Expancel), Matsumoto Yushi-Seiyaku Co., Ltd, Trelleborg AB, Chase Corporation, Luminex Corporation, AkzoNobel N.V., Cospheric LLC, Sigmund Lindner GmbH, Bangs Laboratories, Merck KGaA, Thermo Fisher Scientific, Sekisui Chemical, Mo-Sci Corporation |
Key Technological Shifts and AI in the Microspheres Market
The microspheres market is shifting towards autonomous, self-optimizing systems by integration in microfluidic to ensure uniform particle size, and Generative Adversarial Networks propose novel chemical structures for specialty microspheres. The advancement in wearing sensors for medical and healthcare fuels the market with operational efficiency and optimization. The emerging smart microspheres, including closed-loop systems and hybrid systems pushing the market towards the adoption of technology.
Trade Analysis of the Microspheres Market: Import and Export Statistics
- China exported 5,752 shipments of microsphere.
- The United States exported 4,192 shipments of microsphere.
- Russia exported 1,855 shipments of microsphere.
- From June 2024 to May 2025, the world exported 7,816 shipments of microsphere.
Microspheres Market: Value Chain Analysis
- Feedstock Procurement:The initial stage involves the sourcing of bulk materials like ceramics, glass, fly ash, and polymers by maintaining cost-competitiveness and product quality from suppliers.
- Key Players: 3M Company, Potters Industries LLC, Chase Corporation and Nouryon.
- Manufacturing/Production: In this stage, raw materials are processed using solvent evaporation, spray drying and polymerization to form microspheres with key characteristics to meet strict quality and performance requirements.
- Key Players: Matsumoto Yushi-Seiyaku Co., Ltd., 3M, Trelleborg AB, Luminex Corporation and Momentive Performance Materials Inc.
- Distribution to End-Users: The microspheres are packaged and distributed to end-user industries with efficient delivery and logistics, with major applications like medical, construction composites, cosmetics, automotive, paints & coatings.
- Key Players: Nouryon, Cospheric LLC, 3M, Sigmund Lindner GmbH
Regulatory Framework: Microspheres Market
| Region | Regulations | Regulatory Focus |
| North America | Food and Drug Administration (FDA), Environmental Protection Agency (EPA) | The regulations for medical-grade microspheres require testing, validation with good manufacturing practices for efficiency and also focus on sustainable materials |
| Europe (EU) | European Chemical Agency (ECHA), EMA | The regulation added for various medical devices containing microspheres with safety and performance. |
| Asia Pacific | National Medical Products Administration (NMPA), PMDA | The standards focus on quality control, efficiency and a strong push for domestic manufacturing. |
Segmental Insights
Type Insights
Why the Hollow Microspheres Segment Dominates the Microspheres Market?
The hollow microspheres segment volume was valued at 1,033.6 kilo tons in 2025 and is projected to reach 2,406.3 kilo tons by 2035, expanding at a CAGR of 9.84% during the forecast period from 2025 to 2035. The hollow microspheres segment dominated the market with approximately 68% share in 2025, by enabling industries to reduce weight and improve thermal efficiency. Their hollow structure lowers material density while maintaining mechanical durability, driving innovation in transportation and the energy sector by creating ultra-light composites that extend EV range and boost aircraft fuel economy. Additionally, the encapsulated air offers superior thermal and acoustic insulation, making it vital in extreme environments. The industry is transitioning from specialized fillers to essential structural components, which define modern material performance.
The solid microspheres segment volume was valued at 486.4 kilo tons in 2025 and is projected to reach 1,295.7 kilo tons by 2035, expanding at a CAGR of 11.50% during the forecast period from 2025 to 2035.The solid microspheres segment is the fastest-growing in the market during the forecast period, which is crucial in precision medicine, biotechnology, and specialized electronics. The solid microspheres are valued for stability and functionalisation because they enable precisely engineered targeted drug delivery and diagnostics. Their highly predictable and uniform surface makes them vital for immunoassays and flow cytometry. Additionally, the rising adoption of semiconductor packaging and cosmetics for active ingredients is boosting the market, while the high purity and density support next-generation healthcare and micro-electronics.
Microspheres Market Volume and Share, By Type, 2025-2035
| By Type | Market Volume Share (%), 2025 | Market Volume (Kilo Tons)2025 | Market Volume (Kilo Tons)2035 | CAGR(%) 2026-2035 | Market Volume Share (%), 2035 |
| Hollow Microspheres | 68.00% | 1,033.6 | 2,406.3 | 9.84% | 65.00% |
| Solid Microspheres | 32.00% | 486.4 | 1,295.7 | 11.50% | 35.00% |
Material Insights
How did the Glass Segment hold the Largest Share in the Microspheres Market?
The glass segment held the largest revenue share of approximately 41% in the market in 2025. By combining mechanical strength with chemical neutrality. Their ability to withstand high pressures in processes like injection molding and deep-sea exploration without crumbling. Their structural integrity and low density make them ideal for lightweight automotive and aerospace applications, by replacing heavier fillers to improve fuel efficiency. The glass microspheres are resistant to heat and environmental impact factors that offer excellent thermal insulation and UV stability, making them prominent in specialty coatings and construction.
The polymer segment is experiencing the fastest growth in the market during the forecast period. Due to their molecular customisation and biocompatibility. They serve as biodegradable carriers in biomedical applications, enabling controlled drug release for chronic conditions and gene therapies by protecting sensitive pharmaceuticals. The shift to sustainable chemistry fuels growth in bio-based and compostable polymer spheres for cosmetics and packaging. By combining high performance with environmental safety, polymers drive innovation in specialized applications with chemical flexibility and biological safety.
Application Insights
Which Application Dominated the Microspheres Market?
The construction composites segment dominated the market with approximately 29% share in 2025, serving as lightweight, thermally efficient solutions for infrastructural development. Microspheres improve flow, reduce density by acting as microscopic lubricants, and create lightweight concrete and precast panels that are easier to transport and resistant to shrinkage and cracking. By Integrating them into building materials and composite matrix provides thermal barriers that lower energy consumption with improved insulation. As the global transition to sustainable construction grows, microspheres are essential for high-performance, eco-friendly composites. With a lower environmental impact.
The oil & gas segment is anticipated to grow fastest in the market during the forecast period. The growth is driven by energy industries pushing towards deepwater and ultra-deepwater exploration. The microsphere is essential in syntactic foams by supplying buoyancy for pipelines and risers under extreme hydrostatic pressure. They enable precise density control for lightweight cementing slurries, preventing collapses during drilling and reducing the costs of heavy machinery. The surging demand for pressure-resistant microspheres is due to rising offshore explorations and oil recovery practices sustained its leadership as a key tool for technological innovation.
Regional Insights
How did North America Dominate the Microspheres Market?
The North America microspheres market size was valued at USD 2.94 billion in 2025 and is expected to be worth around USD 5.15 billion by 2035, exhibiting at a compound annual growth rate (CAGR) of 5.76% over the forecast period from 2026 to 2035.
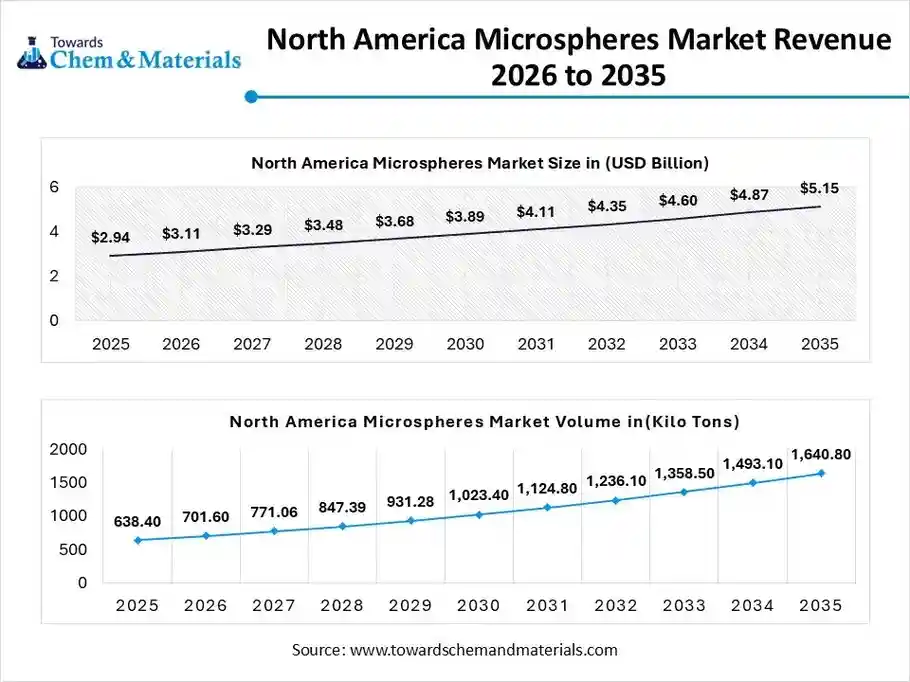
The North America microspheres volume was estimated at 638.4 kilo tons in 2025 and is projected to reach 1640.8 kilo tons by 2035, growing at a CAGR of 9.90% from 2026 to 2035. North America dominated the market with approximately 42% share in 2025. The industry is shifting from simple fillers to high-performance smart components for functional specialization. The market is driven by aerospace lightweighting, AI-driven manufacturing and sustainability initiatives. The manufacturers are integrating hollow spheres into advanced composites for improvement in fuel efficiency and thermal shielding, while the adoption of technology-based precision production supports cancer treatment and diagnostics. The market also promotes eco-friendly, high-margin applications that emphasize material consistency and multifunctionality.
U.S. Microspheres Market Growth Trends
The U.S. show dominance in the market due to its escalating domestic demand in key industries and its investment in innovation projects by enhancing performance to meet stringent regulations, to lower environmental impact and quality standards. The regional player driving the growth in manufacturing and local supply with the adoption of AI-driven navigation in medical and aerospace &defence that fueling the growth.
The Asia Pacific microspheres volume was estimated at 351.1 kilo tons in 2025 and is projected to reach 949.6 kilo tons by 2035, growing at a CAGR of 11.69% from 2026 to 2035. Asia Pacific is expected to grow at the fastest CAGR in the market during the forecast period due to its global leadership in lightweighting and electronics, with the implementation of hollow microspheres reducing vehicle weight and supporting battery management in electric vehicles. The construction projects use microsphere-infused composites for insulation and efficiency in smart city infrastructure due to the rising urban population, fueling the expansion. The region is also advancing in life sciences, producing high-precision polymer beads for diagnostics and therapeutic delivery. As industrialization accelerates shift toward sustainable, bio-based microspheres to meet the massive demand in the personal care and consumer goods sectors.
China Microspheres Market Growth Trends
China dominates the market due to its immense manufacturing base and supply chain infrastructure. The rising demand for electric vehicles creates the need for microspheres utilized in lightweight automotive components, while the rapid urbanization driving the demand for construction materials, which is strengthening its position.
Europe Microspheres Market Growth Trends
The Europe microspheres volume was estimated at 308.7 kilo tons in 2025 and is projected to reach 818.9 kilo tons by 2035, growing at a CAGR of 11.45% from 2026 to 2035.Europe show significant growth in the market, driven by its stringent environmental regulations to boost biodegradable, eco-friendly microspheres solutions. The rising adoption in diversified applications such as construction, medical & healthcare, personal care and especially in automotive due to demand for lightweight composites is pushing the regional growth.
Germany Microspheres Market Growth Trends
Germany led the European market due to demand for energy-efficient infrastructure and innovation for eco-friendly alternatives. Germany leads in medical technology and automotive lightweighting. Additionally, the rising consumer preference and strong government regulation are driving the growth.
Microspheres Market Volume and Share, By Region, 2025-2035
| By Region | Market Volume Share (%), 2025 | Market Volume (Kilo Tons)2025 | Market Volume (Kilo Tons)2035 | CAGR(%) 2026-2035 | Market Volume Share (%), 2035 |
| North America | 42.00% | 638.4 | 1,492.7 | 9.90% | 40.32% |
| Europe | 20.31% | 308.7 | 818.9 | 11.45% | 22.12% |
| Asia Pacific | 23.10% | 351.1 | 949.6 | 11.69% | 25.65% |
| Latin America | 8.32% | 126.5 | 242.1 | 7.48% | 6.54% |
| Middle East & Africa | 6.27% | 95.3 | 198.8 | 8.51% | 5.37% |
Recent Developments
- In November 2024, Sintx Technologies and NED Medical signed the joint development agreement that focuses on advancement in ceramic-based microspheres, especially for radiotherapeutic applications in oncology.(Source: www.nasdaq.com)
- In March 2025, Nouryon launched extra-small grade expandable Expancel® XS200 microspheres, offering a reduction in weight in interior decorative paints without compromising performance and surface finish with emphasis on sustainable growth.(Source: www.nouryon.com)
Top Microspheres Market Players and Their Offerings
- 3M Company: The global leader for technology that supplies high-performance glass and polymer microspheres with a strong focus on research and development.
- Potters Industries LLC: The global innovator in specializing in high-volume glass microspheres and glass feedstocks for industrial filler applications and road marking applications.
- Nouryon (Expancel): The global speciality chemicals leader known for expandable microspheres for raw material supply and global distribution networks in lightweight coatings and thermoplastics.
- Matsumoto Yushi-Seiyaku Co., Ltd: The Japanese pioneer known for expandable microspheres used for manufacturing in footwear and automotive applications.
- Trelleborg AB
- Chase Corporation
- Luminex Corporation
- AkzoNobel N.V.
- Cospheric LLC
- Sigmund Lindner GmbH
- Bangs Laboratories
- Merck KGaA
- Thermo Fisher Scientific
- Sekisui Chemical
- Mo-Sci Corporation
Segment Covered in the Report
By Type
Hollow Microspheres
Solid Microspheres
By Material
Glass
Polymer
Ceramic
Fly Ash/Cenospheres
Metallic & Other
By Application
Construction Composites
Healthcare & Biotechnology
Paints & Coatings
Oil & Gas
Automotive
Others (Cosmetics, Aerospace, etc.)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.