
Lithium Iron Phosphate Powder Market Size and Forecast 2026 to 2035
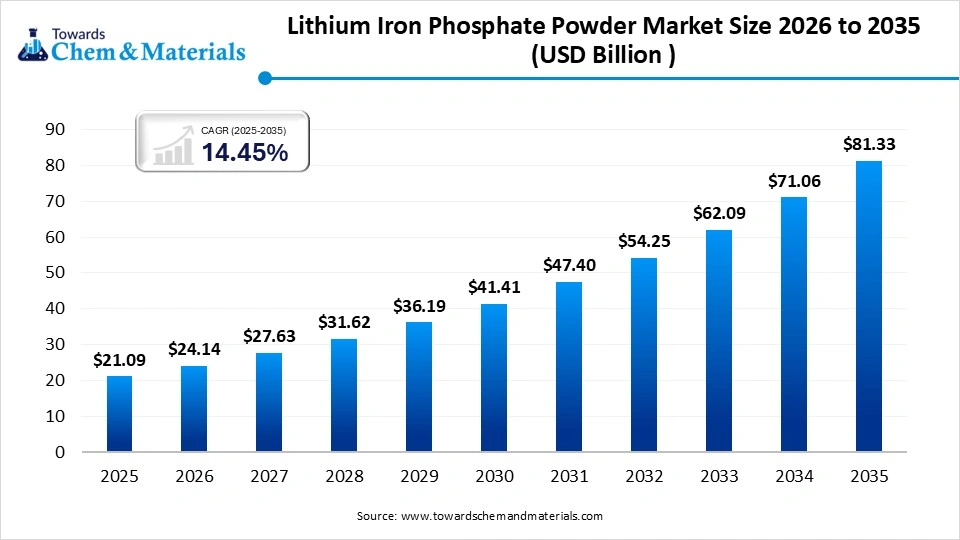
The global lithium iron phosphate powder market size was estimated at USD 21.09 billion in 2025 and is expected to increase from USD 24.14 billion in 2026 to USD 81.33 billion by 2035, growing at a CAGR of 14.45% from 2026 to 2035. Asia Pacific dominated the lithium iron phosphate powder market with the largest revenue share of 67.00% in 2025.The increased need for the establishment of energy storage systems has accelerated the industry's growth in recent years.The specific battery material, which is primarily used to make the cathode of lithium iron batteries, is known as the lithium iron phosphate powder. By helping batteries to store and release energy safely, the lithium iron phosphate powder has gained major industry attention in the modern electric era. Also, the renewable energy manufacturers are seen as demanding lithium iron phosphate powder to store renewable energy, such as solar and others.
Market Highlights
- The Asia Pacific dominated lithium iron phosphate powder market with the largest revenue share of 67.00% in 2025., due to its large battery manufacturing ecosystem.
- By region, Europe is anticipated to capture a greater portion of the market with a significant CAGR in the future, as the region is rapidly transforming its energy and transportation systems.
- By end use, the electric vehicle segment dominated the market and accounted for the largest revenue share of 70.00% in 2025, owing to EV batteries requiring large volumes of cathode material.
- By end use, the energy storage systems segment is expected to grow during the forecast period, due to electricity grids becoming more complex because renewable energy sources produce power at irregular times.
- By form type, the powder segment dominated the market and accounted for the largest revenue share of 72.00% in 2025.
- By application, the battery segment led the market with the largest revenue share of 80.00% in 2025.
Enhanced Battery Performance With Improved LEP
The industry is shifting towards the improvement of particle engineering and conductivity enhancement. Also, earlier LFP materials had lower electrical conductivity, which limited their performance in high-power applications. Manufacturers are now improving the powder structure by using smaller particles and adding conductive coatings that help electricity move more efficiently inside the battery.
What is Lithium iron Phosphate Powder used for?
- Battery Manufacturing: The most significant use of lithium iron phosphate powder is in the creation of LFP batteries. These batteries are widely used in Electric Vehicles (EVs) LFP batteries are commonly used in electric cars, buses, and other electric transportation systems due to their safety, long lifespan, and cost-effectiveness. the Energy Storage Systems LiFePOâ‚„ batteries are also used in stationary energy storage applications, helping store renewable energy from sources like solar and wind. the Consumer Electronics While less common than other lithium-ion battery chemistries, LFP batteries are used in some consumer devices such as power tools, laptops, and portable power banks.
- High Safety and Thermal Stability: LiFePOâ‚„ batteries are known for their excellent thermal stability and safety characteristics. They are less prone to overheating, fires, or explosions compared to other lithium-ion battery chemistries, like nickel-cobalt-aluminum (NCA) or nickel-cobalt-manganese (NCM) batteries.
- Long Cycle Life: LFP batteries have a longer lifespan compared to other battery chemistries, making them ideal for applications where durability and longevity are crucial. This makes them popular in renewable energy storage systems and electric vehicles, where extended battery life is a key advantage.
- Sustainable Energy: LiFePOâ‚„ batteries are considered more environmentally friendly than other lithium-based batteries because they do not contain toxic materials such as cobalt. This helps in reducing the environmental impact of battery manufacturing and disposal.
- Power Tools and Industrial Applications: LFP powder is also used to create batteries for power tools and industrial machinery. These applications benefit from the long cycle life, stability, and relatively low cost of LFP batteries.
- Grid-Scale Energy Storage: The energy storage industry uses lithium iron phosphate batteries for large-scale energy storage systems. These batteries help balance supply and demand in the power grid, storing excess energy produced during off-peak times and discharging it during high-demand periods.
Trade Analysis of the Lithium Iron Phosphate Powder Market:
Import, Export, Consumption, and Production Statistics
- The world has observed the sophisticated export of lithium iron phosphate with 1,250 shipments via 353 buyers and 318 exporters between July 2024 and June 2025 as per the published report.
- China emerged as the heavy exporter of the lithium iron phosphate with 2,421 shipments, while Mexico (173 shipments) and Hong Kong (72 shipments) are following.
- The United States has been seen as of greater import of lithium iron phosphate with 825 shipments, while Vietnam (722 shipments) and Peru (243 shipments) are following the United States nowadays.
Market Trends:
- The heavy shift towards the safer battery chemistry has driven strategic transformation and sectoral scalability in recent years. The manufacturers are using LIPP due to its better thermal stability, which is enhancing the industry readiness and future industry capabilities.
- The greater shift towards local battery production has opened profitable avenues in the current period. Moreover, every country is trying to reduce its dependence on the import of specific materials and is working to assemble and produce products from its own resources nowadays.
- The establishment of the heavy battery storage projects is likely to unlock new business opportunities during the forecast period. Also, solar and wind do not produce the same energy for many reasons, where these energy storage systems are likely to emerge as a catalyst for the strong supply.
Report Scope
| Report Attribute | Details |
| Market Size in 2026 | USD 24.14 Billion |
| Revenue Forecast in 2035 | USD 81.33 Billion |
| Growth Rate | CAGR 14.45% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Dominant Region | Asia Pacific |
| Segment Covered | By End Use, By Region |
| Key companies profiled | BYD Company Limited, Contemporary Amperex Technology Co. Limited (CATL), EVE Energy Co., Ltd., Gotion High-Tech Co., Ltd., Hunan Yuneng New Energy Battery Material Co., Ltd., LG Energy Solution Ltd., L&F Co., Ltd., SVOLT Energy Technology Co., Ltd., Tianjin Lishen Battery Joint-Stock Co., Ltd., Wanrun New Energy Technology Co., Ltd. |
Supply Chain Analysis of the Lithium Iron Phosphate Powder Market:
Distribution to Industrial Users
- Lithium Iron Phosphate (LFP) powder is distributed to industrial users, primarily battery manufacturers, via specialized chemical supply chains. It is typically shipped in bulk airtight drums or moisture-proof vacuum bags to maintain chemical stability.
- Suppliers often provide technical data sheets and batch-specific testing to ensure the powder meets strict energy density and safety standards for EV and energy storage production.
Chemical Synthesis and Processing
- LFP powder is typically synthesized via solid-state reaction or hydrothermal synthesis. Precursors like lithium carbonate, iron phosphate, and carbon sources are mixed, milled, and then calcined in an inert atmosphere.
- This process ensures high crystallinity and a carbon coating, which are essential for enhancing the powder's electrical conductivity.
Regulatory Compliance and Safety Monitoring
- Regulatory compliance for LFP powder involves adhering to REACH and GHS standards for chemical labeling. Safety monitoring focuses on dust explosion prevention and specialized storage to avoid moisture-induced degradation.
- Facilities must implement ventilation controls and fire-suppression systems tailored for lithium-based materials to mitigate thermal and inhalation risks.
Lithium Iron Phosphate Powder Market Regulatory Landscape: Global Regulations
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Environmental Protection Agency (EPA) | Toxic Substances Control Act (TSCA) Section 5 & 8: Requires manufacturers and importers to notify the EPA of new chemical substances and maintain records on health and environmental effects. | Chemical risk evaluation, worker exposure during processing, and strict packaging/documentation standards for hazardous material transit. |
| European Unio | European Chemicals Agency (ECHA). | REACH Regulation (EC) No 1907/2006: Mandates registration and evaluation for any chemical substance produced or imported at volumes over one tonne per year. | Focus Areas: Circular economy goals (recycled content targets), environmental impact transparency, and updated hazard classes for persistent or toxic substances. |
| China |
Ministry of Ecology and Environment (MEE) |
Announcement No. 58 of 2025: Implements new export control licenses for high-performance LFP cathode materials and related manufacturing equipment. |
National security via technology export licensing, standardizing recycled material imports, and safeguarding the domestic LFP supply chain. |
Segmental Insights
End Use Insights
How did the Electric Vehicle Segment Dominate the Lithium Iron Phosphate Powder Market in 2025?
The electric vehicle segment dominated the market share 70.00% in 2025, due to EV batteries require large volumes of cathode material. Moreover, as more people switch from gasoline vehicles to electric vehicles, battery production increases significantly. LFP batteries are particularly popular in vehicles designed for everyday commuting because they offer long life, strong safety, and lower production costs. Automakers prefer them for vehicles where affordability and durability are more important than maximum driving range.
The energy storage systems (ESS) segment is expected to grow with a rapid CAGR, owing to electricity grids becoming more complex because renewable energy sources produce power at irregular times. Also, the large battery systems are increasingly used to stabilize the grid by storing electricity and supplying it when needed. These systems require batteries that can last for many years and perform thousands of charge cycles without significant degradation.
Lithium Iron Phosphate Powder Market Share, By End Use, 2025 (%)
| By End Use | Revenue Share, 2025 (%) |
| Electric Vehicles | 70.00% |
| Energy Storage Systems (ESS) | 14.00% |
| Electric Two/Three Wheelers | 9.00% |
| Industrial & Other Applications | 7.00% |
- Electric Vehicles – Dominating with a 70.00% share, rapid EV adoption, strong demand for cost-effective and safe battery chemistries, and large-scale production drive overwhelming market leadership.
- Energy Storage Systems (ESS) – With a 14.00% share, increasing deployment of renewable energy and grid storage solutions supports steady growth in this segment.
- Electric Two/Three Wheelers – Holding a 9.00% share, rising adoption in urban mobility and cost-sensitive markets contributes to moderate demand.
- Industrial & Other Applications – Making up 7.00% of the market, niche uses in backup power and industrial equipment result in a smaller overall contribution.
Form Insights
How did the Powder Segment Dominate the Lithium Iron Phosphate Market in 2025?
The powder form segment held the largest market share 72.00% in 2025, accounting for approximately share 72.00% of the LFP market by form. This dominance was primarily driven by its central role in battery manufacturing, particularly for cathode production in LFP batteries. Powdered lithium iron phosphate offers consistent particle size distribution and high purity, which are critical for achieving uniform electrochemical performance and optimal battery cycle life. These properties enable precise coating and mixing during electrode fabrication, making powder the preferred form for large‑scale lithium iron phosphate battery production. As electric vehicle (EV) adoption continued to grow, demand for high‑quality powder material increased accordingly.Additionally, the powder form’s compatibility with advanced battery production technologies helped it remain the default choice for major LFP battery manufacturers, further solidifying its share in 2025.
The granules segment is expected to grow with a rapid CAGR, owing to its advantages in handling, storage, and large-scale manufacturing processes. Granular LFP materials reduce dust formation and improve flowability during automated battery production, which helps increase operational efficiency in manufacturing facilities. In addition, granules are easier to transport and store compared to fine powders, minimizing material loss and improving workplace safety. As battery manufacturers continue to expand production capacity, the demand for granulated LFP materials is expected to grow, particularly in facilities focusing on high-volume battery cell manufacturing.
Lithium Iron Phosphate Powder Market Share, By Form, 2025 (%)
| By Form | Revenue Share, 2025 (%) |
| Powder | 72.00% |
| Granules | 16.00% |
| Suspension/dispersion | 12.00% |
- Powder – Dominating with a 72.00% share, its superior processability, uniform particle distribution, and widespread use in battery cathode manufacturing drive strong market preference.
- Granules – With a 16.00% share, improved handling and reduced dust formation support moderate adoption, though limited flexibility in processing restricts broader usage.
- Suspension/Dispersion – Holding a 12.00% share, growing use in advanced coating and slurry applications supports niche demand, but lower scalability limits overall market share.
By Application
The battery segment dominated the market share 80.00% in 2025, largely due to the growing demand for high-performance, cost-effective energy storage solutions, particularly for electric vehicles (EVs) and energy storage systems (ESS). LFP powder is integral to the production of LFP cathodes, which are widely used in lithium-ion batteries. These batteries are favored in EVs because of their long cycle life, thermal stability, and affordability.In electric vehicles, LFP batteries are increasingly used for their safety features, such as high chemical stability and lower risk of thermal runaway. This has made them especially suitable for entry-level electric vehicles, where cost-effectiveness and longevity are key priorities.
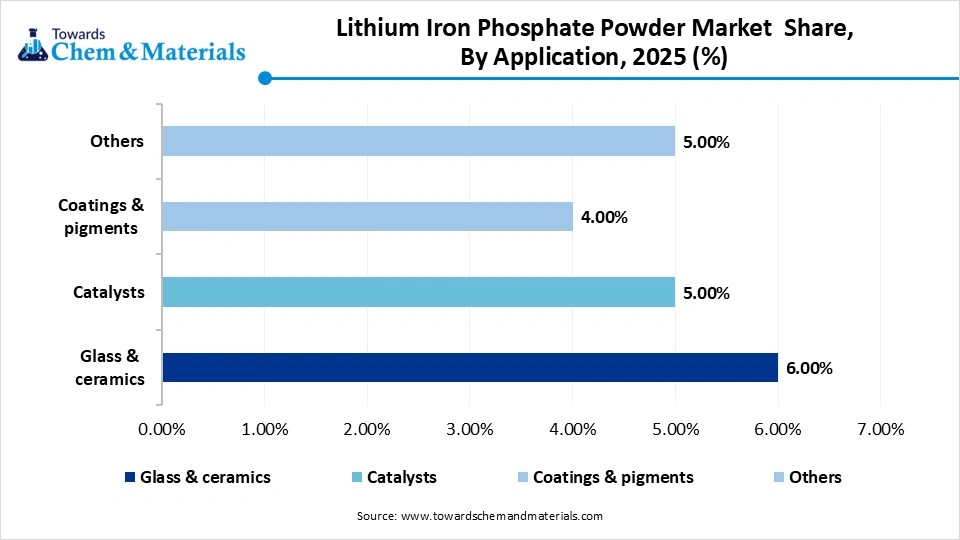
The glass & ceramics segment also witnessed egment is expected to grow with a rapid CAGR. LFP powder is used as a fluxing agent in the manufacturing of glass and ceramic products. It helps improve the melting behavior, reduces the melting temperature, and enhances the durability of these products. With increasing industrial production and demand for advanced ceramic products, the demand for LFP powder in this application is poised to grow steadily.In ceramics, LFP powder is widely used in the production of electronic ceramics, insulating materials, and catalysts, among others. As industries focusing on high-performance ceramics grow, the application of LFP powder in ceramics is expected to expand in line with the increasing demand for advanced materials.
Lithium Iron Phosphate Powder Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Battery | Battery |
| Glass & ceramics | 6.00% |
| Catalysts | 5.00% |
| Coatings & pigments | 4.00% |
| Others | 5.00% |
- Battery – Dominating with the highest share, extensive use in lithium-ion battery cathodes for electric vehicles and energy storage systems drives overwhelming demand.
- Glass & Ceramics – With a 6.00% share, its use in specialty materials and thermal applications supports moderate but limited market contribution.
- Catalysts – Holding a 5.00% share, niche applications in chemical reactions sustain steady demand, though overall usage remains low.
- Others – With a 5.00% share, smaller and diverse applications contribute limited demand due to lack of scale.
- Coatings & Pigments – With a 4.00% share, usage in coloring and protective coatings remains minimal, restricting broader market impact.
Regional Insights
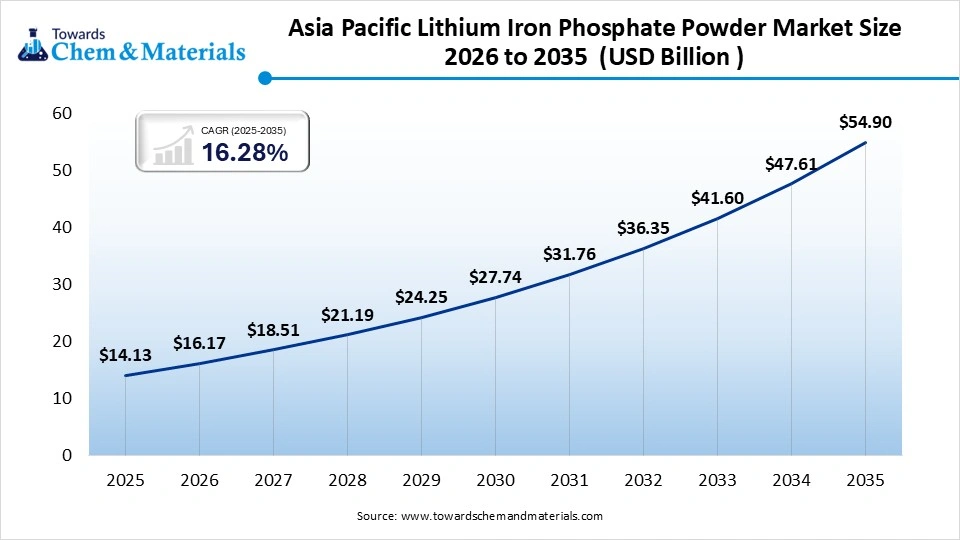
The Asia Pacific lithium iron phosphate powder market size was valued at USD 14.13 billion in 2025 and is expected to be worth around USD 54.90 billion by 2035, exhibiting at a compound annual growth rate (CAGR) of 16.28% over the forecast period from 2026 to 2035. Asia Pacific dominated the lithium iron phosphate powder market share 67.00% in 2025, due to its large battery manufacturing ecosystem. Many companies in this region specialize in producing battery materials, battery cells, and electric vehicles. This concentration of related industries creates a strong supply chain that makes production more efficient in the coming years. Governments in the region have also strongly supported electric vehicle adoption and renewable energy development.
China Powers Global Electric Battery Production
China maintained its dominance in the market, owing to it built a large and integrated battery industry early. Moreover, the country produces huge numbers of electric vehicles, buses, and energy storage batteries. To support this production, many domestic companies invested heavily in battery material manufacturing, including LFP powder. China also has a strong industrial infrastructure that allows raw materials, battery components, and finished batteries to be produced within the same supply chain.
Lithium Iron Phosphate Powder Market Evaluation in Europe
Europe are expected to capture a major share of the lithium iron phosphate powder market with a rapid CAGR, owing to the region rapidly transforming its energy and transportation systems. Many European countries are moving aggressively toward electric vehicles and renewable electricity generation to reduce carbon emissions. This transition requires large numbers of batteries for vehicles and energy storage systems.
Germany Accelerate Lithium Iron Phosphate Powder Market
Germany is expected to emerge as a prominent country for the lithium iron phosphate powder market in the coming years, due to the country has one of the largest automotive industries in the world and is investing heavily in the transition to electric mobility. Many German manufacturers are building new battery production facilities to support this shift. Also, Germany is expanding renewable energy projects such as wind and solar power, which require energy storage solutions.
North America Lithium Iron Phosphate Powder Market Examination
North America is notably growing in the industry, owing to the region's investment in clean energy technologies. Governments and private companies are supporting electric vehicle production and battery manufacturing through incentives and infrastructure development. Another important factor is the effort to build domestic supply chains for battery materials to reduce reliance on imports.
United States Battery Industry Growth Accelerates
United States is expected to gain a significant industry share owing to country increases its investment in battery technology and clean energy. Many companies are building new electric vehicle plants and battery manufacturing facilities. The country is also expanding renewable energy installations such as solar farms, which require large battery storage systems. These developments increase the demand for durable and safe battery materials.
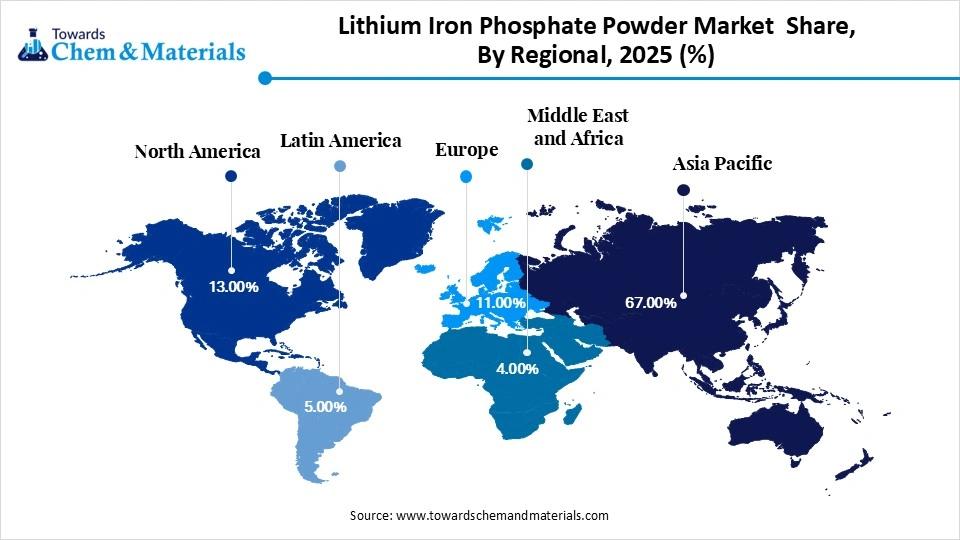
Lithium Iron Phosphate Powder Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| North America | 13.00% |
| Europe | 11.00% |
| Asia Pacific | 67.00% |
| Latin America | 5.00% |
| Middle East & Africa | 4.00% |
- Asia Pacific – Dominating with a 67.00% share, strong battery manufacturing ecosystems, high electric vehicle production, and significant investments in energy storage drive market leadership.
- North America – With a 13.00% share, growing EV adoption and increasing domestic battery production support steady market expansion.
- Europe – Holding an 11.00% share, stringent emission regulations and rising investments in gigafactories contribute to consistent demand.
- Latin America – With a 5.00% share, emerging industrial activities and gradual adoption of energy storage technologies result in limited market presence.
- Middle East & Africa – Making up 4.00% of the market, early-stage battery market development and lower EV penetration restrict overall demand.
Recent Developments
- In September 2025, The Dynanomic has introduced the fifth generation of high-performance LFP material. Also, this material is compatible for both energy storage and power applications as per the company's claim.(Source: www.energytrend.com)
In July 2025, the First Phosphate Corp has introduced lithium iron phosphate (“LFP”) battery cells, which have an 18650 format. Also, the newly introduced cell has been made by North American-sourced critical minerals as per the published report.(Source: firstphosphate.com)
Top Vendors in the Lithium Iron Phosphate Powder Market & Their Offerings:
- BYD Company Limited: BYD is a vertically integrated titan that manufactures both electric vehicles and their batteries under the Fudi brand. It is famous for its Blade Battery, a safe, high-density LFP solution. By 2026, BYD aims to sell 1.3 million vehicles abroad and expand production to over 600 GWh globally.
- Contemporary Amperex Technology Co. Limited (CATL) :CATL is the world's largest EV battery manufacturer, commanding nearly 40% of the global market. It supplies giants like Tesla, BMW, and Volkswagen. Recent innovations include a 1.5-million-mile battery and "Qilin" cell-to-pack technology, solidifying its role as a leader in zero-carbon energy storage and high-speed charging.
- EVE Energy Co., Ltd.: EVE Energy is a top-three global energy storage manufacturer and a pioneer in cylindrical batteries, operating the sector's first "Lighthouse Factory." It is a key BMW supplier and plans to launch all-solid-state batteries by 2026, targeting energy densities of 350 Wh/kg for next-generation EVs.
- Gotion High-Tech Co., Ltd.: Gotion is a strategic technology partner for Volkswagen Group, specializing in the "Unified Cell" for mass-market EVs. It is currently scaling its GEMSTONE solid-state batteries and expanding globally with new plants in the U.S. and Europe to support Volkswagen’s 2026–2032 electrification roadmap.
- Hunan Yuneng New Energy Battery Material Co., Ltd.
- LG Energy Solution Ltd.
- L&F Co., Ltd.
- SVOLT Energy Technology Co., Ltd.
- Tianjin Lishen Battery Joint-Stock Co., Ltd.
- Wanrun New Energy Technology Co., Ltd.
Segments Covered in the Report
By End Use
- Electric Vehicles
- Energy Storage Systems (ESS)
- Electric Two/Three Wheelers
- Industrial & Other Applications
By Form
- Powder
- Granules
- Suspension/dispersion
By Application
- Battery
- Glass & ceramics
- Catalysts
- Coatings & pigments
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.