
Industrial Oil Market Size Analysis Report 2035
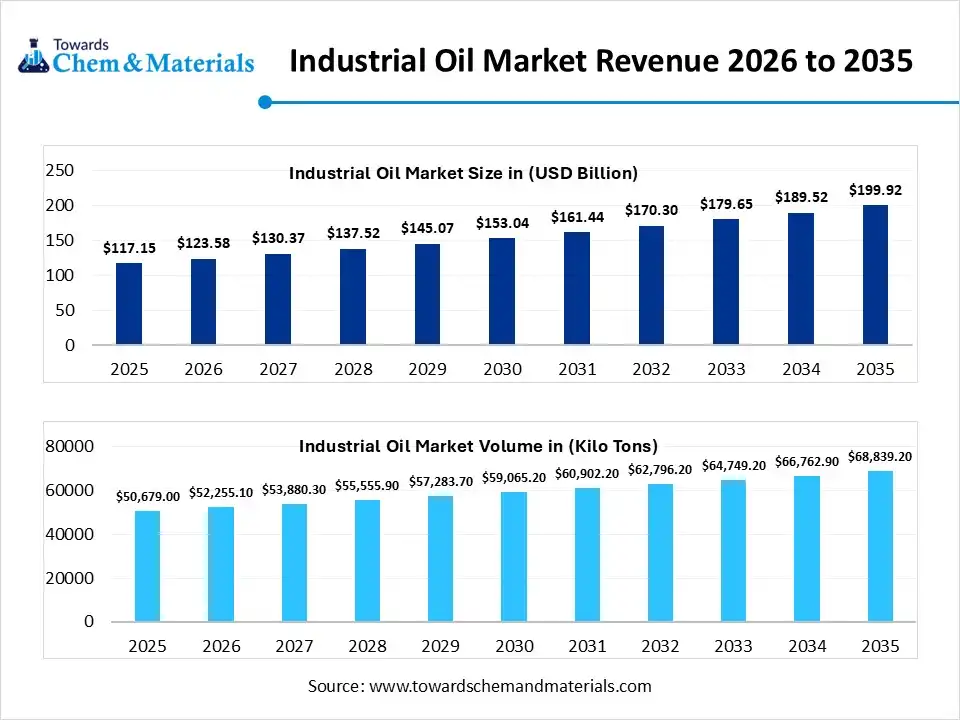
The global industrial oil market size was estimated at USD 117.15 billion in 2025 and is expected to increase from USD 123.58 billion in 2026 to USD 199.92 billion by 2035, growing at a CAGR of 5.49% from 2026 to 2035. In terms of volume, the market is projected to grow from 50,679.0 kilo tons in 2025 to 68,839.2 kilo tons by 2035. growing at a CAGR of 3.11% from 2026 to 2035. Asia Pacific dominated the industrial oil market with the largest volume share of 45.19% in 2025. Global expansion of manufacturing, automotive, and construction industry increased machinery usage, and rising industrialization in various sectors driving the market growth.
Market Highlights
- The Asia Pacific dominated the global industrial oil market with the largest volume share of 45.19% in 2025.
- The Europe industrial oil market segment accounted for the major volume share of 10.00% in 2025.
- By source, the soybean oil segment dominated the market and accounted for the largest volume share of 20.20% in 2025.
- By type, Grade I (light) segment led the market with the largest revenue volume share of 45.3% in 2025.
- By end use the biofuel segment dominated the market and accounted for the largest volume share of 31.39% in 2025.
Growing Demand of lubricants and grease from automotive, manufacturing, and construction industry accelerate the market expansion
Industrial oil is known as industrial lubricant, is a compound which is used in machinery and equipment to reduce friction, wear, and tear for smooth operation. They are specially developed to protect the machines from damage like rust and corrosion. Rapid economic development and industrialization are major factors contributing to increased demand of industrial oil. Expanded manufacturing process, increased use of machinery and demand of specialized lubricant boost market growth.
Automotive manufacturing process depends on various lubricants like engine oil, gear oil, and transmission fluids for functioning and maintenance of vehicles, propel the market growth. Construction industries use a variety of lubricants for heavy machinery like excavators and bulldozers for smooth operation. Use of industrial oil in this automotive and construction sector boosts the industrial oil market growth.
Recent Market Trends
- Growing demand from industrial oil in automotive and manufacturing industry- Expansion of automotive industry increases number of vehicles, demands the lubricants like engine oil, transmission fluids for proper functioning of vehicle.
- Increased Electric vehicle also requires specialized lubricants. Growing use of heavy machinery highly demands lubricants to reduce friction, prevent wear and tear, and maintain operational efficiency, boost market growth.
- Advancement in lubrication technology- Advancement in lubricant technology improves the functioning, efficiency and sustainability which drives the market.
- New advancement like synthetic lubricants, nanotechnology and other method improve performance, reduce friction and heat, overall improving the lifespan of equipment so increased demand of the advanced lubricant driving the market.
- Increasing trend towards sustainable lubricants- Increased awareness of environmental impact of traditional lubricants demands sustainable lubricants very highly. These sustainable lubricants are derived from renewable sources, biodegradable and nontoxic, which have no negative effect on environment.
- Biobased lubricants which derived from vegetable oil and animal fats possess low toxicity and biodegradability and low carbon footprint. So Increased demand of sustainable solution boosts the industrial oil market.
Report Scope
| Report Attributes | Details |
| Market Size and Volume in 2026 | USD 123.58 Billion / 52,255.1 Kilo Tons |
| Expected Market Size and Volume in 2035 | USD 199.92 Billion/ 68,839.2 Kilo Tons |
| Growth Rate | CAGR of 5.49% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Dominant Region | Asia Pacific |
| Units Considered | Value (Billion / Million), Volume (Kilo Tons) |
| Segment Covered | By Source, By Type, By End-Use, By region |
| Key Companies Profiled | Matole Ltd,Exxon Mobil Corporation,Bunge Limited,Castrol Limited,LLC PK “XimProm”,Wilmar International,Soya Mills SA,China Petrolium & Chemical Corporation,AAK Kanmani,Malplast Industries Limited, Royal Dutch Shell Plc,Chevron USA Inc,Buhler Group,KratanCorporation,Fujian Qian Trading Co. Ltd,Archer Daniels Midland ,Gemtek Products,Cargill Incorporated |
Market Opportunity
Increased Environmental Regulation Demands Eco-Friendly Product
Government strict regulation and standards to reduce industrial pollution, sustainable practice demand the conventional alternative which are environment friendly and comply with regulation. Increased innovation to develop eco friendly sustainable product by utilizing renewable sources, drives the market. Rising innovation and development to develop biodegradable product, shows future market opportunities to boost the industrial oil market.
Advancement In Sustainable Lubricant
Innovation and development in sustainable lubricant including water-based lubricants, bio based synthetic lubricants, vegetable-based lubricant, these are developed from renewable sources which are biodegradable and possess very less environmental impact boosting the market. Lubricants made from soybean oil, sunflower oil are biodegradable and offer excellent lubricant properties. The sustainable lubricants, which possess very little environmental impact, are showing significant market oppournities for industrial oil market.
Market Challenges
Fluctuation In Crude Oil Prices
Rising crude oil prices cause higher production costs for industries that rely on oil derived products. Fluctuation in crude oil prices increases production cost, impacting the profitability which reduced investment in the industrial sector.
The unpredictability of oil prices is main challenge for investor because it can lead to a wait-and-see approach, so companies postpone investments until the market stabilizes which reduces the economic growth. This reduced investment negative impact on innovation, technological advancements, and overall industrial development, limits the industrial oil market.
Rising Environmental Concern
Government implementing strict environment regulation in amount of pollutant released in air and for waste disposal which demand biodegradable alternative. The oil industry is also facing challenges related to climate change, which I shifting a move towards renewable energy sources and cleaner technologies.
Value Chain Analysis
Research and Development
- This involves developing high-performance synthetic fluids, bio-based lubricants, and specialized additives to meet tightening environmental regulations and OEM specifications.
- Key Players: Lubrizol, BASF, Chevron Oronite, Infineum, ExxonMobil, and Shell.
Manufacturing, Blending, and Refining
- This involves complex refining of crude oil into base oils and the subsequent blending of additives to create finished industrial lubricants.
- Key Players: ExxonMobil, Shell, TotalEnergies, BP, Chevron, FUCHS, China Petroleum & Chemical Corp, and Petronas.
Logistics, Packaging, and Supply Chain
- This involves a specialized distribution network involving bulk shipping, tanker trucks, and drum filling to industrial sites.
- Key Players: DHL Supply Chainand Schneider National.
Distribution and Commercialization
- This emphasizes technical support, offering lubrication as a service to ensure equipment uptime.
- Key Players: W.W. Grainger and McMaster-Carr.
Application and Technical Services
- This involves condition monitoring to optimize maintenance cycles and reduce waste.
- Key Players: Siemens, Rio Tinto, Toyota, and
Segmental Insights
By Source Insights
The soybean oil segment held the dominating share of the industrial oil market in 2025. Due to widespread use in food industry including cooking and frying, salad dressing increased demand of soybean oil. It has various applications in paints, coatings, biodiesel, and even pharmaceuticals boost the market growth of this segment. Due to popularity of fried food in Asia pacific increased demand of soybean oil for frying and cooking. Increasing global demand of edible oil contributes to dominance of soybean oil market.
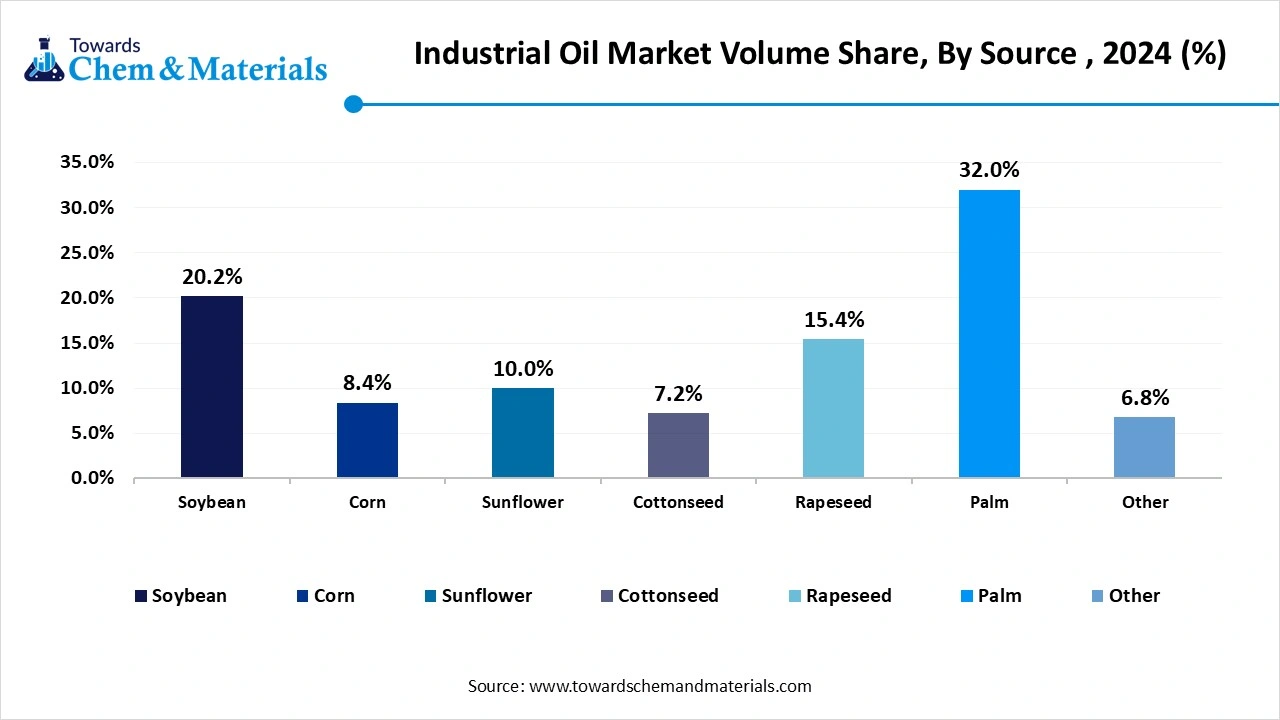
The palm oil segment is observed to grow at the fastest rate during the forecast period. Due to high yield and versatility palm oil is used in various countries. It has various applications in food and beverages, cosmetic, and pharmaceutical use. In Fractionated palm oil is a refined form of palm oil, has a large market share due to its diverse properties and applications. Increasing global demand of palm oil and biofuel may boost the market growth In future.
Industrial Oil Market Volume Share, By Source, 2025(%)
| By Source | Volume Share, 2025 (%) | Market Volume (KiloTons) 2025 (%) |
| Soybean oil | 20.20% | 9,833.16 |
| Corn oil | 8.40% | 4,089.04 |
| Sunflower oil | 10.00% | 4,867.90 |
| Cottonseed oil | 7.20% | 3,504.89 |
| Rapeseed oil | 15.40% | 7,496.57 |
| Palm oil | 32.00% | 15,577.28 |
| Other | 6.80% | 3,310.17 |
By Type Insights
The Grade I (light) segment held the dominating share of the industrial oil market in 2025. Grade I is a light oil base and typically derived from crude oil which possesses lower saturation percentage. It is used in gear oils to lubricate machinery and hydraulic fluids for power transmission. It is used as raw material in industries like cosmetics, personal care and pharmaceutical. Grade I oils associated with renewable sources attractive to business and consumer who prioritize sustainability. Growing industrial production is driving Grade I oil due to easy availibity and low manufacturing cost.
The Grade II (medium) segment was observed to grow at the fastest rate during the forecast period. This oil possesses better volatility, flashpoints, and viscosity index as compared to grade I base oils. Grade II oils have wide range of applications including oxidative stability and high temperature. These oils are preferred to be used in marine, gas engine, and trunk piston engine oils, as well as other industrial uses. Group II oils meet strict environment regulation, boost market growth. Its affordability, high performance and wider application contributed to its market growth.
Industrial Oil Market Volume Share, By Type, 2025 (%)
| By Type | Market Volume Share (%) | Market Volume (KiloTons) |
| Grade I (Light) | 45.90% | 23,461.23 |
| Grade II (Medium) | 35.12% | 17,949.07 |
| Grade III (Heavy) | 18.98% | 9,702.65 |
By End Use Insights
The biofuel segment held the dominating share of the industrial oil market in 2025. Biofuel is lower emission alternative to traditional fossil fuels which contributing to environmental protection. Particularly liquid biofuel which derived from vegetable oil led the market. growing demand for cleaner fuels, favorable government policies, and the increasing use of vegetable oils contributing to market growth of biofuel. Technological advancement for production of advanced biofuel with higher energy densities and cleaner combustion profiles and supportive government policies, boost the market growth of this segment.
The paints and coating segment observed to grow at the fastest rate during the forecast period. Increased need for protecting equipment and infrastructure from corrosion, especially in harsh environments like oil and gas operations.
Industrial oils can be incorporated into the formulation to improve the coatings resistance to various corrosive agents which extend lifespan of coated structures and equipment. Increased demand for solvent-borne and water-borne industrial coating because of durability, resistance to chemicals, and superior performance in various applications. The expansion of industries in oil and gas sector fuels the demand for paint and coating segment.
Industrial Oil Market Volume Share, By End Use, 2025 (%)
| End Use | Market Volume Share (%) | Market Volume (KiloTons) |
| Pharmaceutical | 10.36% | 5,296.66 |
| Cosmetics and Personal Care | 15.49% | 7,918.00 |
| Biofuel | 31.39% | 16,045.76 |
| Paints and Coating | 19.52% | 9,978.32 |
| Others | 23.23% | 11,874.21 |
Regional Insights
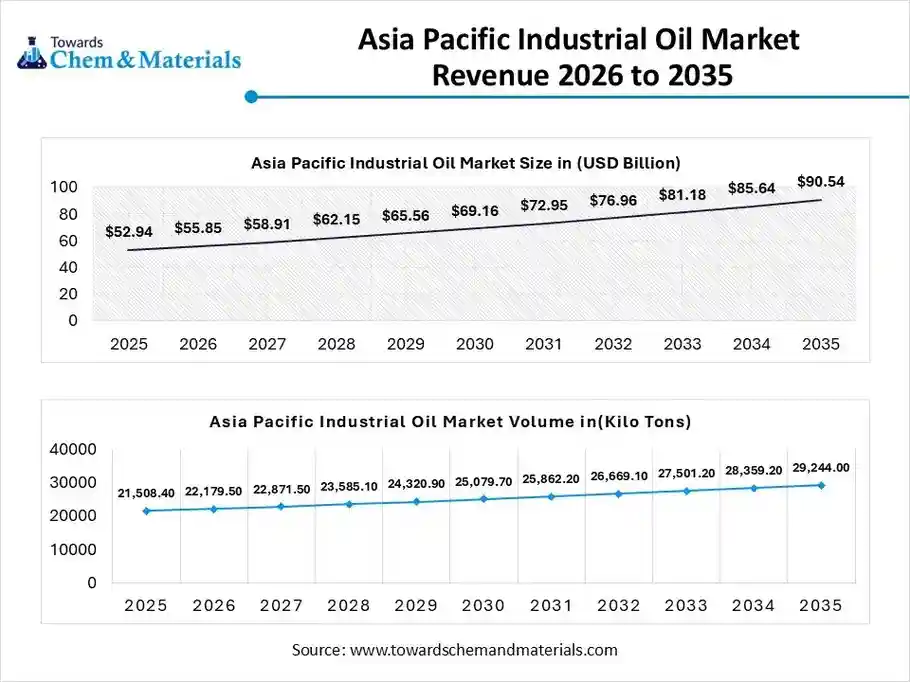
The Asia pacific industrial oil market size was valued at USD 52.94 billion in 2025 and is expected to be worth around USD 90.54 billion by 2035, exhibiting at a compound annual growth rate (CAGR) of 5.52%over the forecast period from 2026 to 2035.The Asia pacific industrial oil volume was estimated at 21,508.4 kilo tons in 2025 and is projected to reach 29,244.0 kilo tons by 2035, growing at a CAGR of 3.12% from 2026 to 2035. Asia pacific dominated industrial oil market in 2025. Rapid industrialization, urbanization and growing demand from various industries like automotive and manufacturing, boost the market growth. Rising infrastructure project and manufacturing sector particularly in India, china and Southeast Asian nations demands the industrial oil for construction, machinery and transportation.
China is a leading consumer of lubricants in the Asia-Pacific region due to its large automotive market and expanded industrial sector. In china The growth of the electric vehicle in China demands the specialized lubricant which boost the market in this region. In the countries like Japan and India are having strict emission regulation, driving the adoption of high-performance and synthetic lubricants. Their focus is on reducing greenhouse gas emission and promoting cleaner fuels.
North America is expecting significant growth in industrial oil market during the forecast period. Rising automotive and aerospace industries in this region demand lubricant boost the market in this region. North America, especially the US and Canada, has a well-established industrial sector they are dependent on the lubricants in various applications like automotive, industrial machinery, and metalworking. In this region there are Major investments in infrastructure projects, such as transportation and energy grids, are also contributing to the growth of the industrial lubricants market.
These projects require lubricants to support the operation and maintenance of heavy machinery. This region is major consumer of automotive and industrial lubricants and exporting lubricants contribute to global market growth. Technological advancement in lubricant formulation, increased environmental concern demand synthetic lubricants contributing to industrial oil market growth in this region.
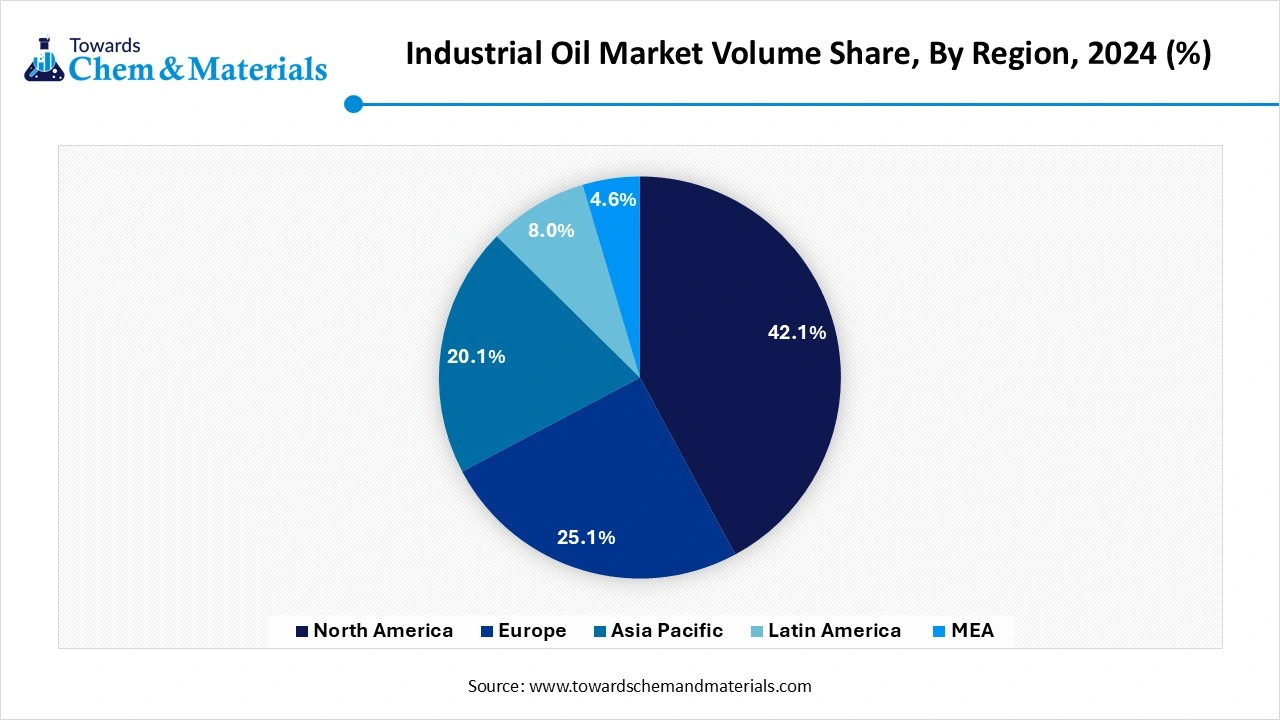
Industrial Oil Market Volume Share, By Region, 2025(%)
| By Region | Market Volume Shares 2025 (%) | Volume (KiloTons)(2025) |
| North America | 35.00% | 25,939.72 |
| Europe | 10.00% | 9,440.52 |
| Asia Pacific | 45.19% | 7,866.25 |
| Latin America | 5.00% | 4,717.71 |
| Middle East and Africa | 4.81% | 3,148.54 |
How will Europe be considered Notable growth in the Industrial Oil Market?
Europe is currently experiencing notable growth in the global market. This growth is mainly driven by its dense manufacturing base, high demand for specialized lubricants, and significant petrochemical refining capacity. The region is home to sophisticated refineries that are particularly adept at handling complex refining processes for both naphtha and gasoline production. Additionally, strict European government regulations on carbon emissions are prompting a shift toward bio-based and biodegradable lubricants. Europe has a high concentration of automotive, construction, mining, and heavy manufacturing industries, which are key factors in driving market expansion.
Germany Industrial Oil Market Trends
Germany plays a distinctive role within the region, acting as a major industrial hub with a strong demand for oil products to support its manufacturing sector. Its focus is increasingly on energy transition, reducing dependence on imports, and enhancing efficiency in petrochemicals and industrial lubricants. This high demand is influencing global import trends and necessitating infrastructure for receiving petroleum products.
How will Latin America Surge in the Industrial Oil Market?
Latin America is also experiencing significant growth in the global market, primarily due to surging offshore production in Brazil and Guyana, increased investment in infrastructure, and rising demand for high-performance lubricants. Growing industrial activity, along with automotive manufacturing and infrastructure development, is increasing the demand for industrial, hydraulic, and specialized lubricants. The region is attracting foreign investment thanks to its openness in key markets and the need for alternative, stable oil supplies to replace riskier regions, contributing significantly to the global supply.
How will the Middle East and Africa contribute to the Industrial Oil Market?
The Middle East and Africa are key contributors to the global market, largely due to increasing infrastructure development, construction projects, and manufacturing initiatives. These factors drive high demand for industrial lubricants and refined products. The region also holds the worlds proven petroleum reserves, making it crucial for global supply, particularly with leading producers like Saudi Arabia, Iraq, and the UAE. Rich mineral resources in this area drive significant mining operations, which require large amounts of industrial lubricants.
The UAE Industrial Oil Market Trends
The UAE plays a significant role in the Middle East, characterized by its position as one of the worlds top ten producers with substantial reserves. The UAE utilizes its strategic location for global oil trade and plays a crucial role in maintaining market stability. It is aggressively investing in increasing its daily production of crude and liquid fuels and is focused on diversifying its economy through investments in upstream, downstream, and petrochemicals.
Recent Developments
- In September 2025, Valvoline Cummins India launched All Fleet Full Synthetic CK4, India’s first full synthetic CK4 engine oil for heavy-duty diesel engines. This innovation offers significantly improved engine protection and is backward compatible with BSIV engines, underscoring Valvoline’s commitment to supporting India’s evolving commercial vehicle market.(Source:www.autocarpro.in)
Top Companies List Of Industrial Oil Market
- Matole Ltd
- Exxon Mobil Corporation
- Bunge Limited
- Castrol Limited
- LLC PK “XimProm”
- Wilmar International
- Soya Mills SA
- China Petrolium & Chemical Corporation
- AAK Kanmani
- Malplast Industries Limited
- Royal Dutch Shell Plc
- Chevron USA Inc
- Buhler Group
- Kratan Corporation
- Fujian Qian Trading Co. Ltd
- Archer Daniels Midland
- Gemtek Products
- Cargill Incorporated
Segments Covered in the Report
By Source
- Soybean
- Corn
- Sunflower
- Cottonseed
- Rapeseed
- Palm
- Other
By Type
- Grade I ( Light)
- Grade II ( Medium)
- Grade III ( Heavy)
By End Use
- Pharmaceutical
- Others
- Biofuel
- Paints and coating
- Cosmetics and personal care
By Regional
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- The Middle East and Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.