Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
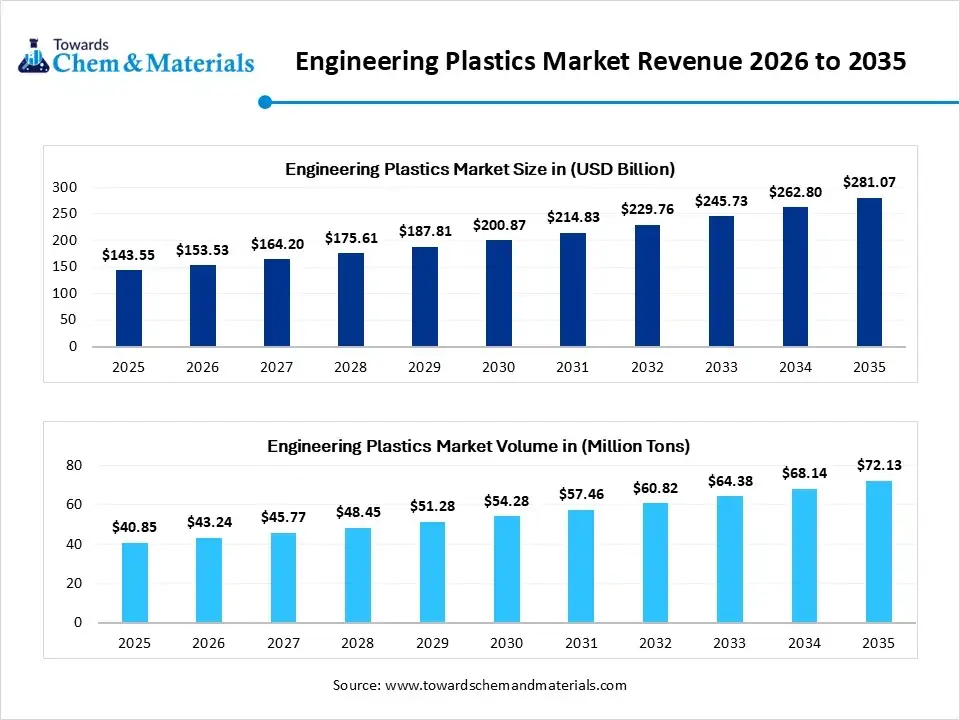
The engineering plastics market size was valued at USD 143.55 billion in 2025, is estimated to reach USD 153.53 billion in 2026, and is projected to reach USD 281.07 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 6.95% over the forecast period from 2026 to 2035. Asia Pacific dominated the engineering plastics market with the largest revenue share of 41% in 2025 and is expected to grow at the fastest CAGR of 7.08% during the forecast period. In terms of volume, the engineering plastics market is projected to grow from 40.85 million tons in 2025 to 72.13 million tons by 2035. growing at a CAGR of 5.85% from 2026 to 2035. The advanced thinking and high-value material have created their own industry presence. Also, the green plastic movement is expected to emerge as a profitable and remarkable revolution in the future industry standards.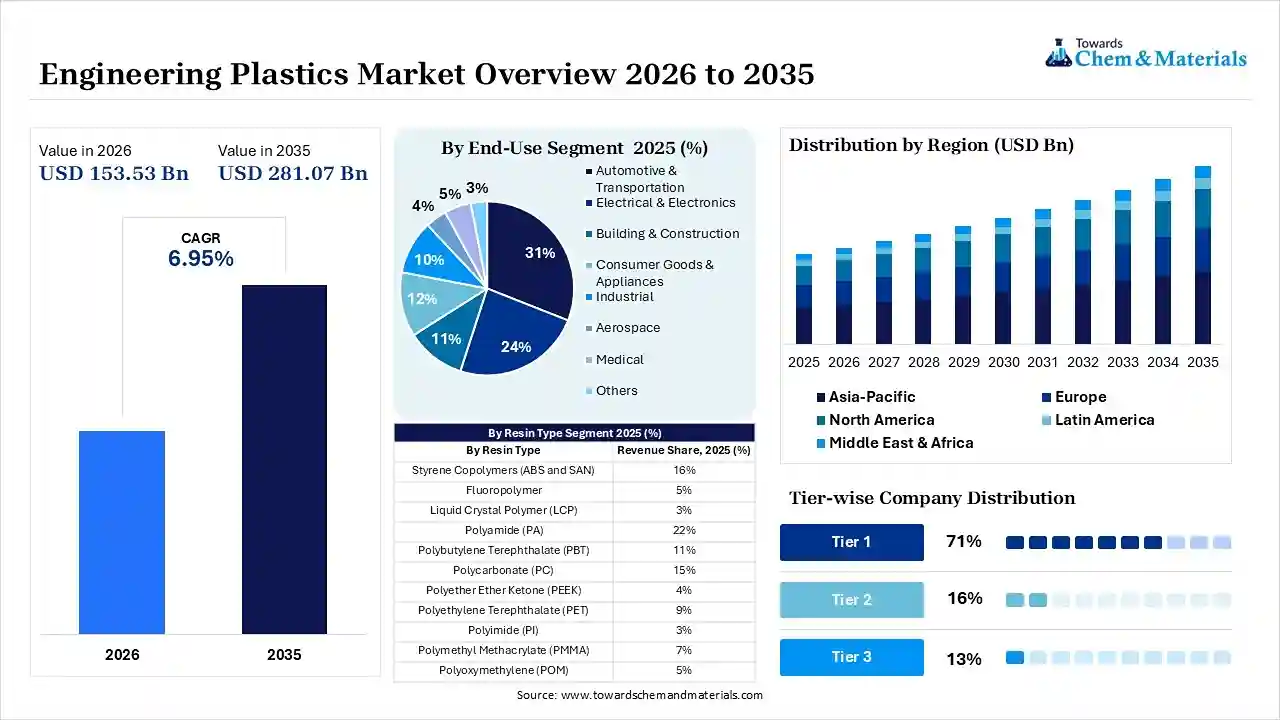
The greater global demand for high-performance yet lightweight materials has presented new business models for forward-thinking manufacturers in recent years. Moreover, the consumers across the globe are actively preferring the materials that have in-built chemical stability, heat resistance, and electrical insulation, which has enabled backward and forward integration for manufacturers these days. Also, the heavy manufacturing regions such as the Asia Pacific and North America are leading the industry potential in the current period.
Furthermore, industries are focusing on improving product performance while reducing manufacturing costs and environmental impact. This has encouraged the use of engineering plastics as a replacement for metal parts in many applications. The automotive sector remains one of the largest consumers, as manufacturers seek lighter materials that help improve fuel efficiency and electric vehicle performance.
The leading manufacturers are investing in recycling technologies and sustainable polymer solutions to meet changing environmental requirements, which supports the industry in the competitive market.
The companies are increasing production capacities to support rising demand from electric vehicles, electronics, and industrial manufacturing sectors. Moreover, businesses are investing in research and development programs to create next-generation engineering plastics with enhanced heat resistance, strength, and durability, helping them serve high-performance applications more effectively.
The manufacturers are highly investing in regional production facilities to strengthen supply chain efficiency & reduce delivery times. In recent years, companies have recognized the importance of manufacturing closer to end-use industries such as automotive, electronics, healthcare, and industrial equipment.
| Report Attributes | Details |
| Market Size and Volume in 2026 | USD 153.53 Billion / 43.24 Million Tons |
| Revenue Forecast in 2035 | USD 281.07 Billion / 72.13 Million Tons |
| Growth Rate | CAGR 6.95% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Resin Type, By End-Use, By Region |
| Key Companies Profiled | BASF, Sabic, Covestro, Evonik Industries, Arkema, Mitsubishi Chemical, Teijin Limited, Lanxess, Asahi Kasei, RadiciGroup, LG Chem |
The industry is observing a movement toward sustainable high-performance materials as per the recent industry survey. Also, manufacturers are no longer focusing only on strength and durability but are also working to reduce environmental impact. New developments include recycled engineering plastics, bio-based polymers, and materials produced using lower-carbon manufacturing processes. At the same time, digital material design and advanced compounding technologies are helping companies create plastics with better heat resistance, flame retardancy, and mechanical properties.
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | EPA (Environmental Protection Agency) | TSCA Chemical Restrictions: Managed under 40 CFR Part 751. This section outlaws or heavily restricts persistent, bioaccumulative, and toxic (PBT) chemical additives used to make industrial plastics flame-retardant. | Halogenated Additive Phase-outs: Eliminating legacy brominated flame retardants from electronic plastic housings due to environmental accumulation risks. |
| Europe | ECHA (European Chemicals Agency) | RoHS Electronics Mandate: Enforced through Directive 2011/65/EU, Annex II. This law bans specific heavy metals and chemical stabilizers from being blended into structural plastics used in appliances. | Eliminating SVHCs: Removing Substances of Very High Concern from high-temperature polymer formulations to protect public health. |
| China | SAMR (State Administration for Market Regulation) | China RoHS Framework: Managed under the Management Methods for the Restriction of Hazardous Substances in Electrical Products. This framework targets and caps heavy metals in consumer plastics. | Heavy Metal Bans: Forcing compounders to replace toxic lead and cadmium stabilizers with eco-friendly zinc or calcium alternatives. |
Huge Industrial Demand and Lightweight Material Deals
The growing demand for lightweight and high-performance materials across multiple industries has opened profitable avenues for manufacturers in recent years. Also, automotive manufacturers are increasingly replacing metal components with engineering plastics to improve fuel efficiency and electric vehicle performance. Similarly, electronics companies are using these materials because of their excellent electrical insulation, durability, and heat resistance. In recent years, industrial manufacturers have also adopted engineering plastics to reduce production costs and improve product lifespan.
Production Cost Barriers Impact
The volatility of raw material prices is likely to hinder the industry's growth during the project time. Most engineering plastics are produced from petrochemical feedstocks, making production costs highly sensitive to fluctuations in crude oil and natural gas prices. Furthermore, engineering plastics are generally more expensive than conventional plastics, which can limit adoption in price-sensitive applications.
Opportunities in Advanced Polymers
The expansion of electric vehicles, renewable energy systems, and sustainable manufacturing is anticipated to unlock new business opportunities for producers during the forecast period. Also, the increasing focus on reducing carbon emissions is encouraging industries to adopt lightweight materials that improve energy efficiency. Furthermore, the development of recyclable and bio-based engineering plastics is creating new growth avenues for manufacturers. Demand for advanced materials is also increasing in healthcare devices, semiconductor production, and industrial automation systems.
The polyamide (PA) segment dominated the market with 22% share in 2025, as it offers an excellent combination of strength, durability, wear resistance, and thermal stability. These properties make it suitable for demanding applications in automotive, industrial machinery, electrical systems, and consumer products. Polyamide materials can withstand mechanical stress while maintaining long service life, making them a preferred choice for manufacturers. Furthermore, the material provides good chemical resistance and processing flexibility, allowing its use in a wide range of applications.
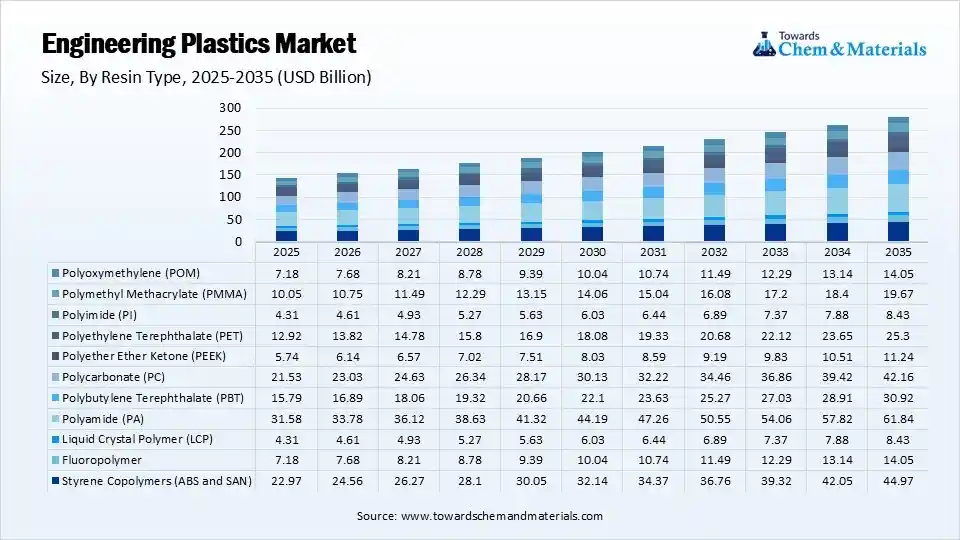 The polyimide (PI) segment held the 3% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 8.30% in the forecast period, owing to increasing demand from electric vehicles, advanced electronics, and industrial automation. Manufacturers are developing enhanced polyamide grades with improved thermal performance, flame resistance, and sustainability characteristics. Furthermore, the material's lightweight nature supports energy efficiency goals across transportation and industrial applications.
Engineering Plastics Market Share,By Resin Type, 2025 (%)
| By Resin Type | Revenue Share, 2025 (%) |
| Styrene Copolymers (ABS and SAN) | 16% |
| Fluoropolymer | 5% |
| Liquid Crystal Polymer (LCP) | 3% |
| Polyamide (PA) | 22% |
| Polybutylene Terephthalate (PBT) | 11% |
| Polycarbonate (PC) | 15% |
| Polyether Ether Ketone (PEEK) | 4% |
| Polyethylene Terephthalate (PET) | 9% |
| Polyimide (PI) | 3% |
| Polymethyl Methacrylate (PMMA) | 7% |
| Polyoxymethylene (POM) | 5% |
The automotive & transportation segment dominated the market with 31% share in 2025, due to producers are heavily relying on lightweight materials to boost vehicle efficiency and reduce emissions. Engineering plastics are widely used in engine components, fuel systems, interiors, electrical systems, and structural parts. These materials provide excellent strength while reducing overall vehicle weight. Furthermore, the growing production of passenger vehicles and commercial vehicles has supported strong demand for engineering plastics.
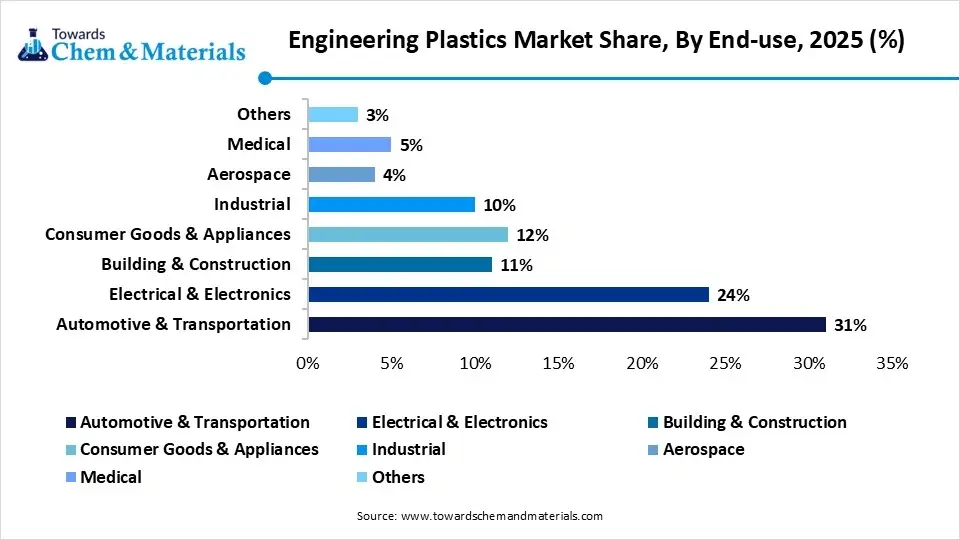 The electrical & electronics segment held the 24% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.80% in the forecast period, owing to increasing demand for smart devices, semiconductors, data centers, and advanced communication systems. Engineering plastics provide excellent electrical insulation, flame resistance, and heat management capabilities, making them highly suitable for electronic applications. Furthermore, the growing adoption of artificial intelligence, 5G infrastructure, and connected devices is creating additional demand for advanced polymer materials.
Engineering Plastics Market Share,By End-use, 2025 (%)
| By End-use | Revenue Share, 2025 (%) |
| Automotive & Transportation | 31% |
| Electrical & Electronics | 24% |
| Building & Construction | 11% |
| Consumer Goods & Appliances | 12% |
| Industrial | 10% |
| Aerospace | 4% |
| Medical | 5% |
| Others | 3% |
How will Asia Pacific Dominate the Engineering Plastics Market in 2025?
The Asia Pacific engineering plastics market size was estimated at USD 58.86 billion in 2025 and is projected to reach USD 116.64 billion by 2035, growing at a CAGR of 7.08% from 2026 to 2035.Asia Pacific dominated the market with a share of 41% in 2025, due to it being considered the world's largest manufacturing hub for automotive, electronics, industrial equipment, and consumer products. Countries across the region benefit from strong industrial infrastructure, large production capacities, and growing domestic demand. Furthermore, increasing investments in electric vehicles, renewable energy, and advanced manufacturing technologies continue to support market expansion.
China
Japan
Engineering Plastics Market Evaluation in North America
The North America engineering plastics market size was estimated at USD 31.58 billion in 2025 and is projected to reach USD 61.84 billion by 2035, growing at a CAGR of 6.95% from 2026 to 2035.North America is notably growing with 22% market share in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 8% in the forecast period, owing to growing investments in electric vehicles, aerospace, advanced manufacturing, & semiconductor sector. The region is also focusing on sustainable materials, recycling technologies, and domestic manufacturing expansion. The increasing government support for technology innovation and industrial development is creating favorable market conditions. Moreover, the growing demand for high-performance materials in healthcare, defense, and electronics sectors is also supporting expansion.
United States
Canada
Europe Engineering Plastics Industry Conditions
The Europe engineering plastics market size was estimated at USD 34.45 billion in 2025 and is projected to reach USD 68.86 billion by 2035, growing at a CAGR of 7.17% from 2026 to 2035.Europe held a 24% market share in 2025, owing to strong demand for sustainable materials, electric vehicles, and advanced manufacturing technologies. Furthermore, the region's strong industrial base and emphasis on advanced engineering continue to support demand for high-performance plastics. Growing investments in industrial automation and next-generation manufacturing technologies are also creating opportunities for engineering plastics suppliers.
Germany
Italy
Engineering Plastics Market Survey in Latin America
The Latin America engineering plastics market size was estimated at USD 8.61 billion in 2025 and is projected to reach USD 16.86 billion by 2035, growing at a CAGR of 6.95% from 2026 to 2035.Latin America held the 6% market share in 2025 due to manufacturers increasingly investing in local production capabilities to serve regional markets. Rising industrial activity and expanding consumer goods production are supporting demand for engineering plastics. Furthermore, companies are modernizing manufacturing operations to improve productivity and competitiveness. These developments are helping create a stronger industrial base and increasing the use of high-performance polymer materials across multiple sectors.
 Brazil
Argentina
Middle East and Africa Engineering Plastics Sector Observation
The Middle East and Africa engineering plastics market size was estimated at USD 10.05 billion in 2025 and is projected to reach USD 19.67 billion by 2035, growing at a CAGR of 6.95% from 2026 to 2035.The Middle East and Africa held the 7% market share in 2025, akin to countries are investing in industrial diversification and downstream manufacturing activities. Governments are encouraging the development of local production industries to reduce reliance on imports. Furthermore, infrastructure expansion and urban development projects are increasing the demand for engineering plastics across multiple applications. These efforts are creating long-term growth opportunities throughout the region.
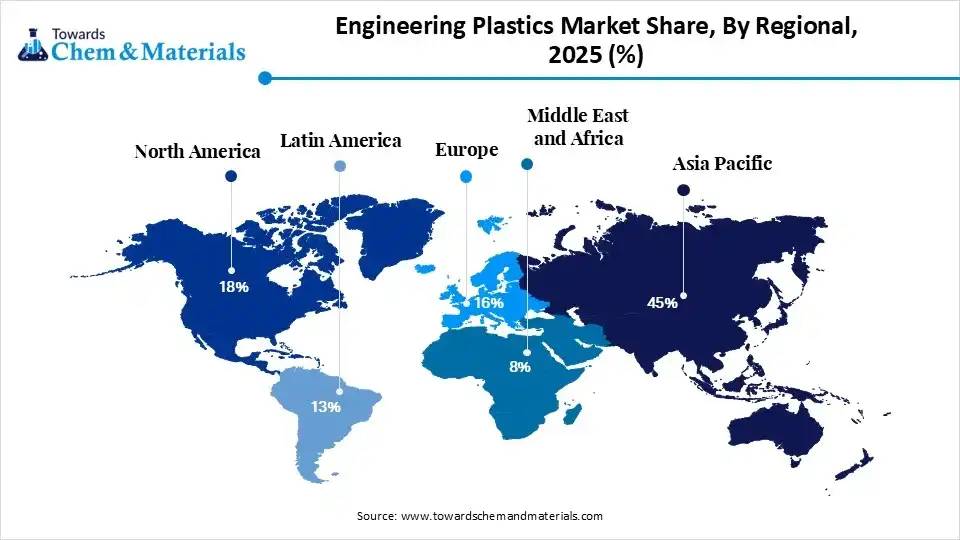
Engineering Plastics Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| Asia-Pacific | 45% |
| North America | 18% |
| Europe | 16% |
| Latin America | 13% |
| Middle East & Africa | 8% |
Saudi Arabia
UAE
The global engineering plastics market is highly competitive, with leading companies focusing on product innovation, sustainability initiatives, production expansion, and strategic partnerships to strengthen their market positions.
| Company | Company Type/Position | Major Headquarters | Geographic Presence | Offerings | Key Strength |
| BASF | Global Chemical Giant | Ludwigshafen, Germany | Massive industrial operations across Europe, the Americas, and the Asia-Pacific. | Ultramid nylon resins, Ultradur PBT, and high-performance polyurethanes for manufacturing. | Unmatched chemical production capacity and a vast portfolio of specialized polymer formulations. |
| Sabic | Thermoplastic Innovator | Riyadh, Saudi Arabia | Extensive sales network and manufacturing plants operating in over 50 nations. | Lexan polycarbonate sheets, Noryl modified PPE resins, and high-heat Ultem PEI plastics | Industry-leading expertise in developing ultra-tough, heat-resistant polymers for aerospace and electronics.. |
| Covestro | Polycarbonate Specialist | Leverkusen, Germany | Strong production footprint across Europe, North America, and major Asian industrial hubs. | Makrolon high-tech polycarbonates, raw coating materials, and specialized polymer blends. | World-class manufacturing of crystal-clear, impact-resistant plastics used in automotive engineering. |
By Resin Type
By End-Use
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo