
Liquid Waste Management Market Size, Share, Trends, and Forecast 2026–2035.
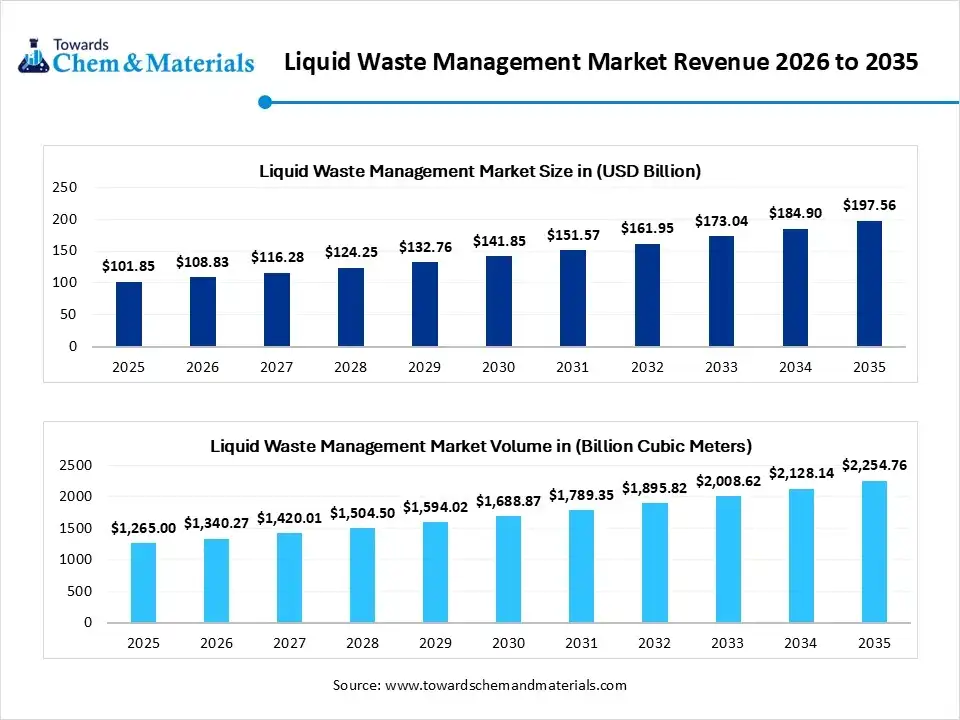
The global liquid waste management market size was estimated at USD 101.85 billion in 2025 and is expected to be worth around USD 197.56 billion by 2035, growing at a CAGR of 6.85% from 2026 to 2035. In terms of volume, the liquid waste management industry is projected to grow from 1,265.00 billion cubic meters in 2025 to 2,254.76 billion cubic meters by 2035, exhibiting a compound annual growth rate (CAGR) of 5.95% over the forecast period from 2026 to 2035. Asia Pacific dominated the liquid waste management market with a market share of 30% of the global market in 2025. The global shift towards sustainability and eco-friendly manufacturing practices has fueled the industrys growth in recent years.
Market Highlights
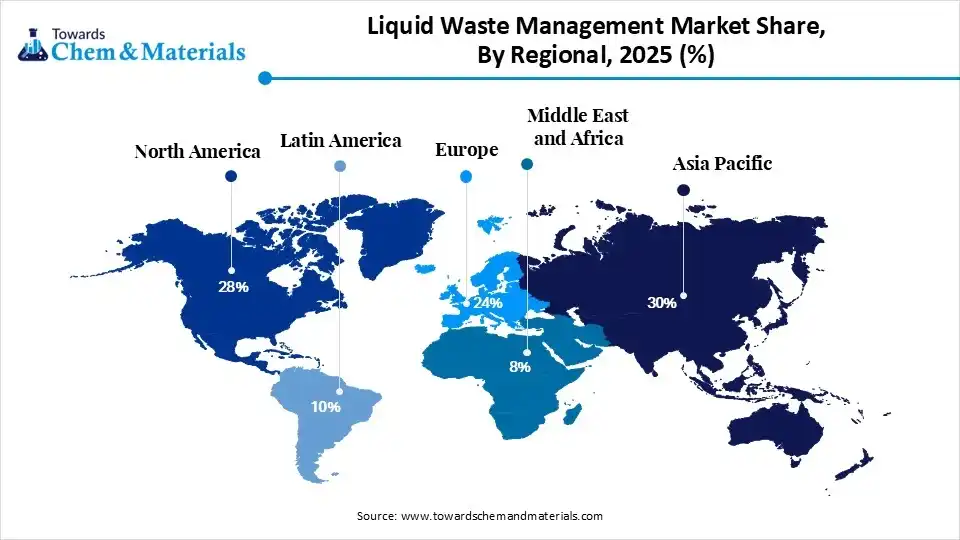
- By region, Asia Pacific dominated the market with a share of 30% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 7.80% in the forecast period.
- By region, North America is notably growing with 28% market share in 2025.
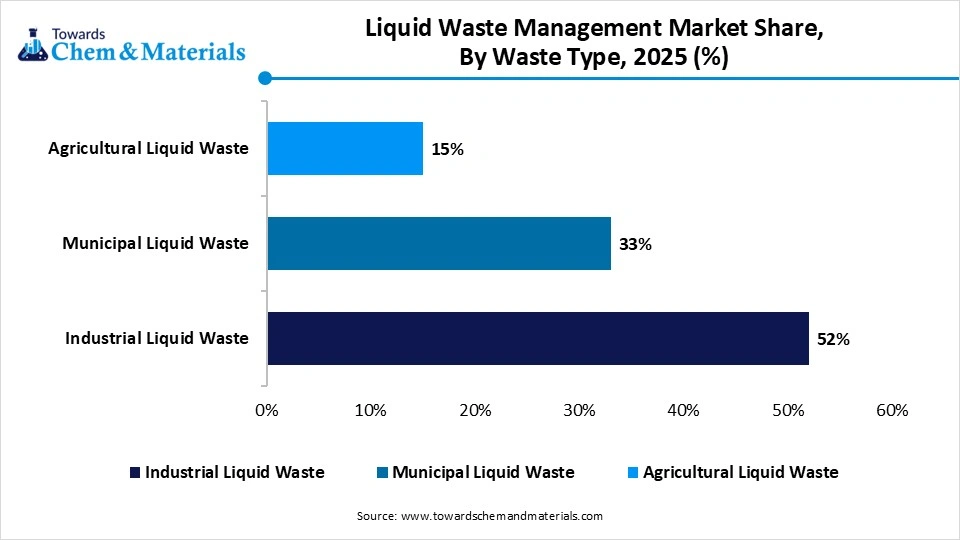
- By waste type, the industrial liquid waste segment dominated the market with a 52% share in 2025, growing at a CAGR of 6.40% from 2026 to 2035.
- By waste type, the municipal liquid waste segment held the 33% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.20% in the forecast period.
- By service type, the treatment services segment dominated the market with 38% share in 2025 and is expected to be the fastest-growing segment in the market, with a CAGR of 7.10% in the forecast period.
- By treatment method, the biological treatment segment dominated the market with a 28% share in 2025, growing at a CAGR of 6.80% from 2026 to 2035.
- By treatment method, the advanced treatment segment held the 22% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.60% in the forecast period.
- By end-use industry, the industrial segment dominated the market with a 48% share in 2025, growing at a CAGR of 6.50% from 2026 to 2035.
- By end-use industry, the municipal segment held the 30% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.30% in the forecast period in 2025.
- By source, the point-source segment dominated the market with a 62% share in 2025, growing at a CAGR of 6.30% from 2026 to 2035.
- By source, the non-point source segment held the 38% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.00% in the forecast period.
Liquid Waste Management Becoming a Global Priority Sector
The process of recycling, collecting, treating, and safely disposing of the liquid waste, which is mainly generated from hospitals, industries, households, commercial buildings, and municipal systems, is known as liquid waste management. Also, the heavy shift towards sustainability and ecologically friendly manufacturing has created profitable pathways for the industry in recent years, where several industries are seen following stricter waste management approaches in the current period. Furthermore, the liquid waste industry has gained overall attention across the world, where dense industrial regions like the Asia Pacific and Europe have observed leading industry potential nowadays.
The industry has grown steadily owing to industries and cities producing larger volumes of wastewater every year. Also, the rapid industrialization, urban population growth, and stricter environmental regulations are increasing the demand for advanced treatment systems across many countries. Industries such as chemicals, pharmaceuticals, food processing, oil & gas, textiles, mining, and manufacturing are among the major contributors to liquid waste generation.
Moreover, the governments and environmental agencies are also focusing more on wastewater recycling and sustainable disposal methods. Many companies are now investing in treatment plants that can recover water and valuable materials from waste streams instead of simply disposing of them, which actively supports the greater expansion of the industry across the globe in the current era.
Recent Market Trends:
- The heavy expansion of the smaller treatment plant establishment locally has enhanced market participation for producers in recent years. Also, the larger cities have been establishing these smaller plants near the waste sources in the past few years.
- The greater focus on risk control of the liquid has boosted the revenue potential across the manufacturing landscape in the current period. The earlier the treatment is mainly focused on removing only dirt, visible pollution, and smell, but the industries are now focusing on removing toxic chemicals, microplastics, and medical residues.
- The demand for the invisible and silent wastewater systems is expected to enable high return ventures for the manufacturers during the coming years. Also, the major factories and industries are seeking advanced systems as per the recent industry survey.
Intelligent Treatment Plants Redefining Water Management
The industry has been observing movement from fixed treatment systems to adaptive intelligent treatment systems in the current period. Also, the traditional plants work in the same way every day, even if wastewater quality changes. But future systems will automatically adjust treatment methods depending on incoming waste conditions. Smart sensors, machine learning, and automated chemical balancing will help systems make decisions in real time.
Supply Chain Analysis of the Liquid Waste Management Market:
Distribution to Industrial Users
- Industrial distribution of liquid waste management centers on a seamless cradle-to-grave logistics chain. Specialized providers deploy vacuum tankers and automated piping systems to extract hazardous effluents directly from manufacturing sites.
- These fluids are then routed to high-capacity facilities where advanced purification restores water quality, ensuring businesses achieve regulatory compliance and environmental sustainability.
- Key players: Veolia and Clean Harbors
Chemical Synthesis and Processing
- Liquid waste processing utilizes chemical synthesis to rearrange molecular structures, effectively neutralizing toxicity.
- By introducing specific reagents, facilities trigger precipitation and oxidation cycles that isolate heavy metals and degrade organic pollutants. This scientific approach converts volatile industrial runoff into purified water or reclaimed chemical components, preventing environmental contamination through rigorous molecular stabilization.
- Key Players: Dow Chemical and Xylem Inc
Regulatory Compliance and Safety Monitoring
- Strict legal protocols govern the handling of liquid effluents to prevent toxic seepage into public ecosystems.
- Compliance relies on rigorous documentation and biological assessments, while safety monitoring employs automated sensors to track chemical fluctuations.
- This dual approach ensures that industrial discharge remains within safe limits, mitigating environmental liability and protecting local communities.
- Key Agencies: EPA and SGS
Liquid Waste Management Market Regulatory Landscape: Regulations
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Environmental Protection Agency (EPA) | Resource Conservation and Recovery Act (RCRA). | Preventing subsurface leakage into aquifers and enforcing strict manifesting (tracking) of every gallon from generation to final destruction |
| Europe | European Commission (EC) |
Waste Framework Directive (Directive 2008/98/EC) | Prioritizing the "Waste Hierarchy" (recovery over disposal) and implementing the Polluter Pays Principle to fund advanced filtration infrastructure. |
| China | Ministry of Ecology and Environment (MEE) | Law on the Prevention and Control of Water Pollution | Rapidly scaling Zero Liquid Discharge (ZLD) technologies in industrial hubs and integrating real-time digital monitoring for factory outflows |
Market Dynamics
Driver
Rising Freshwater Costs Boosting Recycling Demand
Growing water pressure across cities and industries is driving the strategic transformation and sectoral scalability. Also, freshwater is becoming expensive, while wastewater generation is increasing every year. Governments are also creating stricter environmental rules, forcing industries and municipalities to treat wastewater properly before disposal. At the same time, companies are realizing that untreated liquid waste can damage their brand image, create legal risks, and increase operational costs. Moreover, the water reuse demand is increasing. Many industries now recycle wastewater because buying fresh water repeatedly is becoming costly.
Restraint
Wastewater Management Facing Efficiency Pressure
High operational complexity is anticipated to hinder the industry growth during the forecast period. Also, many treatment systems need skilled workers, continuous monitoring, expensive maintenance, and regular chemical usage. Smaller industries and municipalities often struggle to manage these costs properly. Another challenge is inconsistent wastewater quality nowadays. Different industries generate different types of liquid waste, making treatment difficult and expensive.
Opportunity
From Waste Disposal to Resource Recovery
The water reuse and resource recovery are expected to create lucrative opportunities for the industry players during the projected period. Also, the companies are slowly understanding that wastewater can generate value instead of only creating disposal problems. Treated wastewater can be reused for cooking, cleaning, irrigation, and industrial operations. Valuable materials like salts, nutrients, chemicals, and biogas can also be recovered from liquid waste streams. Furthermore, the smart monitoring technology is actively presenting advantages in the industry nowadays. Industries want systems that reduce manpower and improve efficiency using automation and AI-based monitoring.
Segmental Insights
Waste Type Insights
Liquid Waste Management Market Share, By Waste Type, 2025 (%)
| By Waste Type | Revenue Share, 2025 (%) |
| Industrial Liquid Waste | 52% |
| Municipal Liquid Waste | 33% |
| Agricultural Liquid Waste | 15% |
The industrial liquid waste segment dominated the market with 52% share in 2025, as factories generate highly contaminated wastewater that requires complex treatment. Industries like chemicals, pharmaceuticals, textiles, food processing, oil and gas, and manufacturing produce large volumes of liquid waste every day.
The municipal liquid waste segment held the 33% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.20% in the forecast period, owing to the rapid growth of the urban population. Cities are producing massive amounts of sewage every day due to rising residential housing, commercial buildings, and urban lifestyle changes. Governments are investing heavily in sewage infrastructure because poor wastewater management directly affects public health and urban living quality.
The agriculture liquid waste segment held the 15% market share in 2025, owing to modern farming is becoming more intensive and commercialized. Large farms, dairy operations, poultry farms, and food production facilities generate huge amounts of liquid waste containing fertilizers, pesticides, animal waste, and organic matter.
Service Type Insights
The treatment services segment dominated the market with 38% share in 2025 and is expected to be the fastest-growing segment in the market, with a CAGR of 7.10% in the forecast period, as liquid waste cannot simply transported or collected without proper processing. Most wastewater contains harmful pollutants that must be treated before reuse or disposal. Municipalities and Industries spend heavily on treatment because environmental laws majorly focus on discharge quality standards.
The collection services segment held the 24% market share in 2025, due to wastewater generation points are increasing rapidly. Urban expansion, industrial growth, hospitals, commercial buildings, and remote facilities all need organized liquid waste transportation systems. Many regions still lack permanent pipeline infrastructure, increasing dependence on tanker-based collection services.
The recycling & disposable services segment held the 22% market share in 2025, owing to companies wanting to reduce freshwater usage and landfill dependency. Industries are realizing that treated wastewater can be reused for cooling, cleaning, irrigation, and manufacturing operations. Recycling reduces operational costs and supports sustainability goals.
Treatment Method Insights
Liquid Waste Management Market Share, By Treatment Method, 2025 (%)
| By Treatment Method | Revenue Share, 2025 (%) |
| Physical Treatment | 26% |
| Chemical Treatment | 24% |
| Biological Treatment | 28% |
| Advanced Treatment | 22% |
The biological treatment segment dominated the market with 28% share in 2025, as it is one of the most cost-effective and natural ways to treat wastewater. This method uses microorganisms to break down organic pollutants inside sewage and industrial wastewater.
The advanced treatment segment held the 22% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.60% in the forecast period, owing to the wastewater pollution becoming more complex. Traditional systems cannot fully remove pharmaceutical residue, microplastics, PFAS compounds, toxic chemicals, and dissolved contaminants. Future regulations may require much cleaner discharge quality and higher water reuse standards.
The physical treatment segment held the 26% market share in 2025, as industries want faster and simpler pre-treatment solutions. Methods like filtration, sedimentation, flotation, and screening help remove solid particles, oils, and suspended matter before advanced treatment stages begin.
End-Use Industry Insights
Liquid Waste Management Market Share, By End-Use Industry, 2025 (%)
| By End-Use Industry | Revenue Share, 2025 (%) |
| Industrial | 48% |
| Municipal | 30% |
| Commercial | 12% |
| Agriculture | 10% |
The industrial segment dominated the market with 48% share in 2025, owing to factories generating highly polluted wastewater that requires expensive treatment technologies. Industries such as pharmaceuticals, mining, chemicals, food processing, textiles, oil and gas, and manufacturing produce wastewater containing oils, heavy metals, toxic chemicals, and industrial sludge.
The municipal segment held the 30% market share in 2025 and is expected to be the fastest-growing in the market, with a projected CAGR of 7.30% from 2026 to 2035, owing to cities expanding faster than ever before. Urban populations are increasing daily, creating huge sewage management challenges. Governments are investing heavily in sewage infrastructure because wastewater directly affects public health, sanitation, and urban development.
The commercial segment held the 12% market share in 2025, owing to modern commercial buildings generating significant wastewater volumes every day. Hotels, malls, hospitals, office complexes, restaurants, airports, and educational institutions are increasingly adopting wastewater treatment systems to reduce water costs and improve sustainability.
Source Insights
Liquid Waste Management Market Share, By Source, 2025 (%)
| By Source | Revenue Share, 2025 (%) |
| Point Source | 62% |
| Non-Point Source | 38% |
The point source segment dominated the market with 62% share in 2025, owing to it comes from clearly identifiable locations such as factories, sewage plants, hospitals, and industrial facilities. These sources are easier to monitor, regulate, and control compared to scattered pollution sources.
The non-point source segment held the 38% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 7.00% in the forecast period, as environmental pollution is becoming more widespread and difficult to control. Agricultural runoff, urban stormwater, roadside drainage, and scattered chemical leakage are increasing due to rapid urbanization and climate change.
Regional Insights
How will Asia Pacific Dominate the Liquid Waste Management Market in 2025?
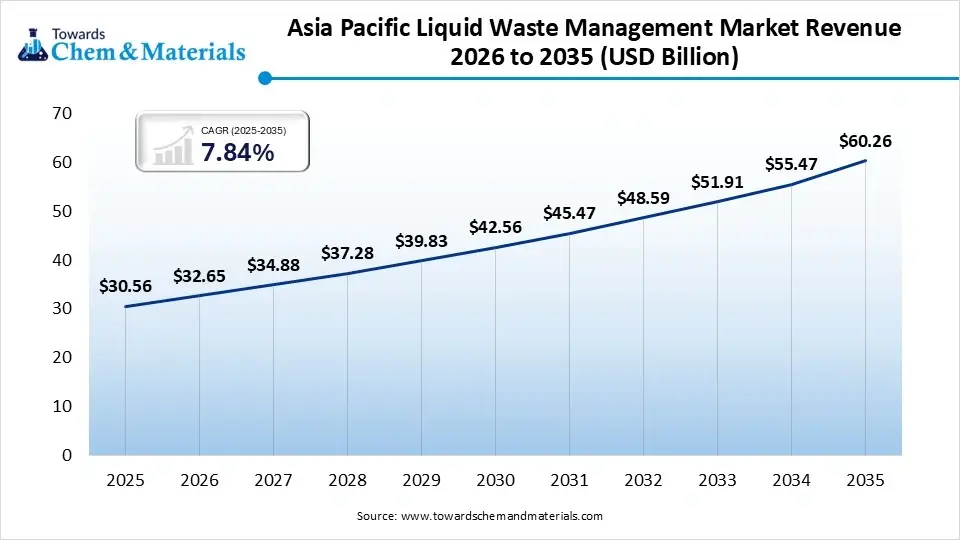
The Asia Pacific Liquid Waste Management Market size was estimated at USD 30.56 billion in 2025 and is projected to reach USD 60.26 billion by 2035, growing at a CAGR of 7.84% from 2026 to 2035.Asia Pacific dominated the market with a share of 30% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 7.80% in the forecast period, due to the region having massive population growth, rapid industrialization, and expanding urban infrastructure. Countries across Asia are generating enormous wastewater volumes from factories, residential housing, and commercial development. Governments are investing heavily in sewage treatment projects to improve sanitation and reduce pollution.
China Accelerating Smarter Sewage Systems
China maintained its dominance in the market, owing to its huge industrial base and large urban population. The country has faced serious water pollution challenges for many years, pushing the government to strengthen environmental regulations aggressively. China is investing heavily in industrial wastewater treatment, smart sewage systems, and water recycling technologies.
Liquid Waste Management Market Evaluation in North America
North America is notably growing with 28% market share in 2025, owing to industries and municipalities upgrading old wastewater infrastructure. Many treatment plants in the region were built decades ago and now require modernization. Strict environmental regulations are also increasing investment in advanced treatment technologies for removing emerging contaminants like PFAS, pharmaceutical residue, and microplastics.
Liquid Waste Management Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| North America | 28% |
| Europe | 24% |
| Asia-Pacific | 30% |
| Latin America | 10% |
| Middle East & Africa | 8% |
Rising Investment in Smart Water Systems in the United States
The United States is expected to emerge as a prominent country for the liquid waste management market in the coming years, due to country is focusing strongly on upgrading aging sewage infrastructure and improving industrial wastewater compliance. Water scarcity in some states is increasing investment in wastewater recycling and reuse projects. The market in the United States is also leading in smart water technologies, AI-based monitoring systems, and advanced filtration methods.
Recent Developments
- In February 2026, Sumitomo Electric unveiled a compact membrane treatment system. Also, this newly launched membrane system has the ability to reduce industrial waste disposal by 90% and specifically works better in waste liquids and wastewater containing oil, as per the companys claim.(Source : sumitomoelectric.com)
Top Vendors in the Liquid Waste Management Market & Their Offerings:
- Veolia Environnement S.A.: This French powerhouse leads the global shift toward ecological transformation by managing complex water and waste cycles. They specialize in reclaiming precious resources from industrial fluids and converting hazardous sludge into renewable energy. By integrating circular economy principles, Veolia helps cities and factories significantly reduce their environmental footprint through smart technology.
- Suez S.A.: Suez focuses on revolutionary water management and recovery solutions, prioritizing the protection of global aqueous resources. They utilize advanced digital monitoring and chemical-physical treatments to purify industrial effluents and safeguard drinking water supplies. Their commitment to innovation drives the development of sustainable infrastructure that turns liquid waste into valuable secondary materials.
- Waste Management, Inc. (WM): As North America’s environmental services leader, WM operates a massive network of collection and processing facilities. They excel in the safe containment and stabilization of industrial liquids, utilizing cutting-edge leak prevention and environmental monitoring systems. Their strategy emphasizes landfill diversion and transforming captured waste streams into sustainable power for local communities.
- Republic Services, Inc.
- Clean Harbors, Inc.
- GFL Environmental Inc.
- Waste Connections, Inc.
- Stericycle, Inc.
Segments Covered in the Report
By Waste Type
- Industrial Liquid Waste
- Chemical Waste
- Oil & Gas Wastewater
- Heavy Metal Waste
- Hazardous Liquid Waste
- Municipal Liquid Waste
- Sewage
- Greywater
- Stormwater
- Agricultural Liquid Waste
- Livestock Waste
- Irrigation Runoff
- Pesticide & Fertilizer Waste
By Service Type
- Collection Services
- Tanker Collection
- Pipeline Collection
- Transportation Services
- Treatment Services
- Physical Treatment
- Chemical Treatment
- Biological Treatment
- Recycling & Disposal Services
- Resource Recovery
- Wastewater Reuse
- Safe Disposal
By Treatment Method
- Physical Treatment
- Filtration
- Sedimentation
- Chemical Treatment
- Coagulation & Flocculation
- Neutralization
- Biological Treatment
- Aerobic Treatment
- Anaerobic Treatment
- Advanced Treatment
- Membrane Filtration
- Reverse Osmosi
- UV & Ozone Treatment
By End-Use Industry
- Industrial
- Manufacturing
- Oil & Gas
- Chemicals
- Power Generation
- Municipal
- Commercial
- Healthcare
- Hospitality
- Retail
- Agriculture
By Source
- Point Source
- Industrial Discharge Points
- Sewage Treatment Plants
- Non-Point Source
- Agricultural Runoff
- Urban Runoff
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.