
Automotive Tinting Film Market Size, Competitive Landscape Analysis Report 2035
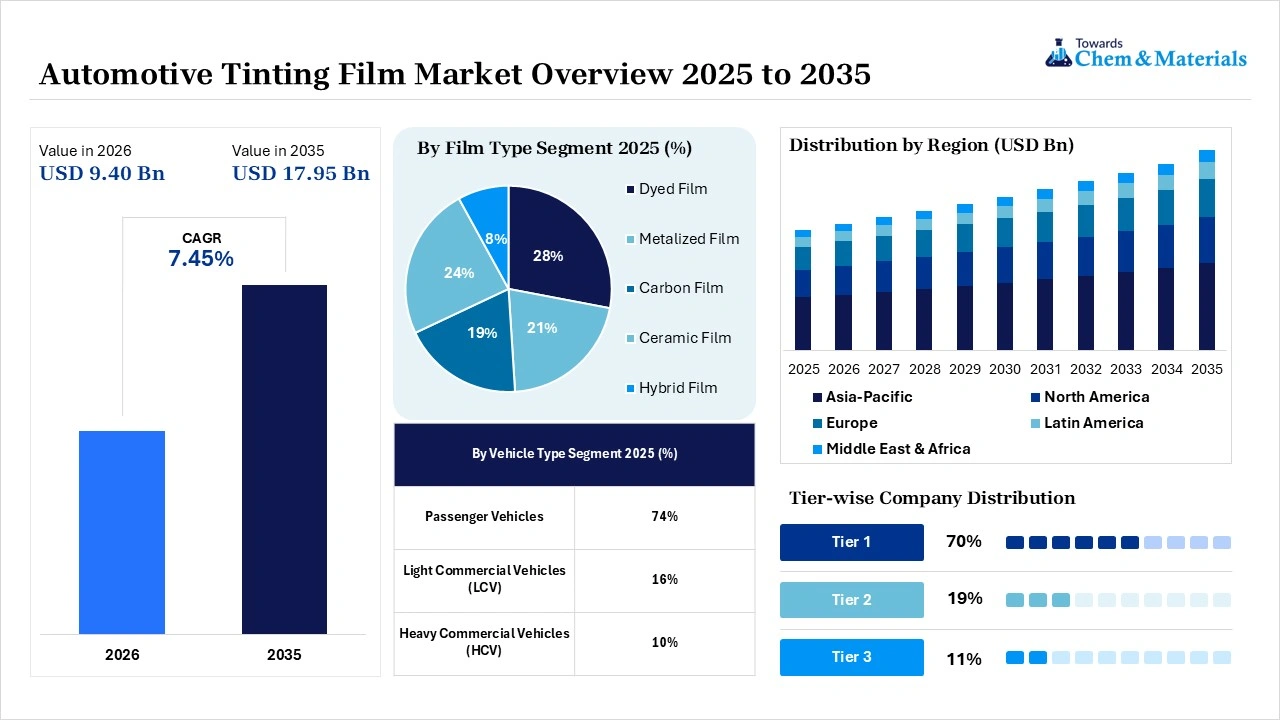
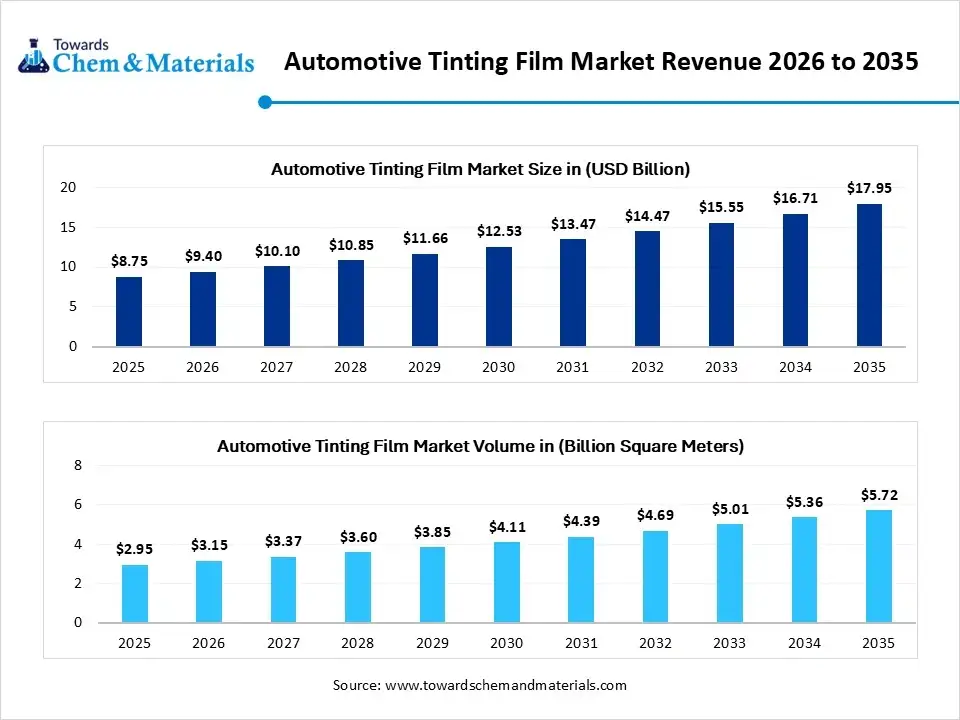
The automotive tinting film market size was valued at USD 8.75 billion in 2025, is estimated to reach USD 9.40 billion in 2026, and is projected to reach USD 17.95 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 7.45% over the forecast period from 2026 to 2035.Asia Pacific dominated the automotive tinting film market with the largest revenue share of 39% in 2025 and is expected to grow at the fastest CAGR of 7.59% during the forecast period. In terms of volume, the automotive tinting film market is projected to grow from 2.95 million tons in 2025 to 5.72 million tons by 2035. growing at a CAGR of 6.85% from 2026 to 2035. Increasing vehicle personalization trends and a surge in EV adoption are the key factors driving market growth. Also, a growing desire for improved personal privacy coupled with increasing consumer awareness regarding the dangers of UV radiation can fuel market growth further. Moreover, the wide growth of aftermarket services in developing countries can lead to market growth soon.
Market Highlights
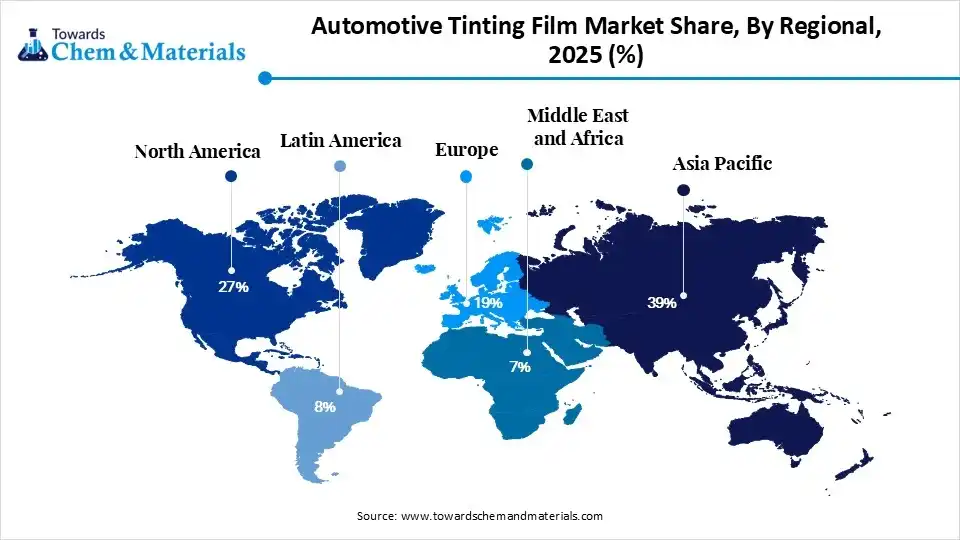
- By region, Asia Pacific dominated the market with the largest share of 39% in 2025. The dominance of the region can be attributed to the rising disposable incomes, increasing urbanization, and a growing fleet of passenger vehicles.
- By region, North America held the market share of 27% in 2025 and is expected to grow at the fastest CAGR of 8.00% over the forecast period. The growth of the region can be credited to substantial consumer investment in vehicle customization.
- By film type, the dyed film segment dominated the market with the largest share of 28% in 2025. Dyed window tints are produced by applying a layer of dye to film, which sits between the adhesive layer and a protective topcoat.
- By film type, the ceramic film segment held the market share of 24% in 2025 and is expected to grow at the fastest CAGR of 8.9% over the forecast period. Ceramic films represent a high-performance, premium tire segment.
- By vehicle type, the passenger vehicles segment dominated the market with the largest share of 74% in 2025 and is expected to grow at the fastest CAGR of 7.00% over the forecast period. This segment depends on aftermarket and OEM applications to enhance interior preservation.
- By application, the side windows segment dominated the market with the largest share of 43% in 2025. These are mainly used to block harmful UV rays, regulate interior cabin temperatures to enhance passenger comfort, and prevent interior upholstery from fading.
- By application, the front windshield segment held the market share of 11% in 2025 and is expected to grow at the fastest CAGR of 8.2% over the forecast period. The automotive front windshield serves as the primary entry point for solar radiation.
- By visible light transmission (VLT), the 20%–35% segment held a market share of 39% in 2025. This category of premium window film constitutes a darker tint tier, permitting between 20% and 35% of ambient light to penetrate the glass.
- By visible light transmission (VLT), the above 50 segments held the market share of 15% in 2025 and are expected to grow at the fastest CAGR of 8.0% over the forecast period. This segment primarily consists of legal, light-tinted window films.
- By technology, the non-reflective films segment dominated the market with the largest share of 36% in 2025. These films utilize advanced dyed, carbon, and nanoceramic formulations to minimize solar heat and glare without producing a metallic or reflective finish.
- By technology, the nano-ceramic films segment held the market share of 29% in 2025 and was expected to grow at the fastest CAGR of 9.1% over the projected period. These films have become the preferred premium choice due to their superior performance.
- By distribution channel, the aftermarket segment dominated the market with the largest share of 73% in 2025. The aftermarket offers a diverse array of advanced film technologies, including dyed, metalized, carbon, and high-performance ceramic films.
- By distribution channel, the OEM segment held the market share of 27% in 2025 and is expected to grow at the fastest CAGR of 7.10% during the study period. Vehicle manufacturers are integrating advanced window films directly during assembly to boost energy efficiency and cabin comfort.
Quick Stats at a Glance
- Market Estimated Size (2025): USD 8.75 Billion | CAGR (2026–2035): 7.45%
- Market Projected Size (2035): USD 17.95 Billion
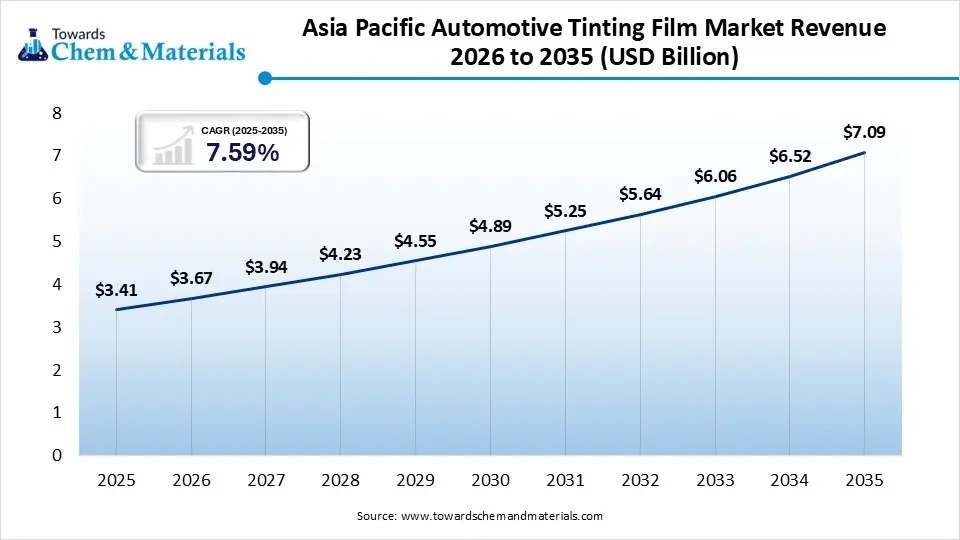
- Asia Pacific: largest Market Revenue Share of 39% in 2025|USD 3.41 Billion
- Market Estimated Volume (2025): 2.95 Billion Square Meters | Volume CAGR (2026–2035): 6.85%
- Market Projected Volume (2035): 5.72 Billion Square Meters
- Market Pricing (2025):
- Average Manufacturing Price: USD 1.99/Sq. Ft.
- Average Selling Price: USD 3.19/Sq. Ft.
- Pricing CAGR (2026–2035): 2.35%
The market consists of sets of lucrative opportunities with major segments, underscoring the transitioning consumer preferences and technological innovations. Consumers across the globe are becoming more aware of the benefits associated with cutting-edge window films, better heat rejection, and enhanced UV protection. This move is towards high-grade tinting products, shaping a positive market trajectory.
For Instance, Garware Hi-Tech Films Limited has commenced commercial operations at its new Paint Protection Film (PPF) manufacturing facility in Waluj, Maharashtra. This ₹125 crore investment adds an annual capacity of 300 LSF. This strategic expansion follows a robust fiscal year in which the company reported a 26% increase in revenue, reaching ₹2,109 crores, and a 63% surge in profit after tax (PAT) to ₹331 crores.
High-rejection films minimize cabin heat, reducing the energy load placed on vehicle air-conditioning systems and directly extending an EV's driving range. Also, tinting laminates offers a bonding layer that holds shattered window glass together in any harmful event, minimizing injuries from flying debris.
Surged regional heatwaves drive significant aftermarket adoption in hot climates like North America, the Asia-Pacific, and the Middle East.
Global Investment Flow for Automotive Tinting Film 2026
Investment flows are largely fueled by the transition towards electric vehicle (EV) thermal management, high-performance nanoceramic films, and growing aftermarket customization in developing countries such as China and India.
JETOUR has introduced a global micro-film initiative aimed at redefining brand storytelling within the automotive industry. Driven by a consistent long-term vision, the company has achieved over 2.15 million in cumulative sales within a span of just eight years, representing a major milestone in its corporate development.
Major players are heavily investing in Asia-Pacific and European production hubs. Companies are funding the development of multilayer optical films to enhance heat rejection and electronic signal clarity.
Automotive Tinting Film Market Trends
- Increasing awareness regarding health benefits among consumers is the latest trend in the market, shaping positive market growth. This trend is especially popular in regions with high sun exposure and where the need for protective films is anticipated to rise substantially.
- In recent years, the growing need for sustainable solutions is impelling market players to develop window films that are made from recyclable materials. This trend aligns with extensive sustainability goals and shows a rising preference for products that reduce overall environmental impact.
- The ongoing technological innovations in film manufacturing are the future trend in the market driving growth. Innovations in materials science have facilitated the development of high-performance films that give superior durability, clarity, and heat rejection.
AI-Powered Predictive Formulations in Automotive Tinting Film Market
The integration of predictive, AI-driven formulations is fundamentally reshaping the market. By substituting heuristic R&D processes with advanced machine learning, manufacturers can now optimize polymer architectures, resin chemistries, and nanoparticle distributions with high precision. Furthermore, this approach reduces lengthy product development cycles.
Market Scope
| Report Atributes | Details |
| Market Size and Volume in 2026 | USD 9.40 Billion / 3.15 Million Tons |
| Revenue Forecast in 2035 | USD 17.95 Billion / 5.72 Million Tons |
| Growth Rate | CAGR 7.45% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Film Type, By Vehicle Type, By Application, By Visible Light Transmission (VLT), By Technology, By Distribution Channel, By regions |
| Key Companies Profiled | Avery Dennison Israel Ltd. (Hanita Coatings RCA Ltd.), Johnson Window Films, Inc., GLOBAL WINDOW FILMS, Madico, Inc., Saint-Gobain Performance Plastics Corporation, TWF, Armolan, NEXFIL, Solar Screen International SA, Huper Optik USA, 3M, Eastman Chemical Company, TintFit Window Films Ltd. |
Supply Chain Analysis of the Automotive Tinting Film Market
- Production & Processing:It encompasses the manufacturing, processing, distribution, and installation of thin laminate films on vehicle glass surfaces. It serves both Original Equipment Manufacturer (OEM) facilities and aftermarket sectors. It delivers ultraviolet (UV) protection, thermal insulation through infrared rejection, enhanced privacy, and shatter resistance. The foundation is generally high-grade optically clear polyester (PET).
- Avery Dennison Corporation (U.S.) - It offers a wide array of automotive window films designed for cool comfort and UV protection.
- Other Key Players: 3M Company, Eastman Chemical Company
- Quality Testing and Certification:It refers to the evaluation processes that ensure window films meet safety standards and performance benchmarks. These standards include visible light transmission limits. The benchmarks include ultraviolet and infrared blocking. This evaluation guarantees regulatory compliance. It also ensures product durability over time. It tests films against extreme heat, humidity, and bubbling or fading over time to ensure structural integrity.
- Garware Hi-Tech Films Ltd.: A prominent player providing RTO-approved sun control and automotive films.
- Other Key Players: Saint-Gobain, Avery Dennison Corporation
- Distribution to Industrial Users:It encompasses both Original Equipment Manufacturer (OEM) and aftermarket channels and constitutes a critical segment of the supply chain. In this model, manufacturers sell tinting and protective films in bulk quantity directly to automotive manufacturers, large fleet operators, commercial installers, and specialized dealerships, rather than targeting individual retail consumers. Industrial distribution generally involves offering technical specifications.
- Avery Dennison Corporation: Widely known for launching comprehensive commercial and automotive window film portfolios (like their Encore series).
- Other Key Players: Saint-Gobain,Eastman Chemical Company
Automotive Tinting Film Market’s Regulatory Landscape: Global Regulations
| Country/Region | Key Regulations |
| United States | Regulations are governed at the state level rather than federally. For example, in states like North Dakota, the front windshield must allow at least 70% VLT (only above the AS-1 line), while other side windows must allow at least 35% VLT. Other states may allow darker or lighter limits depending on local laws. |
| India | Under the Motor Vehicles Act, the Supreme Court of India enforces very strict guidelines to prevent illegal activities inside vehicles. Aftermarket tinting films are completely banned. Only factory-fitted glass is legal, which must adhere to a minimum of 70% VLT for the front and rear windshields, and 50% VLT for the side windows. |
| United Kingdom | The front windshield must legalise a minimum of 75% VLT, and the front side windows must allow at least 70% VLT. There are no legal restrictions on tinting the rear windscreen or rear side windows. |
Market Dynamics
Driver
Increasing Vehicle Security and Protection
A growing focus on vehicle security and protection is the major factor driving growth in the market. Owing to their distinct physicochemical properties, nanomaterials enhance both the structural longevity and operational safety of vehicles. In addition, capitalizing on recent technological breakthroughs, major market players are currently releasing advanced iterations of automotive window tinting films to the global market, impacting growth.
Restraint
Stringent and Varying Regulations
Regulations about how dark window tints can be, which change significantly by region, are the major factor hindering the growth of the market. These rules generally focus on Visible Light Transmission (VLT), which is the percentage of light that can pass through the window. Moreover, international legal frameworks vary widely, with some nations imposing total bans on vehicular tinting for safety and crime-prevention purposes; hence, manufacturers face severe obstacles in creating universally standardized products.
Opportunity
Growing Adoption of Nanoceramic Tinting Films
The increasing utilization of nano-ceramic tinting films, which gives better heat rejection and UV protection without compromising visibility, is the major factor creating lucrative opportunities in the market. Furthermore, these films are gaining widespread popularity because they keep vehicle cabins comfortable and protect interiors from sun damage. Since they are completely metal-free, they do not interfere with electronic device signals. Also, innovations in film technology are making DIY tint applications easier and more convenient.
Segmental Insights
Film Type Insights
The dyed film segment dominated the market with the largest share of 28% in 2025. Dyed window tints are produced by applying a layer of dye to film, which sits between the adhesive layer and a protective topcoat. These films are cost-effective and appeal more to budget-conscious consumers. In addition, the dye absorbs solar radiation to maintain a cooler cabin environment and blocks up to 99% of harmful ultraviolet (UV) radiation, mitigating interior material degradation, such as dashboard cracking and fading.
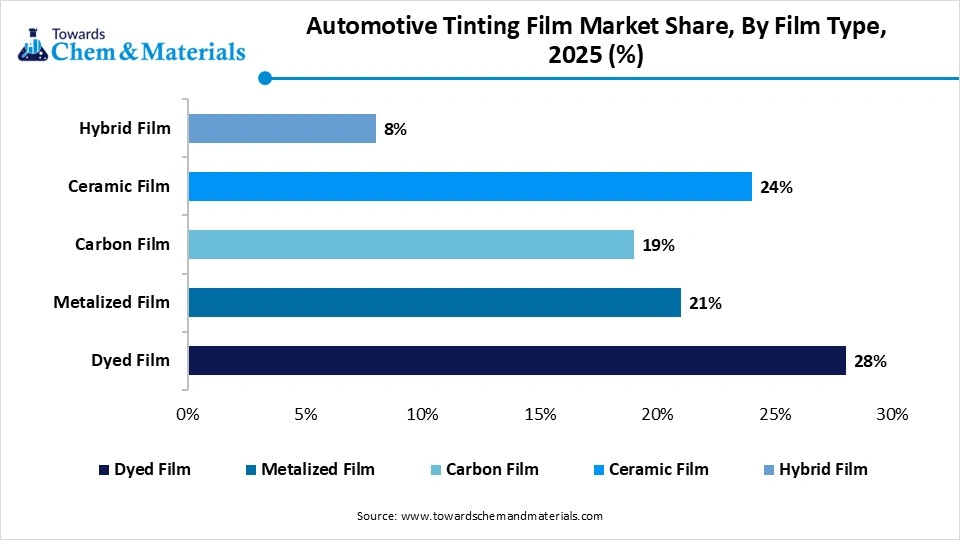 The ceramic film segment held the market share of 24% in 2025 and is expected to grow at the fastest CAGR of 8.9% over the forecast period. Ceramic films represent a high-performance, premium tire segment. Renowned for its integration of advanced nanoparticle technology, this constitutes the industry's most rapidly expanding film type. This growth is driven by its exceptional thermal insulation, non-conductive composition, and remarkable optical clarity. It gives exceptional daytime and nighttime glare reduction without needing dark shade.
Automotive Tinting Film Market Share,By Film Type, 2025 (%)
| By Film Type | Revenue Share, 2025 (%) |
| Dyed Film | 28% |
| Metalized Film | 21% |
| Carbon Film | 19% |
| Ceramic Film | 24% |
| Hybrid Film | 8% |
Vehicle Type Insights
The passenger vehicles segment dominated the market with the largest share of 74% in 2025 and is expected to grow at the fastest CAGR of 7.00% over the forecast period. This segment depends on aftermarket and OEM applications to enhance interior preservation, vehicle aesthetics, and UV protection. There is a growing consumer demand for window tinting films to minimize cabin heat and block harmful ultraviolet rays. These films serve to protect passengers from skin damage while preventing vehicle interiors, such as dashboards and seats, from cracking and fading.
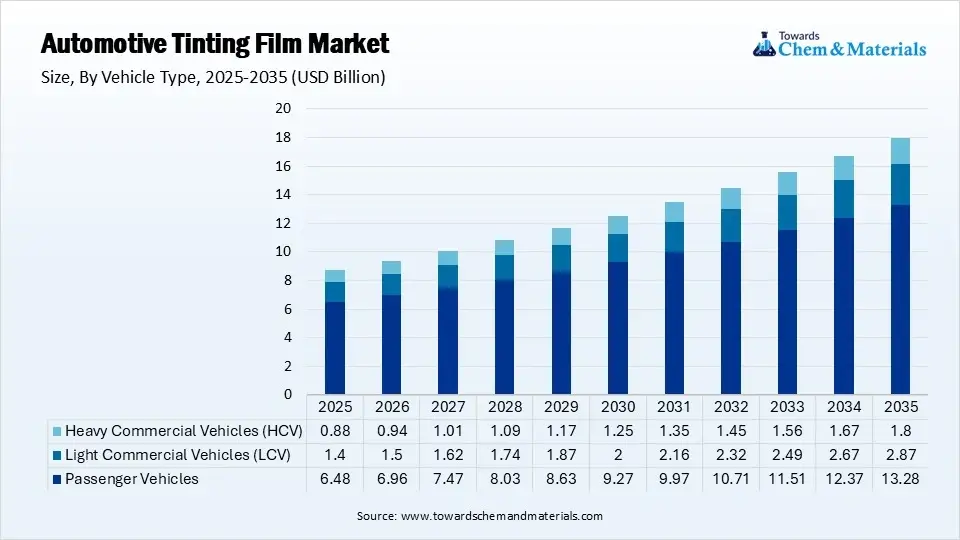
The light commercial vehicles (LCV) segment held a market share of 16% in 2025. LCVs, which include vans, pickups, and minibuses, possess robust expansion due to growing urban commercial fleets, cargo protection, and demand for heat reduction. Due to the extensive use of light commercial vehicles (LCVs) in business operations, fleet operators are increasingly selecting high-performance window films. These transparent or legally compliant tinted options maximize ultraviolet (UV) and infrared (IR) rejection while fully maintaining driver visibility.
Automotive Tinting Film Market Share,By Vehicle Type, 2025 (%)
| By Vehicle Type | Revenue Share, 2025 (%) |
| Passenger Vehicles | 74% |
| Light Commercial Vehicles (LCV) | 16% |
| Heavy Commercial Vehicles (HCV) | 10% |
Application Insights
The side windows segment dominated the market with the largest share of 43% in 2025. These are mainly used to block harmful UV rays, regulate interior cabin temperatures to enhance passenger comfort, and prevent interior upholstery from fading. Furthermore, high-end window films are frequently purchased by luxury vehicle owners to enhance aesthetic appeal and achieve a sophisticated appearance. Similarly, automotive customization enthusiasts and younger demographics represent a significant market driver for premium window tinting products. More car owners globally prefer high-quality materials like ceramic films.
The front windshield segment held the market share of 11% in 2025 and is expected to grow at the fastest CAGR of 8.2% over the forecast period. The automotive front windshield serves as the primary entry point for solar radiation. To mitigate this effect, high-performance window films, such as ceramic and carbon variants, are employed to obstruct up to 99% of harmful ultraviolet rays. In addition, windshields are made of laminated glass; adding tinting films provides an extra layer of protection. This film helps hold glass fragments together during a collision or impact.
Automotive Tinting Film Market Share,By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Side Windows | 43% |
| Rear Windshield | 24% |
| Front Windshield | 11% |
| Sunroof | 14% |
| Quarter Glass & Other Windows | 8% |
Visible Light Transmission (VLT) Insights
The 20%–35% segment held a market share of 39% in 2025. This category of premium window film constitutes a darker tint tier, permitting between 20% and 35% of ambient light to penetrate the glass. Primarily engineered for optimal heat rejection, privacy, and visual enhancement, market growth is mainly governed by local legal mandates, environmental conditions, and consumer preferences for automotive customization. Applied to the rear side windows and back windshield, films with 20% and 35% Visible Light Transmission (VLT) offer enhanced cabin climate control and privacy without significantly compromising nocturnal visibility.
The above 50 segments held the market share of 15% in 2025 and are expected to grow at the fastest CAGR of 8.0% over the forecast period. This segment primarily consists of legal, light-tinted window films. These films dominate highly regulated markets, such as India and the EU, by delivering exceptional UV and infrared heat rejection with minimal Visible Light Transmission (VLT) reduction. They are essential for preserving interior materials and minimizing air conditioning loads. These tints are designed for application on side and rear windows. They offer standard glare reduction and basic privacy while ensuring strict compliance with applicable traffic regulations.
Automotive Tinting Film Market Share,By Visible Light Transmission (VLT), 2025 (%)
| By Visible Light Transmission (VLT) | Revenue Share, 2025 (%) |
| Below 20% | 18% |
| 20%–35% | 39% |
| 35%–50% | 28% |
| Above 50% | 15% |
Technology Insights
The non-reflective films segment dominated the market with the largest share of 36% in 2025. These films utilize advanced dyed, carbon, and nanoceramic formulations to minimize solar heat and glare without producing a metallic or reflective finish. Also, they are the preferred choice for preserving vehicle electronics to ensure seamless OEM integration. These films incorporate non-conductive ceramic particles that effectively obstruct up to 85% of infrared heat and 99% of ultraviolet radiation. Furthermore, they are entirely non-reflective, highly durable, and ensure zero interference with radio, GPS, or cellular signals.
The nano-ceramic films segment held the market share of 29% in 2025 and was expected to grow at the fastest CAGR of 9.1% over the projected period. These films have become the preferred premium choice due to their superior performance. They offer advanced heat rejection and excellent ultraviolet protection. Additionally, they ensure clear signal transmission. Traditional dyed or metallic alternatives do not match these capabilities. They also block 85% of infrared heat and nearly all harmful UV rays without needing a super dark tint, leaving the car feeling way more comfortable.
Automotive Tinting Film Market Share,By Technology, 2025 (%)
| By Technology | Revenue Share, 2025 (%) |
| Non-Reflective Films | 36% |
| Reflective Films | 17% |
| Nano-Ceramic Films | 29% |
| Multi-Layer Sputtered Films | 18% |
Distribution Channel Insights
The aftermarket segment dominated the market with the largest share of 73% in 2025. The aftermarket offers a diverse array of advanced film technologies, including dyed, metalized, carbon, and high-performance ceramic films. Moreover, the majority of vehicle owners elect to procure and apply these films post-purchase, bypassing factory glass limitations. This approach empowers consumers to customize their vehicles to suit personal preferences, specific climatic requirements, and regional legal mandates. Digital stores allow buyers to compare prices and check local tint laws before buying, driving segment growth further.
The OEM segment held the market share of 27% in 2025 and is expected to grow at the fastest CAGR of 7.10% during the study period. Vehicle manufacturers are integrating advanced window films directly during assembly to boost energy efficiency and cabin comfort. These efforts are supported by long-term contracts with specialty film producers. Furthermore, to facilitate thermal regulation without causing electromagnetic interference with critical vehicle sensors or telematics infrastructure, OEMs leverage non-metallic connected film technologies and nano-ceramic coating matrices.
Automotive Tinting Film Market Share,By Distribution Channel, 2025 (%)
| By Distribution Channel | Revenue Share, 2025 (%) |
| OEM | 27% |
| Aftermarket | 73% |
Regional Analysis
How did Asia Pacific Dominate the Automotive Tinting Film Market in 2025?
The Asia Pacific automotive tinting film market size was estimated at USD 3.41 billion in 2025 and is projected to reach USD 7.09 billion by 2035, growing at a CAGR of 7.59% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 39% in 2025. The dominance of the region can be attributed to the rising disposable incomes, increasing urbanization, and a growing fleet of passenger vehicles. In addition, extreme weather in tropical areas and the urgent need for UV protection boost this growth further. Also, the rapid adoption of electric vehicles plays a major role in boosting the market.
 China
- The sustained rise in passenger vehicle sales directly correlates with the growing aftermarket demand for tinting films, as new vehicle owners frequently purchase films for aesthetic enhancement and vehicle protection.
- China’s aggressive push toward electric vehicles is a major catalyst for market growth. EV owners prioritize heat-reflecting and energy-efficient films because they minimize the usage of air conditioning, hence preserving battery range.
India
- Surging middle-class purchasing power has led to higher vehicle ownership and increased spending on luxury automotive accessories.
- The transition from traditional, dyed films to advanced nanoceramic and graphene-infused films enables high infrared (IR) heat rejection without blocking GPS or mobile signals.
The North America automotive tinting film market size was estimated at USD 2.36 billion in 2025 and is projected to reach USD 4.94 billion by 2035, growing at a CAGR of 7.67% from 2026 to 2035.North America held the market share of 27% in 2025 and was expected to grow at the fastest CAGR of 8.00% over the forecast period. The growth of the region can be credited to the substantial consumer investment in vehicle customization, escalating temperatures, and an increasing demand for solar and UV protection. Furthermore, the market benefits from a robust automotive aftermarket sector and a high density of premium and electric vehicles.
United States
- Increasing consumer preference for superior heat rejection is propelling the adoption of premium films such as nano-ceramic and infrared-blocking films.
- Growing health awareness about skin protection against harmful UV rays and the safety benefits of shatter-resistant films can fuel country growth soon.
Canada
- Growing consumer awareness regarding the dermatological benefits of blocking harmful UV rays driving adoption in the country soon.
- Privacy tinting helps secure valuables left in vehicles and prevents outsiders from looking into parked cars.
The Europe automotive tinting film market size was estimated at USD 1.66 billion in 2025 and is projected to reach USD 3.50 billion by 2035, growing at a CAGR of 7.74% from 2026 to 2035.Europe held a market share of 19% in 2025. The growth of the region can be attributed due to the increasing consumer preference for high-SPF window films designed to mitigate harmful ultraviolet (UV) radiation, attenuate solar glare, and protect occupants against dermatological and ocular risks. Furthermore, individuals and organizations apply these protective tinting films to safeguard high-value interior furnishings, impacting positive regional growth soon.
Germany
- Germany's strong push for electric vehicles (EVs) is a massive growth factor. Tinting and solar-control films are heavily utilized to reduce cabin heat and, hence, enhance battery range.
- Transition from conventional dyed films to advanced nano-ceramic and graphene-enhanced coatings ensures high durability and non-metallic signal interference.
France
- Increasing temperatures during European summers have pushed French consumers to seek high-quality tinting for heat rejection, glare reduction, and interior preservation.
- There is a strong increasing trend among European drivers to customize their vehicle aesthetics while also seeking premium safety films that provide shatter resistance.
The Latin America automotive tinting film market size was estimated at USD 0.70 billion in 2025 and is projected to reach USD 1.53 billion by 2035, growing at a CAGR of 8.13% from 2026 to 2035. Latin America held a market share of 8% in 2025. The growth of the region can be driven by rising disposable incomes among the expanding middle class in regions like Argentina and Brazil coupled with the regional footprint of automotive leaders such as General Motors and Ford, which stimulate aftermarket tinting installations. This growing market adoption is further supported by innovations in nano-ceramic and graphene technologies.
Automotive Tinting Film Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| Asia-Pacific | 39% |
| North America | 27% |
| Europe | 19% |
| Latin America | 8% |
| Middle East & Africa | 7% |
Brazil
- Increasing crime rates in urban areas drive consumers to install thicker, security-focused tinting films to deter break-ins and prevent glass from shattering during accidents.
- There is a increasing consumer understanding of the health risks associated with prolonged UV exposure while driving, leading to country growth soon.
Argentina
- There is a robust regional shift towards advanced tint options like nano-ceramic and infrared-absorbing films, which offer superior cooling without restricting nighttime visibility.
The Middle East and Africa automotive tinting film market size was estimated at USD 0.61 billion in 2025 and is projected to reach USD 1.35 billion by 2035, growing at a CAGR of 8.27% from 2026 to 2035.The Middle East & Africa held a market share of 7% in 2025. The growth of the region can be attributed to the rising disposable incomes and a strict luxury-car culture, the regional market notably led by the GCC countries, such as the UAE and Saudi Arabia, which relies heavily on these films for solar protection and aesthetic appeal. Tinting films are widely adopted for cosmetic enhancement, custom vehicle styling, and enhanced privacy.
Saudi Arabia
- Saudi Arabia's increased temperatures & solar radiation create a demand for high-performance heat rejection & UV-blocking films.
- High vehicle ownership rates and a strong consumer preference for luxury and premium automobiles boost the demand for high-end tinting solutions.
UAE
- The increasing adoption of advanced nanoceramic and infrared-absorbing (IR) films offers superior solar protection without interfering with modern in-car electronics and GPS systems.
- Many consumers readily invest in premium tinting and paint protection films (PPF) to maintain upholstery and prevent interior fading.
Competitive Analysis
- The competition in the industry is consolidating around high-tech, premium, and nanotechnology films, with major market players increasingly investing in research and development to increase their market share.
The 3M™ Automotive Window Film Ceramic IR Series ensures uninterrupted connectivity for all wireless devices. - Constructed with advanced ceramic materials, this film does not interfere with electronic or mobile signals, hence facilitating seamless connections to modern 5G networks.
- The Johnson Window Films company specializes in manufacturing high-quality solar protection, safety, security, and anti-graffiti window films. To support its global dealer network, the organization provides advanced pattern-cutting software, a cooperative store program, and extensive professional resources.
Recent Development
- In March 2026, Auto Glass Stars, an automotive glass specialist based in San Tan Valley, has expanded its ceramic window tinting services. This strategic initiative directly addresses the growing consumer demand for advanced thermal regulation and ultraviolet protection.(Source: www.hillsdale.net)
- In February 2025, Avery DennisonⓇ (NYSE:AVY) has officially launched its new Encore™ automotive window film portfolio, representing an innovative range of products engineered to establish a new benchmark in performance and style for industry professionals and automotive enthusiasts alike.(Source: graphics.averydennison.com)
Top Vendors in the Automotive Tinting Film Market & Their Offerings
- 3M: The brand remains an industry benchmark, holding a massive market share through premium technological innovation, robust installer networks, and a strong global distribution footprint.
- Eastman Chemical Company: It is a leading global company in the automotive tinting & performance films market. Operating through its Eastman Performance Films division, the company manufactures premium window tints and paint protection films (PPF) known for solar control, UV protection, and advanced aesthetics.
- TintFit Window Films Ltd.: TintFit focuses heavily on aftermarket and trade distribution, serving both automotive installers and the public directly. Their automotive product lines target core consumer demands.

Other Key Players
- Avery Dennison Israel Ltd. (Hanita Coatings RCA Ltd.)
- Johnson Window Films, Inc.
- GLOBAL WINDOW FILMS
- Madico, Inc.
- Saint-Gobain Performance Plastics Corporation
- TWF
- Armolan
- NEXFIL
- Solar Screen International SA
- Huper Optik USA
Segments Covered in the Report
By Film Type
- Dyed Film
- Metalized Film
- Carbon Film
- Ceramic Film
- Hybrid Film
- Dyed-Metalized Hybrid
- Carbon-Ceramic Hybrid
By Vehicle Type
- Passenger Vehicles
- Hatchbacks
- Sedans
- SUVs
- Luxury Vehicles
- Light Commercial Vehicles (LCV)
- Heavy Commercial Vehicles (HCV)
By Application
- Side Windows
- Front Side Windows
- Rear Side Windows
- Rear Windshield
- Front Windshield
- Sunroof
- Quarter Glass & Other Windows
By Visible Light Transmission (VLT)
- Below 20%
- 20%–35%
- 35%–50%
- Above 50%
By Technology
- Non-Reflective Films
- Reflective Films
- Nano-Ceramic Films
- Multi-Layer Sputtered Films
By Distribution Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket
- Authorized Installers
- Independent Tinting Centers
- Online Retail
By Regional
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.