
Synthetic Fuels Market Size, Competitive Landscape Analysis Report 2035
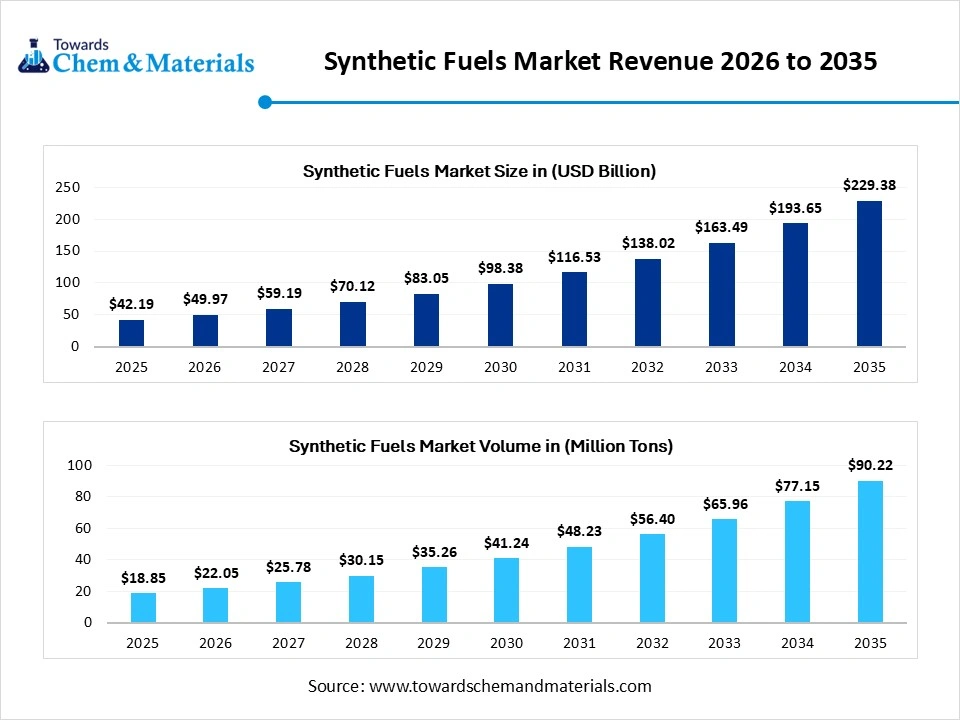
The global synthetic fuels market was valued at USD 42.19 billion in 2025, is estimated to reach USD 49.97 billion in 2026, and is projected to reach USD 229.38 billion by 2035, growing at a CAGR of 18.45% from 2026 to 2035. In terms of volume, the synthetic fuels market is projected to grow from 18.85 million tons in 2025 to 90.22 million tons by 2035. growing at a CAGR of 16.95% from 2026 to 2035.
Key Takeaways
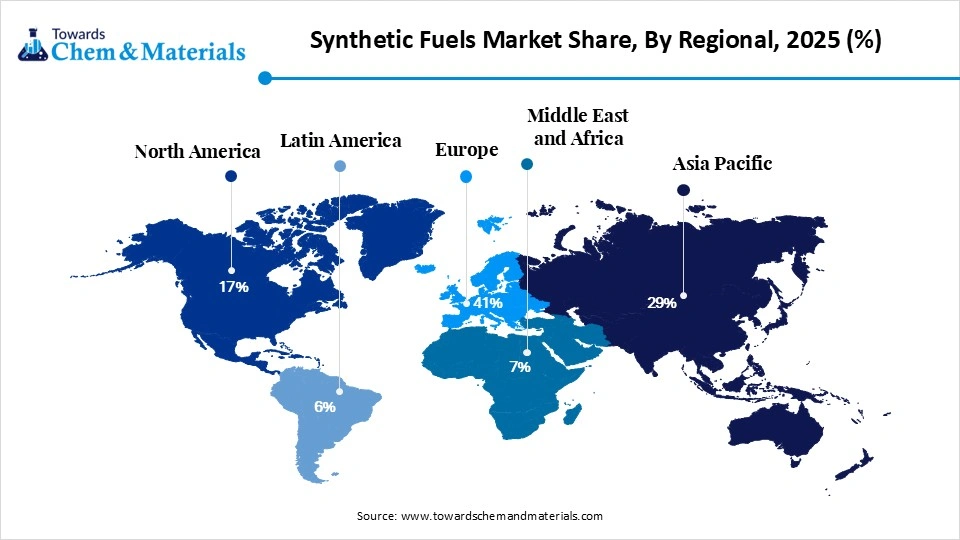
- Europe dominated the synthetic fuels market with the largest revenue share of 41% in 2025.
- By feedstock, the natural gas segment led the market with the largest revenue share of 38% in 2025.
- By fuel, the synthetic diesel segment led the market with the largest revenue share of 39% in 2025.
What are Synthetic Fuels Market?
The market consists of producing liquid or gaseous fuels, like gasoline, diesel, and kerosene through chemical processes rather than refining crude oil. These man-made fuels are often extracted from natural gas, coal, biomass, or captured carbon dioxide, which acts as a direct substitute for conventional fossil fuels in current engines. The raw materials used are extensive, ranging from non-renewable sources such as coal and natural gas to renewable sources, including biomass combined with green hydrogen.
Synthetic Fuels Market Trends
- The ongoing investments in renewable energy sources are the latest trend in the market, shaping positive market growth. As major countries are striving to diversify their investments in solar, wind, and hydroelectric power along with their energy portfolios. These renewable sources can be used to create the electricity required for synthetic fuel production.
- Major companies are rapidly joining forces with technology providers, research institutions, and other stakeholders to boost the commercialization and development of synthetic fuels. These collaborations can optimize knowledge sharing, risk mitigation, and resource pooling.
- The ongoing technological advancements in manufacturing efficiency are substantially improving the viability and scalability of synthetic fuels by emphasizing key operational and cost hurdles. Also, innovations encompass enhancements in reactor design, catalyst development, and integrated process technologies that facilitate the conversion of essential materials into usable fuels.
Report Scope
| Report Attribute | Details |
| Market Size and Volume in 2026 | USD 49.97 Billion / 22.05 Million Metric Tons |
| Expected Size and Volume by 2035 | USD 229.38 Billion / 90.22 Million Metric Tons |
| Growth Rate from 2026 to 2035 | CAGR 18.45% |
| Forecast Period | 2026 - 2035 |
| Dominant Region | Europe |
| Segment Covered | By Feedstock, By Fuel and By Regions |
| Key companies profiled | Sasol Limited, Chevron Corporation, Airbus SE, TotalEnergies SE, Neste Oyj, Johnson Matthey Plc, Repsol S.A., Synhelion SA |
How Cutting-Edge Technologies Are Revolutionizing the Synthetic Fuels Market?
Advanced technologies are revolutionizing the market by allowing potentially lower-lifecycle-emission fuel production, depending on feedstock and energy sources, slashing manufacturing costs, and enhancing overall efficiency. Key developments include innovations in Direct Air Capture (DAC), synthetic biology, advanced catalysts, and co-electrolysis. Furthermore, engineers are increasingly using nanotechnology to design catalysts with high surface-area-to-volume ratios, substantially enhancing reaction rates in the Fischer-Tropsch process.
Trade Analysis of the Synthetic Fuels Market: Import & Export Statistics
- In 2024, the U.S. exported 55% of its domestic crude oil and natural gas plant liquids (NGPL) production, including both raw crude and refined products like gasoline and propane.
- In 2024, China's chemical trade grew 1.2% to $1.949 trillion, fueled by recovering global demand, according to the China Minmetals Chemical Import and Export Chamber.
- According to data from the National Bureau of Statistics, China imported a total of 28.7035 million tons of fuel oil in 2024, a year-on-year increase of 1.82%; The total export volume of fuel oil in China was 20.274 million tons, a year-on-year increase of 1.82%.
Supply Chain Analysis of Synthetic Fuels Market
Feedstock Procurement
It refers to the acquisition, logistics, and processing of essential materials like carbon dioxide, biomass waste used as input for manufacturing synthetic fuels such as biodiesel and sustainable aviation fuel (SAF).
- Major Players: Neste, Shell
Chemical Synthesis and Processing
It involves the conversion of carbon-based feedstocks into liquid chemical intermediates and transportation fuels using innovative chemical techniques.
- Major Players: Neste Oyj, TotalEnergies SE
Packaging and Labelling
Storage and distribution involve fuel handling, transport, blending where applicable, and quality checks to maintain product specifications and safe delivery.
- Major Players: Sunfire GmbH, Velocys plc
Regulatory Compliance and Safety Monitoring
Regulatory compliance involves checking that synthetic fuels meet applicable fuel-quality, environmental, transport, and safety requirements throughout production and distribution
- Major Players: Intertek, Ricardo
Synthetic Fuels Market's Regulatory Landscape: Global Regulations
| Country/Region | Key Regulations |
| Europe (EU & UK) | The EU Renewable Energy Directive (RED III) establishes renewable-energy targets and rules relevant to renewable fuels of non-biological origin; applicability depends on the fuel pathway and the directive’s eligibility criteria. |
| United States | U.S. policy support relevant to low-carbon fuels includes federal tax incentives, the Sustainable Aviation Fuel Grand Challenge, and California’s Low Carbon Fuel Standard. Their eligibility rules and coverage differ by program. |
| Middle East | GCC nations like Saudi Arabia and the UAE are investing in massive projects integrating green hydrogen for synthetic fuel production. |
Market Dynamics
Driver
Expansion of Green Hydrogen Infrastructure
Decreasing costs of renewable electricity and a surge in green hydrogen infrastructure allow for cleaner, cheaper production of synthetic fuels. It also can significantly enhance sustainability. In addition, many countries are heavily investing in domestic synthetic fuel production to minimize reliance on foreign fossil fuel imports, leading to market growth soon.
Restraint
High Production Costs
Capital costs, electricity prices, hydrogen production, and conversion efficiency can make some synthetic-fuel pathways more expensive than conventional fuels, which is the major factor hindering market growth. Moreover, immense competition from substitute low-carbon solutions, such as ammonia, advanced biofuels, and traditional fossil fuels, further impacts the market expansion.
Opportunity
Shift Towards Low-Carbon Energy Sources
The ongoing shift towards low-carbon energy sources is the current trend in the market, presenting lucrative opportunities. There is a significant push from corporations, governments, and consumers to minimize greenhouse gas emissions. Furthermore, ongoing innovations in technology are enabling synthetic fuel production to be more cost-effective and efficient, which in turn results in increasing demand for low-carbon energy solutions.
Segmental Insights
Feedstock Insights
Natural Gas Segment Dominated the Market with Largest Share in 2025
The natural gas segment dominated the market with the largest share in 2025. Potential factors supporting this segment include established gas-to-liquids technology and natural-gas availability
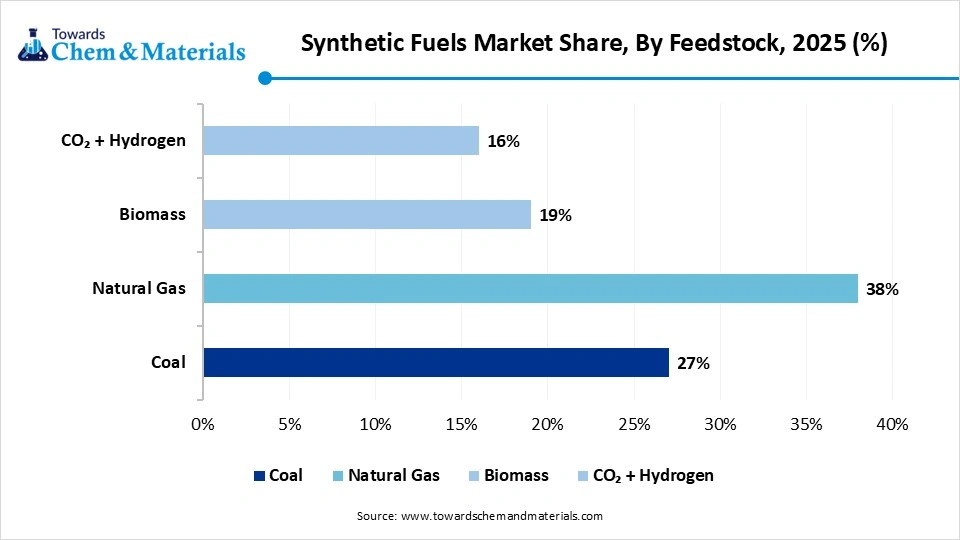
The COâ‚‚ + hydrogen segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be credited to the ongoing efforts to manufacture carbon-neutral and carbon recycling technologies. China uses its extensive coal reserves to minimize reliance on crude oil.
The coal segment held a significant market share in 2025. The growth of the segment can be linked to the rise in availability of low-cost raw materials along with the innovations in Fischer-Tropsch technology. Countries use CTL technologies to minimize reliance on imported crude oil.
The biomass segment held a notable market share in 2025. The growth of the segment can be driven by ongoing innovations in Bio-to-Liquid (BtL) technologies and stringent environmental regulations. BTL technologies convert forestry waste and agricultural residues into valuable energy.
Fuel Insights
Synthetic Diesel Segment Dominated the Market with Largest Share in 2025
The synthetic diesel segment dominated the market with the largest share in 2025. The dominance of the segment is owed to its compatibility with current fuel distribution infrastructure, diesel engines, and industrial applications. It also provides enhanced combustion efficiency with lower particulate emissions.
The synthetic jet fuel (SAF) segment is expected to grow at the fastest CAGR during the forecast period. Approved sustainable aviation fuel pathways can be blended with conventional jet fuel within applicable specifications and limits; compatibility depends on the certified pathway and relevant aviation-fuel standards.
Synthetic Fuels Market Share, By Fuel, 2025 (%)
| By Fuel | Revenue Share, 2025 (%) |
| Synthetic Diesel | 39% |
| Synthetic Gasoline | 24% |
| Synthetic Jet Fuel (SAF) | 28% |
| Others | 9% |
The synthetic gasoline segment held a significant market share in 2025. The growth of the segment can be attributed to the growing need for low-carbon fuels and the use of green hydrogen and CO2 capture technologies. Many countries are heavily investing in synthetic fuels.
The other segment held the notable market share in 2025. The growth of the segment can be credited to the stringent government policies and increasing innovations in Power-to-Liquid (PtL) technologies. Rise in partnerships between energy companies and industrial end users is driving segment growth further.
Regional Insights
How did Europe Dominate the Synthetic Fuels Market in 2025?
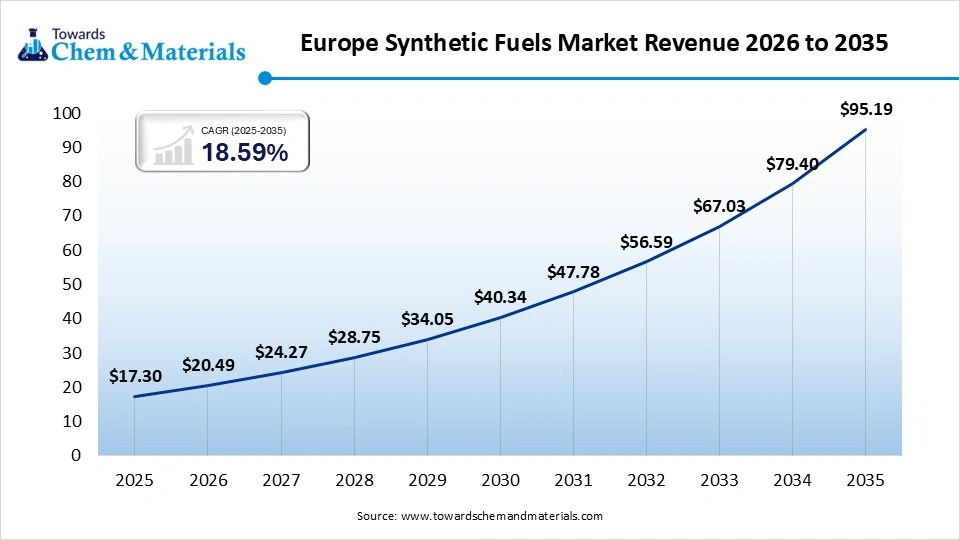
The Europe synthetic fuels market size was estimated at USD 17.30 billion in 2025 and is projected to reach USD 95.19 billion by 2035, growing at a CAGR of 18.59% from 2026 to 2035. The dominance of the region can be attributed to the extensive investments in Power-to-Liquids (PtL) and green hydrogen technologies along with the strict decarbonization targets in many countries. In addition, heavy reliance on fossil fuels has impelled European nations to invest in locally manufactured carbon-neutral energy sources, ensuring a more reliable energy supply.
Germany Synthetic Fuels Market Trends
The growth of the market in the country is due to the growing demand for transport and aviation decarbonization, coupled with the rising private and industrial investment in energy infrastructure. Also, Germany is home to leading technology providers such as INERATEC's plant in Frankfurt, which produces a significant amount of e-fuel annually.
Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The growth of the region can be credited to the increasing energy demand and substantial investments in carbon capture and hydrogen technologies. Furthermore, increasing per capita income in emerging countries such as China and India has boosted the growth of the automotive sector, propelling demand for sustainable fuel alternatives.
China Synthetic Fuels Market Trends
In the Asia Pacific, China dominated the market owing to the surge in demand for sustainable energy in the transportation sector along with the rapid technological innovations in the Fischer-Tropsch synthesis process to improve manufacturing efficiency. Moreover, the country uses its extensive natural gas (GTL) and coal reserves (CTL) to minimize reliance on imported crude oil.
Recent Development
- In March 2026, global automotive supplier Marelli unveiled a new generation of Port Fuel Injection Engine Control Units (PFI ECUs). Designed for versatility, these ECUs support gasoline, flex fuel (ethanol, methanol, synthetic fuels), and Compressed Natural Gas (CNG) for vehicles in Brazil, India, and EMEA.
Synthetic Fuels Market Competitive Landscape Analysis
Tier 1 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | Shell plc | London, England | United Kingdom | Global leader in synthetic fuels, GTL technologies, SAF, and e-fuels investments | Fischer-Tropsch fuels, SAF, synthetic diesel, GTL products |
| 2 | Sasol Limited | Johannesburg, Gauteng | South Africa | Pioneer in commercial Fischer-Tropsch synthetic fuel production | Synthetic diesel, synthetic gasoline, chemicals, FT fuels |
| 3 | Exxon Mobil Corporation | Spring, Texas | United States | Major investor in low-carbon fuels, hydrogen, and synthetic fuel technologies | Synthetic fuels, low-carbon fuels, hydrogen-based fuels |
| 4 | Neste Oyj | Espoo, Uusimaa | Finland | Leading producer of renewable and synthetic transportation fuels | SAF, renewable diesel, synthetic hydrocarbons |
| 5 | TotalEnergies SE | Courbevoie, Île-de-France | France | Active developer of synthetic aviation fuels and e-fuel projects globally | SAF, e-fuels, renewable synthetic fuels |
Tier 2 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | HIF Global | Houston, Texas | United States | One of the world's leading dedicated e-fuel project developers | E-methanol, e-gasoline, synthetic fuels |
| 2 | Sunfire GmbH | Dresden, Saxony | Germany | Leading supplier of electrolyzer and Power-to-Liquid technologies | E-fuels, synthetic hydrocarbons, green hydrogen |
| 3 | Infinium Holdings, Inc. | Sacramento, California | United States | Commercial producer of ultra-low-carbon synthetic fuels | E-diesel, e-SAF, synthetic fuel products |
| 4 | Velocys plc | Oxford, England | United Kingdom | Developer of Fischer-Tropsch technology for SAF and synthetic fuels | SAF technology, FT fuels, synthetic hydrocarbons |
| 5 | Topsoe A/S | Lyngby | Denmark | Major provider of e-fuel, SAF, and Power-to-X technologies | E-methanol, SAF technologies, synthetic fuel catalysts |
Tier 3 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | Synhelion SA | Zurich | Switzerland | Developer of solar-based synthetic fuel production technologies | Solar fuels, synthetic kerosene, synthetic diesel |
| 2 | Arcadia eFuels | Washington, D.C. | United States | Focused on large-scale sustainable aviation fuel and e-fuel projects | E-SAF, synthetic aviation fuels |
| 3 | Twelve Benefit Corporation | Berkeley, California | United States | Converts captured CO₂ into synthetic fuels and chemicals | E-fuels, sustainable aviation fuel, CO₂-derived products |
| 4 | Nordic Electrofuel AS | Porsgrunn | Norway | Developing commercial e-kerosene and aviation fuel facilities | E-kerosene, synthetic aviation fuels |
| 5 | Carbon Recycling International hf. | Reykjavik | Iceland | Pioneer in commercial CO₂-to-methanol production | E-methanol, synthetic fuel intermediates |
Synthetic Fuels Market Companies
- Shell Plc: Shell Plc is actively positioning itself as a major player in the synthetic fuels and low-carbon energy market, aiming to decarbonize sectors like aviation and transport.
- ExxonMobil Corporation: ExxonMobil Corporation is a primary global player in the synthetic fuels market, leveraging its legacy Methanol-to-Gasoline (MTG) technology and newer Low Carbon Solutions business to develop lower-emission alternatives.
Companies in the Synthetic Fuels Market
- Sasol Limited
- Chevron Corporation
- Airbus SE
- TotalEnergies SE
- Neste Oyj
- Johnson Matthey Plc
- Repsol S.A.
- Synhelion SA
Synthetic Fuels Market Segments Covered in the Report
By Feedstock
- Coal
- Natural Gas
- Biomass
- COâ‚‚ + Hydrogen
By Fuel
- Synthetic Diesel
- Synthetic Gasoline
- Synthetic Jet Fuel (SAF)
- Others
By Regions
- North America
- U.S.
- Canada
- Mexico
- U.S.
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Germany
- Asia Pacific
- China
- India
- Japan
- South Korea
- China
- Latin America
- Brazil
- Argentina
- Brazil
- Middle East & Africa
- Saudi Arabia
- South Africa
- Saudi Arabia
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.