Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
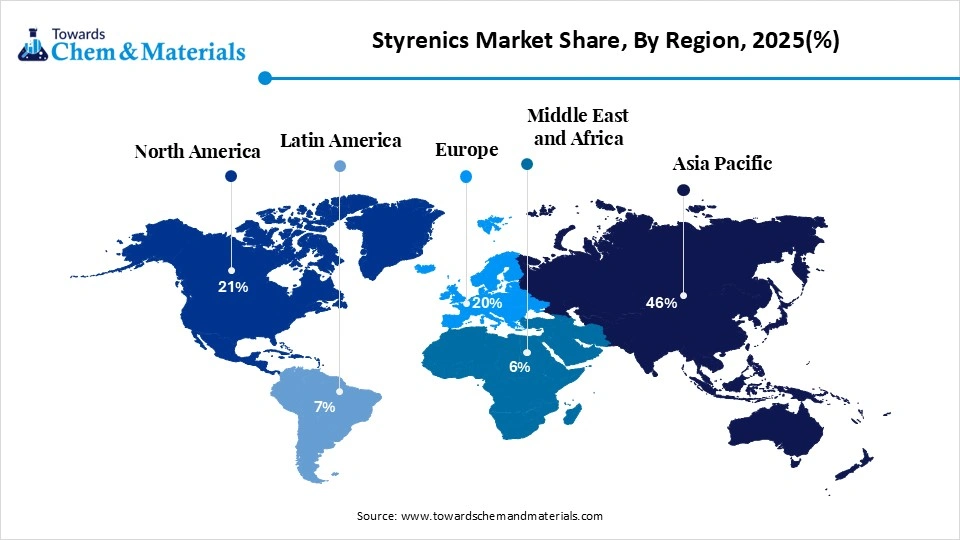
The styrenics market size was valued at USD 114.35 billion in 2025, is estimated to reach USD 121.04 billion in 2026, and is projected to reach USD 201.90 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.85% over the forecast period from 2026 to 2035.Asia Pacific dominated the styrenics market market with the largest revenue share of 46% in 2025 and is expected to grow at the fastest CAGR of 5.96% during the forecast period. The increase in packaging, automotive, consumer electronics, and healthcare applications is contributing to the growth of the market. The use of lightweight materials, growth of eCommerce and the development of chemical recycling and bio-attributed styrenics are driving sustainable production forward at a fast pace, while opening new market opportunities in a variety of end-use applications.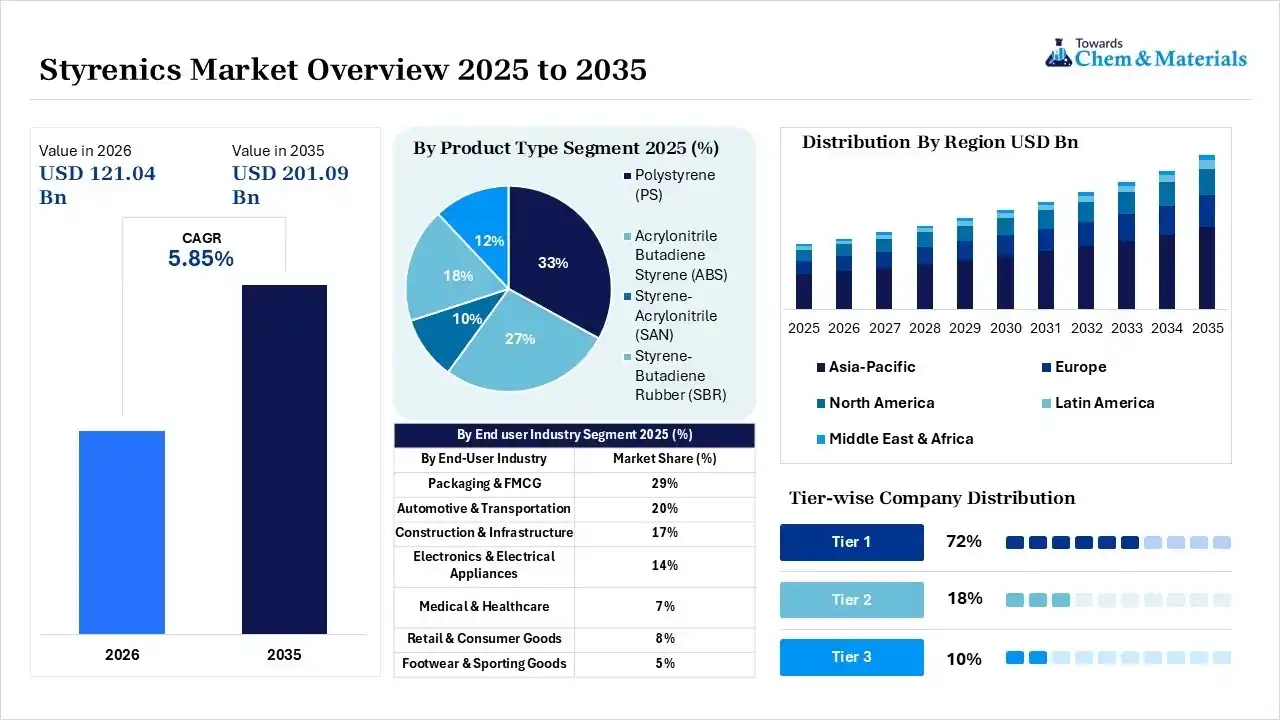
According to Towards Chemicals and Materials Analytics and Consulting, the global styrenics market volume was valued at 40.85 million tons in 2025 and is expected to surpass around 66.22 million tons by 2035, accelerating a compound annual growth rate (CAGR) of 4.95% over the forecast period from 2026 to 2035.
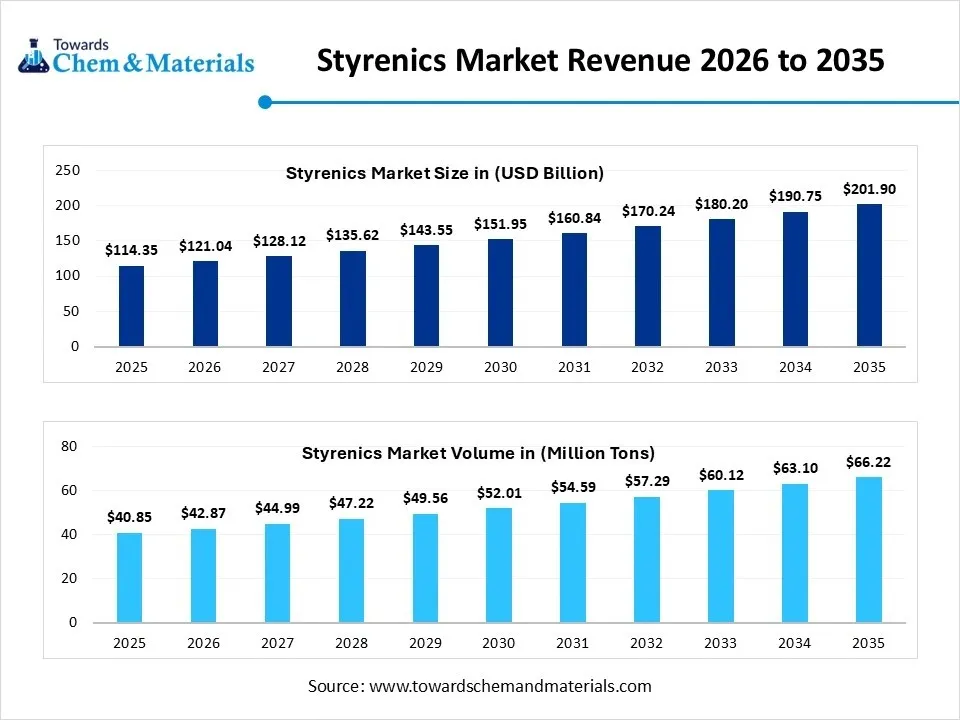
The steady growth of the styrenics market is due to rising demand in the packaging, automotive, consumer electronics, and healthcare sectors. Increasingly lightweight, durable, and affordable plastic materials are driving broad use in various applications. Market growth is further bolstered by continued growth in e-commerce transactions and growing demand for protective food packaging, with emerging opportunities in the electric vehicle market driven by higher investments.
Chemical recycling technologies, bio-attributed feedstocks, and mass-balanced production processes are being developed to help manufacturers to achieve the targets of the circular economy and minimize environmental effects. Production efficiency is enhanced further by electrified steam cracker technologies, and sustainable manufacturing processes are reducing carbon emissions.
The styrenics market comprises a family of thermoplastic polymers derived from styrene monomer, used across a wide range of applications including packaging, automotive, construction, electronics, medical devices, and consumer goods. The market includes key products such as polystyrene (PS), expanded polystyrene (EPS), acrylonitrile butadiene styrene (ABS), styrene-butadiene rubber (SBR), styrene-acrylonitrile (SAN), and styrene block copolymers (SBC). These materials are valued for their moldability, impact resistance, insulation properties, and cost-effectiveness.
The enlarged expansion of the packaging industry is spearheading the industrys growth in the current period. Having the unique characteristics such as affordability, lightweight, and easy to shape has provided immense attention to the styrenics materials like polystyrene and expanded polystyrene. Moreover, these properties are also making it ideal for food packaging and electronics. Also, the need for protective and hygienic packaging has contributed to the industrys potential in recent years.
| Report Attributes | Details |
| Market Size in 2026 | USD 121.04 Billion/ 42.87 Million Tons |
| Market Size by 2035 | USD 201.90 Billion/ 66.22 Million Tons |
| Growth rate | CAGR 5.85% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Product Type, By Application, By End-User Industry, By Region |
| Key Companies Profiled | INEOS Group AG, BASF SE, SABIC, Chevron Phillips Chemical Company LLC, Repsol, LG Chem, Trinseo, TotalEnergies Styrenics |
The increasing demand for electric vehicles and electronics is expected to create significant opportunities for manufacturers in the coming years. Having properties like lightweight, heat resistance, and strength make the styrenics the ideal material in the development of modern electronics and electric vehicles. Also, the manufacturers can establish a partnership or collaboration with vehicle manufacturers, which can provide long-term profit margins and trust initiatives to the manufacturers during the projected period.
Styrenics Industry Faces Turning Point Amid Plastic Reduction Mandates
The increased pressure from the government to reduce plastic waste is anticipated to hamper the industrys growth in the coming years. Moreover, several governments across the world are trying to reduce plastic dependency by using alternatives, which is limiting the sales of the styrenics. However, the manufacturers can take advantage of this sustainability shift by integrating the eco-friendly materials in the production of the styrenics, and they can also invest in the research and development activities for sustainable alternatives, which are affordable in the coming years.
The polystyrene segment held the largest share of the market in 2025, due to its wide applications in sectors like insulation, packaging, and consumer products. Moreover, having unique characteristics such as affordability, lightweight, and easy molding, the polystyrene segment gained immense popularity in recent years. Also, the increased need for thermal insulation and fragile packaging protection has heavily provided the sophisticated consumer base to the polystyrene segment in the past few years.
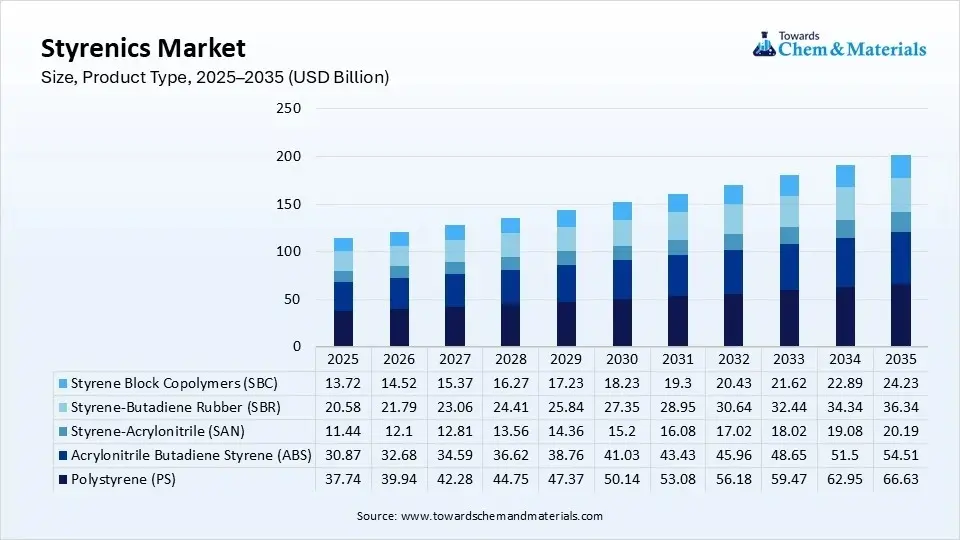
The acrylonitrile butadiene styrene (ABS) segment is expected to grow at a notable rate during the predicted timeframe due to its combination of strength, toughness, and flexibility-making it suitable for many industries. ABS is used widely in automotive parts, electronics, home appliances, and even 3D printing. It is lightweight, impact-resistant, and easy to mold, which makes it ideal for complex designs and durable products. As electric vehicles and consumer electronics continue to grow, the demand for ABS will rise. Additionally, its use in medical devices and toys is expanding due to its safety and chemical resistance. These advantages make ABS a top choice for future product innovation.
Styrenics Market Share, By Product Type, 2025(%)
| By Product Type | Market Share (%) |
| Polystyrene (PS) | 33% |
| Acrylonitrile Butadiene Styrene (ABS) | 27% |
| Styrene-Acrylonitrile (SAN) | 10% |
| Styrene-Butadiene Rubber (SBR) | 18% |
| Styrene Block Copolymers (SBC) | 12% |
The packaging segment held the largest share of the global styrenics market in 2025, owing to the affordability, lightweight, and durability of the PS and EPS materials. Furthermore, these materials are considered essential in the making of food containers, protective packaging, and trays, which has led to their demand in recent years. Also, the sudden surge in e-commerce, retail consumption, and food delivery has contributed to the packaging growth in the past few years.
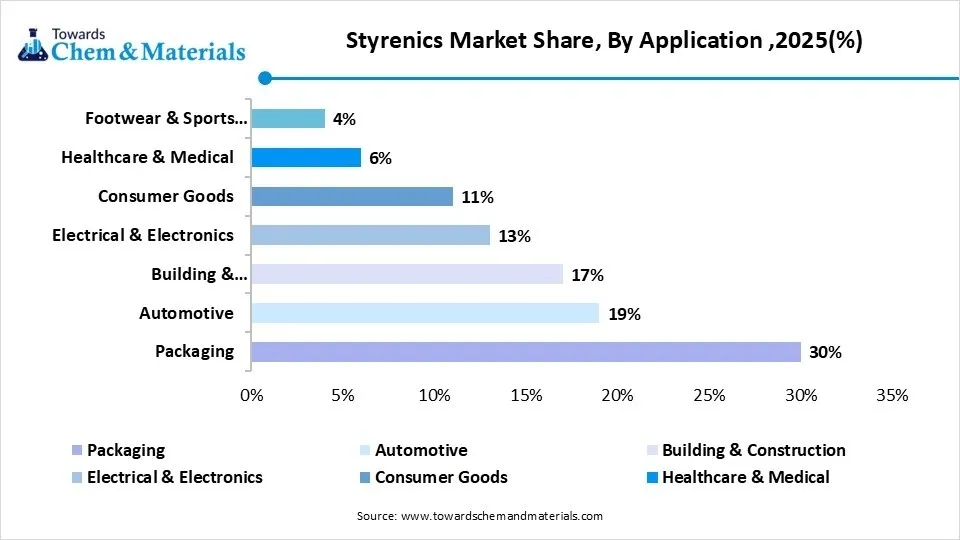
The automotive segment is expected to grow at a notable rate, as carmakers are using more lightweight plastic parts to reduce vehicle weight and improve fuel efficiency. Styrenics like ABS and SAN are perfect for making dashboards, trims, and bumpers because they are strong, durable, and easy to mold. With the rise of electric vehicles (EVs), manufacturers want materials that are safe, heat-resistant, and cost-effective. Styrenics also help lower production costs compared to metal parts. As more countries push for EV adoption and lightweight cars, the demand for styrenics plastics in the automotive sector will continue to grow quickly.
Styrenics Market Share, By Application ,2025(%)
| By Application | Market Share (%) |
| Packaging | 30% |
| Automotive | 19% |
| Building & Construction | 17% |
| Electrical & Electronics | 13% |
| Consumer Goods | 11% |
| Healthcare & Medical | 6% |
| Footwear & Sports Equipment | 4% |
The packaging and FMCG segment dominated the market with the largest share in 2025. These sectors require lightweight, low-cost, and easy-to-process plastics. Styrenics like polystyrene are widely used for food containers, hygiene products, household items, and electronics packaging. FMCG companies need reliable materials that protect products, attract consumers, and reduce shipping costs. Styrenics meet these needs while offering flexibility in design and production. With rising urbanization and consumer spending globally, the need for convenient, protective, and affordable packaging continues to rise-making packaging and FMCG the largest end-user segment for styrenics products worldwide.
The medical segment is expected to grow at a notable rate due to rising demand for safe, durable, and hygienic materials in healthcare. Styrenics like ABS and styrene-acrylonitrile (SAN) are widely used in medical devices, diagnostic tools, and lab equipment. They are resistant to chemicals, easy to sterilize, and dont break easily, making them ideal for hospitals and clinics. As global healthcare spending increases and more advanced medical technologies emerge, the need for reliable plastic components will grow. The shift toward disposable and single-use medical products will also boost the demand for styrenics materials in the medical field.
Styrenics Market Share, By End-User Industry, 2025(%)
| By End-User Industry | Market Share (%) |
| Packaging & FMCG | 29% |
| Automotive & Transportation | 20% |
| Construction & Infrastructure | 17% |
| Electronics & Electrical Appliances | 14% |
| Medical & Healthcare | 7% |
| Retail & Consumer Goods | 8% |
| Footwear & Sporting Goods | 5% |
How did the Asia Pacific Dominate the Styrenics Market in 2025?
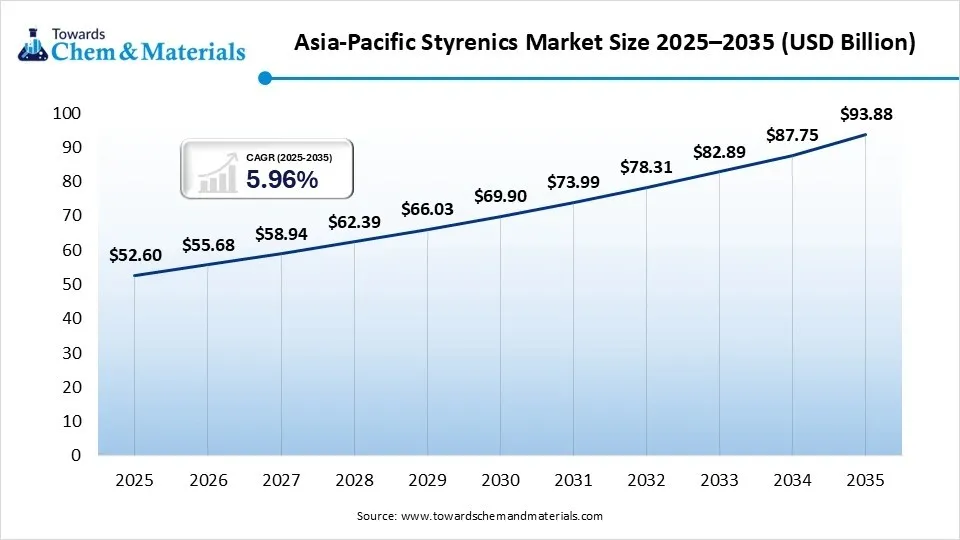
The Asia Pacific styrenics market size was estimated at USD 52.60 billion in 2025 and is projected to reach USD 93.88 billion by 2035, growing at a CAGR of 5.96% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 46% in 2025 and is expected to grow at the fastest CAGR of 6.7% during the forecast period, as the region has a robust base of petrochemical manufacturing facilities, a rapidly growing automotive and electronics industry, and a growing packaging market. The industry is being further supported by a surge in sustainable plastics investments and steady increases in chemical recycling capabilities, which are driving market growth in the region. The involvement of key manufacturers also boosts production and innovation along the value chain.
China
India
North America held 21% market share in 2025, due to high demand from the packaging, healthcare, automotive, and consumer goods sectors. Advancements in technology for recycling and the development of sustainable materials are the ongoing drivers of market expansion in the region. The increasing diffusion of circular economy (CE) approaches provides a further boost to innovation and long-term competitiveness by using bio-attributed polymers.
United States
Canada
Europe held 20% market share in 2025, thanks to its robust environmental legislation, technology know-how, and growing uptake of circular economy concepts. There is still innovation taking place through growing investments in chemical recycling, sustainable feedstocks, and low-carbon production technologies. The automotive, healthcare, and packaging sectors are among other major industries driving local market growth.
Germany
France
Latin America held 7% market share in 2025, alongside the automotive industrys expansion and increased industrial development. Continued investments in manufacturing consumer goods and processing plastics still offer growth opportunities. Expansion of manufacturing activities should help markets to grow in the future in the region.
Brazil
Chile
The Middle East & Africa held 6% market share in 2025. Styrenics consumption is expanding in applications across different industries on the back of rising industrial activities and infrastructure development. The increasing attention on the production of petrochemicals in the downstream segment is likely to support the growth of the regional market in the coming years.
Saudi Arabia
South Africa
By Product Type
By Application
By End-User Industry
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo