
Stainless Steel Powder Market Size and Forecast 2026 to 2035
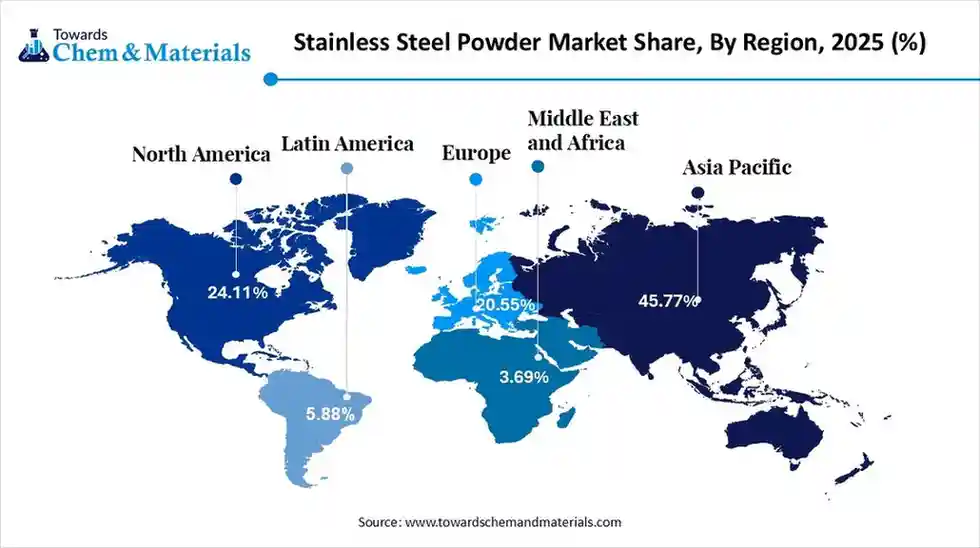
The global stainless steel powder market size was estimated at USD 899.72 million in 2025 and is predicted to increase from USD 942.55 million in 2026 and is projected to reach around USD 1,432.39 million by 2035, The market is expanding at a CAGR of 4.76% between 2026 and 2035. Asia Pacific dominated the stainless-steel powder market with a market share of 45.77% the global market in 2025.The rapid expansion of additive manufacturing and growing industrial applications drive the market growth.

Key Takeaways
- By region, Asia Pacific led the stainless steel powder market with the largest revenue share of over 45.77% in 2025.
- By region, North America is growing at the fastest CAGR in the market during the forecast period due to the huge demand for additive manufacturing.
- By grade, the austenitic segment led the market in 2025 due to its excellent biocompatibility & ductility.
- By grade, the duplex & super-duplex segment is growing at the fastest CAGR in the market during the forecast period due to its superior corrosion resistance.
- By manufacturing process, the gas/water atomization segment led the market in 2025 due to its high-volume capacity.
- By manufacturing process, the plasma atomization segment is expected to grow at the fastest CAGR in the market during the forecast period due to superior and low-oxygen powder quality.
- By application, the additive manufacturing and powder metallurgy segment led the market in 2025 due to the development of complex internal automotive & aerospace parts.
- By application, the metal injection molding (MIM) segment is expected to grow at the fastest CAGR in the market during the forecast period due to higher demand for complex shapes across diverse industries.
- By end-use industry, the medical & industrial engineering segment led the market in 2025 due to the rise in the creation of medical devices.
- By end-use industry, the aerospace & defense segment is expected to grow at the fastest CAGR in the market during the forecast period due to the development of high-strength aircraft parts.
- By form, the spherical powder segment led the market in 2025 due to its excellent flowability and process compatibility.
- By form, the custom alloy blends & pre-alloyed powders segment is expected to grow at the fastest CAGR in the market during the forecast period due to the increasing need for high-performance property materials.
What is Stainless Steel Powder?
The stainless steel powder market growth is driven by the huge production of intricate designs, booming use of 3D printing, focus on enhancing vehicle performance, development of biocompatible surgical instruments, innovations in powder metallurgy, increasing need for machinery, transition to green manufacturing, and development of high-performance aerospace parts.
Stainless steel powder is finely divided stainless steel, like chromium, molybdenum, iron, & nickel. It is available in uniform shape & size and is present in different grades like 430L, 304L, & others. It offers high corrosion resistance, temperature resistance, wear resistance, good ductility, formability, excellent strength, and weldability.
Stainless steel powder is used for aesthetic finishes and the production of protective coatings. Stainless steel is used in diverse applications like powder metallurgy, additive manufacturing, surface treatments, fluid processing, high-performance parts, and electrical device components.
Stainless Steel Powder Market Trends:
- Expanding Additive Manufacturing: The rising production of customized parts and development of complex geometrical shapes increases the adoption of additive manufacturing. The creation of high-strength parts and rapid design prototyping increases the adoption of grades like 316L, 304L.
- Automotive Industry Growth: The strong focus on enhancing fuel efficiency of vehicles, electrification of vehicles, and development of corrosion-resistant vehicle parts increases demand for stainless steel powder.
- Surging Construction Activities: The rise in high-rise buildings development and the growing manufacturing of transport infrastructure systems increases demand for stainless steel powder to produce structural components, cladding, rebars, and others.
- Food Processing Sector Expansion: The growing production of food and focus on maintaining hygiene in food production environments increase demand for stainless steel powders for the development of food processing equipment.
Report Scope
| Report Attribute | Details |
| Market Size Value in 2026 | USD 942.55 Million |
| Revenue Forecast in 2035 | USD 1,432.39 Million |
| Growth Rate | CAGR 4.76% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Dominant Region | Asia Pacific |
| Fastest Growing Region | North America |
| Segment Covered | By Grade / Type, By Manufacturing Process, By Application / End-Use, By End-User Industry, By Form / Product, By Region |
| Key companies profiled | Höganäs AB, Sandvik AB, Carpenter Technology Corporation, GKN Powder Metallurgy / GKN Additive, Daido Steel Co., Ltd, ATI Powder Metals , AP&C , LPW Technology , Oerlikon AM , CNPC Powder Material Co., Ltd. , EOS , Renishaw , Jiangsu Jiuding New Material , Shanghai Easpring Material Technology Co., Ltd. , TLS Technik , Rio Tinto Metal Powders / AP , Praxair / Linde , Sandvik Osprey , Carpenter Additive |
Key Technological Shifts in the Stainless Steel Powder Market:
The stainless steel powder market is going through key technological changes driven by the demand for sustainable production, purity, and efficient production. The technological advancements are the integration of IoT, sustainable manufacturing, advanced atomization techniques, automated production, and 3D printing enable smart monitoring and better quality. The key technological shift is the integration of artificial intelligence (AI) enhances the properties of material and improves the quality of the product.
AI analyzes real-time powder quality by accessing properties like size, shape, and powder yield. AI detects flagging deviations and lowers the need for manual testing. AI used to manufacture powder for advanced applications and early predicts potential failures in equipment. AI detects inconsistencies in powder and ensures the meeting of high-quality standards. AI strongly gives attention to supply chain management and accelerates research on new materials.
Trade Analysis of Stainless Steel Powder Market: Import & Export Statistics
- India imported 513 shipments of stainless steel powder.
- Vietnam exported 497 shipments of stainless steel powder.
Stainless Steel Powder Market Value Chain Analysis
- Feedstock Procurement: The feedstock procurement is sourcing raw materials like chromium, molybdenum, carbon, iron ore, nickel, silicon, and manganese.
- Key Players:- Intertek Group, SGS SA, Bureau Veritas
- Chemical Synthesis and Processing: The chemical synthesis involves methods like SHS, mechano-chemical synthesis, & chemical vapor, and chemical processing involves steps like mechanical alloying, atomization, consolidation, heat treatment & finishing.
- Key Players:- Carpenter Powder Products, Daido Steel Co., Ltd., Hoganas AB, Mitsubishi Steel, Sandvik AB
- Quality Testing and Certifications: The quality testing is testing of characteristics like powder density, moisture level, elemental composition, flow rate, particle size, integrity, resistance, surface area, & durability. The certifications, like ASTM, BIS, and ISO, are needed for stainless steel powder.
- Key Players:- Intertek Group, SGS SA, Bureau Veritas
Country-Wise Stainless Steel Powder Snapshot
| Country | Key Regulations | Majorly Used Technologies | Major Players |
| United States |
|
|
|
| India |
|
|
|
| Germany |
|
|
|
| Saudi Arabia |
|
|
|
Segmental Insights
Grade Insights
Why Austenitic Segment Dominates the Stainless Steel Powder Market?
The austenitic segment dominated the stainless steel powder market in 2025. The excellent corrosion resistance and high toughness of the austenitic grade help market growth. The manufacturing of devices like orthodontics and medical implants increases the adoption of austenitic grade. The rapid expansion of food processing and the creation of consumer electronic products require an austenitic grade. The growing use of austenitic grades like 316L and 304 drives the market growth.
The duplex & super-duplex segment is the fastest-growing in the market during the forecast period. The excellent mechanical strength and cost-effectiveness of duplex & super-duplex boost market growth. The ongoing offshore exploration and infrastructure development surge increases demand for duplex & super-duplex. The expanding chemical plants and focus on the development of longer lifespan components require duplex & super-duplex, supporting the overall market growth.
Manufacturing Process Insights
How did the Gas or Water Atomization Segment hold the Largest Share in the Stainless Steel Powder Market?
The gas or water atomization segment held the largest revenue share in the stainless steel powder market in 2025. The lower expenses of production and high scalability for mass production of water atomization boost market growth.
The increasing development of high-end coatings and a higher adoption rate of additive manufacturing increase the use of gas atomization. The growing production of large-volume stainless steel powder and focus on higher purity increases demand for gas or water atomization, driving the overall market growth.
The plasma atomization segment is experiencing the fastest growth in the market during the forecast period. The strong focus on the production of superior quality powder and the increasing use of powder in critical parts increase demand for plasma atomization. The development of aircraft parts and the increasing use of medical devices require plasma atomization for the production of high-purity stainless steel powder. The plasma atomization ability of processing high-melting-point alloys supports the overall market growth.
Application Insights
Which Application Segment Dominated the Stainless Steel Powder Market?
The additive manufacturing (AM) & powder metallurgy segment dominated the stainless steel powder market in 2025. The creation of intricate parts and an increasing focus on lowering waste generation increase the adoption of additive manufacturing. The ongoing customization of shapes and development of surgical tools create a huge demand for additive manufacturing. The design freedom, reduced waste, and rapid prototyping of additive manufacturing drive the overall growth of the market.
The metal injection molding (MIM) segment is the fastest-growing in the market during the forecast period. The increased miniaturization of electronics components and the creation of complex components for safety systems require MIM. The cost-effectiveness, high strength, and excellent durability of MIM powder boost the expansion of the market. The creation of small engine parts for cars and the increasing need for dental devices require MIM, supporting the overall growth of the market.
End-User Industry Insights
Why did the Medical & Industrial Engineering Segment hold the Largest Share in the Stainless Steel Powder Market?
The medical & industrial engineering segment held the largest revenue share in the stainless steel powder market in 2025. The growing demand for forceps & bone plates and the development of orthopedic implants create demand for stainless steel powder. The development of fluid power components and the increasing need for industrial equipment require stainless steel powder. The development of sterilizable surgical tools and the increasing need for pharmaceutical equipment require stainless steel powder, driving the overall market growth.
The aerospace & defense segment is experiencing the fastest growth in the market during the forecast period. The need to minimize aircraft weight and the development of advanced military hardware require stainless steel powder. The focus on lowering aerospace emissions and heavy investment in defense modernization requires stainless steel powder. The manufacturing of protective armor, drones, fuel systems, turbine parts, and missiles requires stainless steel powder, supporting the overall market growth.
Form Insights
How Spherical Powder Segment Dominated the Stainless Steel Powder Market?
The spherical powder segment dominated the stainless steel powder market in 2025. The superior flowability and high packing density of spherical powder boost market expansion. The compatibility of spherical powder with metal injection molding and additive manufacturing helps market growth. The increased customization of components and the increased development of medical implants require spherical powder.
The custom alloy blends & pre-alloyed powders segment is the fastest-growing in the market during the forecast period. The increasing need for heat-resistant components in the aerospace industry and the production of lightweight vehicles requires custom alloy blends. The creation of corrosion-resistant components and the production of precision parts require pre-alloyed powder. The development of battery casing, surgical tools, heat-resistant components, and fuel system parts requires custom alloy blends, supporting the overall market growth.
Regional Insights
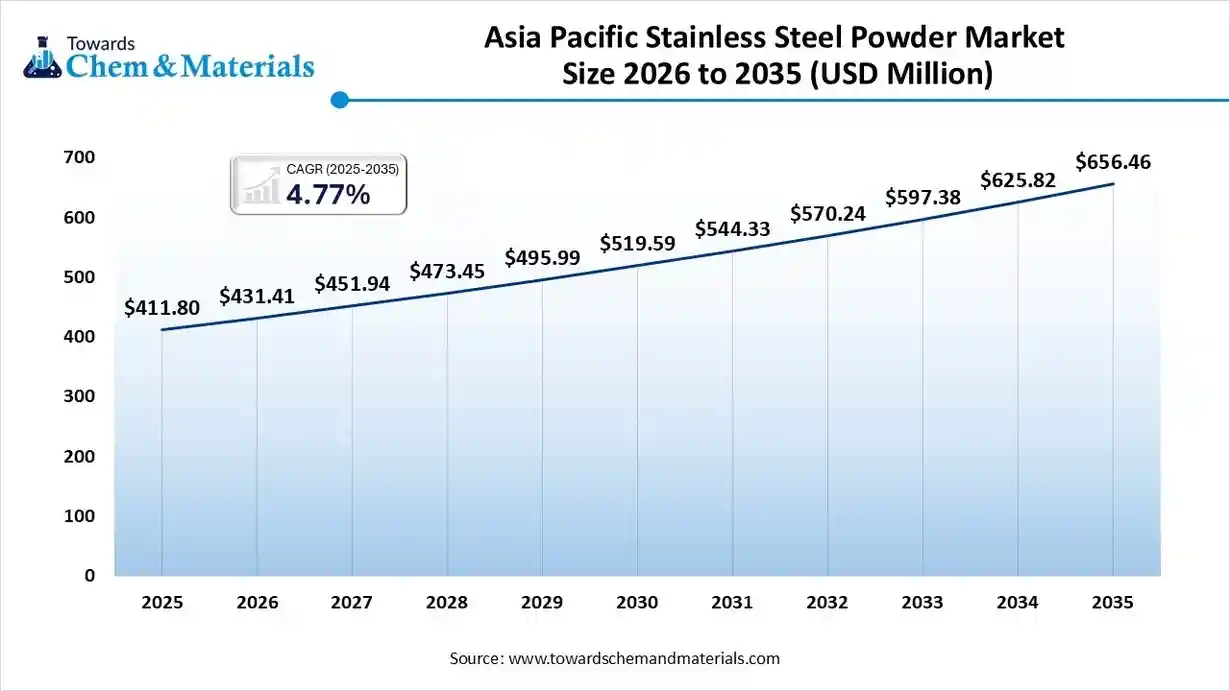
The Asia Pacific stainless steel powder market size was valued at USD 411.80 million in 2025 and is expected to surpass around USD 656.46 million by 2035, expanding at a compound annual growth rate (CAGR) of 4.77% over the forecast period from 2026 to 2035. Asia Pacific dominated the market in 2025.
The strong government backing for technologies like additive manufacturing and powder metallurgy, especially in countries like India, South Korea, and China, helps market expansion. The growing industrial activities and well-developed electronics manufacturing base increase demand for stainless steel powder. The major presence of automobile hubs and the increasing use of metal injection molding increase demand for stainless steel powder. The increasing development of rail infrastructure projects and the rise in deliveries of aircraft require stainless steel powder, driving the overall market growth.
India’s Precision: Strengthening Stainless Steel Powder Position
India is a key contributor to the market. The increased manufacturing of vehicles and the growing need for corrosion-resistant building components require stainless steel powder. The rapid growth in sectors like power and chemicals increases demand for stainless steel powder for the production of diverse equipment, tools, and machinery. The government focuses on local manufacturing, and increasing investment in stainless steel infrastructure supports the overall market growth.
North America Stainless Steel Powder Market Trends
North America is experiencing the fastest growth in the market during the forecast period. The development of lightweight aircraft parts and the higher production of biocompatible medical devices create a huge demand for stainless steel powder. The expansion of 3D printing and a strong focus on using precise components in the automotive sector increase the adoption of stainless steel powder. The rise in modern construction activities and robust expansion in the electrification of vehicles requires stainless steel powder, driving the overall market growth.
Particle Strength: Rise of Stainless Steel Powder in the United States
The United States is a major contributor to the market. The additive manufacturing surge and rise in space commercialization boost demand for stainless steel powder for the development of lightweight components and intricate designs. The electric vehicle transition and expanding defense industry require stainless steel powder. The well-established industrial and leveraging MIM support the overall market growth.
Europe Stainless Steel Powder Market Trends
Europe is growing at a notable rate in the market. The rising manufacturing of vehicles and the increasing use of lightweight parts in aircraft increase demand for stainless steel powder. The EU’s focus on sustainable production of powder and increasing investment in advanced materials fuels market expansion. The increasing development of building & construction projects and the growing medical sector increase demand for stainless steel powder.
Precision in Motion:- France Advancing Stainless Steel Powder Production
France is growing rapidly in the market. The expanding 3D printing and focus on smart manufacturing practices create a higher demand for stainless steel powder. The increasing use of advanced technologies like MIM & gas atomization boosts market growth. The focus on the creation of lightweight automotive parts and the higher production of smart devices requires stainless steel powder, supporting the overall growth of the market.
Middle East & Africa Stainless Steel Powder Market Trends
The Middle East & Africa are growing at a substantial rate in the market. The heavy investment in the development of the smart cities project and growing industrialization increase demand for stainless steel powder. The shift towards renewable energy and rapid growth in manufacturing in countries like Saudi Arabia & UAE requires stainless steel powder. The government's backing for lowering import dependency drives the overall growth of the market.
Industrial Force: Saudi Arabia's Solid Position in Stainless Steel Powder
Saudi Arabia is growing in the market. The development of water desalination infrastructure projects and the increasing use of tanks & pipelines require stainless steel powder. The increasing use of 3D printing in applications like industrial parts & medical, and government policies like NIDLP for domestic production, increases the manufacturing of stainless steel powder. The strong focus on lowering waste supports the overall market growth.
South America Stainless Steel Powder Market Trends
South America is growing substantially in the market. The transition towards 3D printing and the expansion of manufacturing capabilities create huge demand for stainless steel powder. The increased mining activities and rise in the development of energy infrastructure increase demand for stainless steel powder. The strong focus on green manufacturing and increasing demand for lightweight components requires stainless steel powder, supporting the overall market growth.
Brazil: Role in Stainless Steel Powder Excellence
Brazil is growing significantly in the market. The blooming infrastructure projects, like roads and the increasing use of heavy machinery, increase demand for stainless steel powder. The presence of raw materials like metal reserves and iron ore increases the production of stainless steel powder. The growth in utilization of additive manufacturing in sectors like aerospace, construction, and automotive drives the market growth.
Recent Developments
- In September 2025, Outokumpu launched stainless steel powder, Ultra 904L, for industrial 3D printing. It has high chromium & nickel content and is useful in components across the oil & gas & chemical industry. The powder is manufactured using inert gas atomization and vacuum induction melting.(Source: 3druck.com )
- In October 2025, EOS launched StainlessSteel 316L-4404 powder. The powder offers excellent toughness, corrosion resistance, ductility, and strength. The powder is used across industries like food production, marine, chemical processing, & water handling, and is compatible with systems like EOS M 400, EOS M 300-4, EOS M 290, & EOS M 400-4. (Source: www.voxelmatters.com)
- In June 2024, AMTEK SMP launched an innovative high green strength stainless steel powder for powder metallurgy. The powder offers greater than 50% or 50% improvement in green strength in the 400 & 300 series and minimizes production cost.(Source: www.ametekmetals.com)
Top Companies in the Stainless Steel Powder Market
- Höganäs AB:- The company leads in manufacturing metal powder using technologies like brazing, additive manufacturing, filtration, pressing & sintering, & others to serve key industries like aerospace, construction, chemicals, automotive, manufacturing, medical, & welding.
- Sandvik AB:- The Swedish company provides tools, digital technology, equipment, and services for the development of high-performance materials, stainless steels, and special alloys.
- Carpenter Technology Corporation:- The company produces high-quality specialty alloy and stainless steel powders for surface enhancement & additive manufacturing to support sectors like medical & aerospace.
- GKN Powder Metallurgy / GKN Additive:- The company manufactures metal powder solutions for the development of precision parts like structural elements, gears, and bearings.
- Daido Steel Co., Ltd.:- The company manufactures stainless steel powders like austenitic, ferritic, and martensitic using technologies like sintering & additive manufacturing to serve applications like medical, industrial, automotive, and electronics.
Other Companies List
- Höganäs AB
- Sandvik AB
- Carpenter Technology Corporation
- GKN Powder Metallurgy / GKN Additive
- Daido Steel Co., Ltd
- ATI Powder Metals
- AP&C
- LPW Technology
- Oerlikon AM
- CNPC Powder Material Co., Ltd.
- EOS
- Renishaw
- Jiangsu Jiuding New Material
- Shanghai Easpring Material Technology Co., Ltd.
- TLS Technik
- Rio Tinto Metal Powders / AP
- Praxair / Linde
- Sandvik Osprey
- Carpenter Additive
Segments Covered
By Grade / Type
- Austenitic
- Martensitic
- Ferritic
- Duplex & Super-duplex
- Precipitation-hardening (PH) stainless steels
By Manufacturing Process
- Gas / Water Atomization
- Plasma Atomization
- Mechanical Milling / Reduction
- Electrolytic / Chemical routes
By Application / End-Use
- Additive Manufacturing (AM / Metal 3D Printing) & Powder Metallurgy
- Metal Injection Molding (MIM)
- Thermal Spray & Coatings
- Cold / Hot Isostatic Pressing (CIP / HIP) parts
- Others (binder-jet printing, specialty sintered components)
By End-User Industry
- Medical (implants, surgical instruments) & Industrial Engineering
- Automotive (lightweight, complex components)
- Aerospace & Defense
- Energy & Power
- Electronics & Consumer Goods
By Form / Product
- Spherical Powder
- Irregular / atomized flakes
- Custom alloy blends, pre-alloyed powders
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.