Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The global bimodal HDPE market size was valued at USD 11.85 billion in 2025, is estimated to reach USD 12.65 billion in 2026, and is projected to reach USD 22.77 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 6.75% over the forecast period from 2026 to 2035.Asia Pacific dominated the bimodal HDPE market with the largest revenue share of 43% in 2025 and is expected to grow at the fastest CAGR of 6.86% during the forecast period. In terms of volume, the bimodal HDPE market is projected to grow from 7.15 million tons in 2025 to 12.99 million tons by 2035. growing at a CAGR of 6.15% from 2026 to 2035. The increasing need for durable municipal pipelines is the key factor in driving market growth. Also, ongoing infrastructure modernization coupled with the increasing need for robust intermediate bulk containers (IBCs) can fuel market growth further. Moreover, rapid innovations in catalyst technology will likely drive market growth soon.

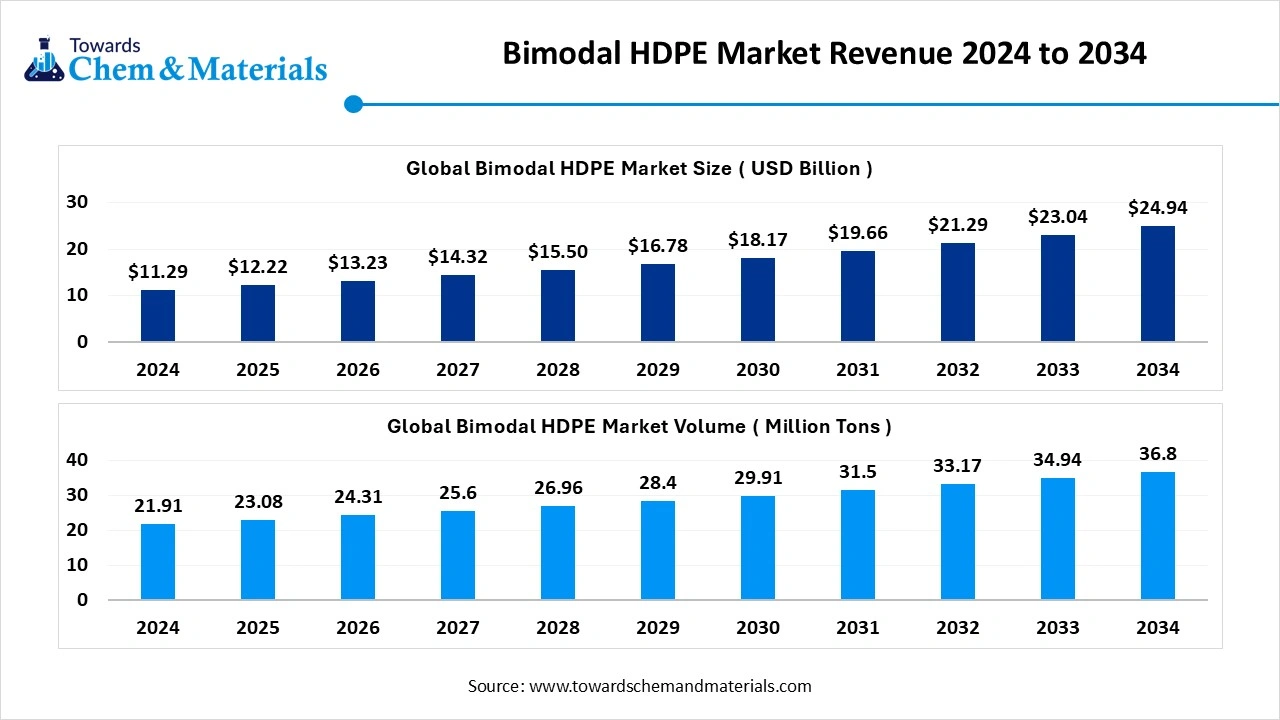
A surge in infrastructure investments for gas, water, and sewage systems is presenting crucial opportunities in the market. Its durability and strength over time are necessary for the HDPE pipe sector. In addition, demand for durable piping materials has increased due to heavy investments in the Infrastructure and Jobs Act.
Recyclable and sustainable materials such as HDPE are increasingly gaining traction due to stringent global environmental regulations.
The global investment flow for the market is generally defined by sustainability upgrades, regional supply chain realignments, and infrastructure developments.
Capital investments by major market players including Dow, Braskem, SABIC, and INEOS are flowing into certain bimodal formulations to fulfill high-demand sectors.
| Report Attributes | Details |
| Market Size in 2026 | USD 12.65 Billion/ 7.59 Million Tons |
| Expected Market Size by 2035 | USD 22.77 Billion/ 12.99 Million Tons |
| Growth Rate from 2025 to 2035 | CAGR 6.75% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Processing Method, By Application, By Regions |
| Key Companies Profiled | INEOS Group AG, SABIC, LyondellBasell Industries N.V., Dow Inc. (USA), Exxon Mobil Corporation, Dynalab Corp., LyondellBasell Industries N.V., INEOS AG, SINOPEC Beijing Yanshan Company, PetroChina Company Ltd., Braskem S.A., Formosa Plastics Corporation, Daelim Industrial Co., Ltd., Mitsui Chemicals Inc |
AI-powered predictive formulations are revolutionizing the market by using machine learning (ML) to surpass slow and traditional trial-and-error chemical formulation methods. Furthermore, by integrating AI, market players can conveniently co-optimize the high-molecular-weight fraction and low-molecular-weight fraction along with environmental stress.
| Country/Region | Key Regulations |
| European Union (EU) | Food Contact Materials (Regulation EU No 10/2011): Establishes strict specific migration limits (SML) for plastic additives used in bimodal blow-molded packaging. Recent traceability standards mandate comprehensive tracking for food-contact plastics. |
| United States (US) | Food and Drug Administration (US FDA): Bimodal resins must satisfy 21 CFR 177.1520 (olefin polymers) specifications, detailing permissible catalyst residues and density levels for food-grade packaging. |
| China | Infrastructure Pipe Standardization: The National Standard GB/T 13663 regulates polyethylene piping for water supply. Bimodal resins must meet top-tier PE100 classifications to withstand heavy geological stress in municipal grids. |
Increasing Shift Towards Customized Resin Grades
The ongoing transition towards customized resin grades created specifically for targeted applications is the major factor in driving market growth. Resin market players are rapidly adopting innovative polymerization and catalyst technologies to fine-tune proper molecular-weight distributions, allowing overall performance enhancements. In addition, this trend enables manufacturers to tailor materials for exact functional requirements, including achieving long-term durability in piping systems and thin-wall structural integrity in blow-molded containers.
Environmental Regulatory Compliance
Stringent global mandates for post-consumer recycled (PCR) plastics impel major players to invest heavily in innovative mechanical or chemical recycling loops, which is the major factor hindering market growth. Moreover, major manufacturers continuously struggle to incorporate recycled materials into bimodal matrices while preserving the resins high environmental stress-crack resistance (ESCR).
Expanding Automotive Sector
The ongoing urbanization and surge in the automotive sector in different regions increase demand for bimodal HDPE, creating lucrative opportunities in the market. The emphasis on minimizing the weight of vehicles and improving the overall fuel efficiency of vehicles grows the need for bimodal HDPE. The rising production of electric vehicles (EVs) and under-the-hood components is driving a surge in demand for bimodal HDPE. Furthermore, the escalating complexity in manufacturing automotive components, such as fluid systems and air ducts, is driving increased demand for bimodal high-density polyethylene (HDPE).
The extrusion segment dominated the market with the largest share of 58% in 2025. Bimodal grades integrate short molecular chains for easy processing with long chains that offer excellent environmental stress crack resistance (ESCR) and creep resistance. The superior mechanical strength of bimodal resins enables a 15–20% reduction in material thickness without compromising puncture resistance. This allows manufacturers to achieve stringent sustainability targets and lightweight objectives. In addition, significant municipal funding directed toward replacing aging metallic water infrastructure across North America, the Middle East, and the Asia-Pacific continues to generate sustained, large-scale demand for pipeline extrusion.
 The compression molding segment held a market share of 7.0% in 2025 and is expected to grow at the fastest CAGR of 7.40% over the forecast period. Compression-molded parts using biomodal resins give superior resistance to cracking under harsh chemical exposure and harsh environments. Bimodal resins enable market players to manufacture lighter components with thinner walls without compromising impact resistance and structural integrity. Furthermore, the growing adoption of automated, high-speed continuous compression molding (CCM) rotary machines eliminates the thermal degradation risks associated with traditional extrusion, yielding superior final products with minimal volatile residue.
Bimodal HDPE Market Share,By Processing Method, 2025 (%)
| By Processing Method | Revenue Share, 2025 (%) |
| Extrusion | 58% |
| Blow Molding | 20% |
| Injection Molding | 15% |
| Compression Molding | 7% |
The packaging segment dominated the market with the largest share of 41% in 2025. Because of their long-term durability and high environmental stress-crack resistance (ESCR). Bimodal high-density polyethylene (HDPE) represents the major industry standard for large-scale industrial packaging and ensures the secure containment of volatile chemicals, paints, lubricants, and petroleum derivatives. Moreover, this material is extensively used in both blown and extruded film formats. Its bimodal molecular structure provides superior tensile strength and puncture resistance, which makes it highly suitable for retail carrier bags, food packaging, pallet wrapping, and heavy-duty industrial liners. Bimodal HDPE offers the precise dimensional stability and torque retention necessary for leak-proof bottle caps.
 The automotive segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 7.60% during the projected period. Bimodal HDPE offers a key strength-to-weight ratio, high chemical resistance (essential for fuel systems), and exceptional structural reliability as compared to other polymers. Furthermore, to mitigate the inherent mass of electric vehicle (EV) battery systems and comply with strict international emissions regulations, Original Equipment Manufacturers (OEMs) are increasingly replacing traditional metallic structural components with advanced bimodal polymer composites. Leading global chemical producers, including Borealis AG, Dow Inc., SABIC, and ExxonMobil, are actively developing and optimizing automotive-grade bimodal resin formulations, leading to segment growth soon.
Bimodal HDPE Market Share,By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Packaging | 41% |
| Automotive | 24% |
| Electronics & Electrical (E&E) | 9% |
| Construction | 18% |
| Other Applications | 8% |
How did Asia Pacific Dominated the Bimodal HDPE Market in 2025?
The Asia Pacific bimodal HDPE market size was estimated at USD 5.10 billion in 2025 and is projected to reach USD 9.90 billion by 2035, growing at a CAGR of 6.86% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 43.0% in 2025. The dominance of the segment can be attributed to the growing demand for high-performance and sustainable packaging materials along with extensive infrastructure investments. In addition, increasing regulatory requirements for sustainability and extended producer responsibility (EPR) frameworks are driving industries to adopt environmentally conscious mono-material packaging solutions.
 China
India
The North America bimodal HDPE market size was estimated at USD 2.13 billion in 2025 and is projected to reach USD 4.21 billion by 2035, growing at a CAGR of 7.05% from 2026 to 2035.North America held a market share of 18.00% in 2025 and was expected to grow at the fastest CAGR of 7.80% over the forecast period. The growth of the region can be credited to the ongoing innovations in catalyst design and polymerization techniques that enable manufacturers to control molecular weight distribution. Also, bimodal high-density polyethylene (HDPE) is widely used in the production of blow-molded containers, closures, and storage vessels for food and chemical applications. Due to its dual-molecular weight structure, this material offers superior mechanical strength.
United States
Canada
The Europe bimodal HDPE market size was estimated at USD 2.84 billion in 2025 and is projected to reach USD 5.58 billion by 2035, growing at a CAGR of 6.99% from 2026 to 2035.Europe held a market share of 24.00% in 2025. The growth of the region can be credited to the rigorous European Union for sustainability mandates, substantial investments in aging pipeline infrastructure, and a surging demand for lightweight, high-performance packaging. Also, Europe leverages sophisticated polymer processing infrastructure and strong research and development frameworks driven by prominent market players, including SABIC and LyondellBasell.
Germany
France
The Latin America bimodal HDPE market size was estimated at USD 0.83 billion in 2025 and is projected to reach USD 1.71 billion by 2035, growing at a CAGR of 7.50% from 2026 to 2035.Latin America held a market share of 7.00% in 2025. The growth of the region can be driven by substantial capital investments in water supply infrastructure, government-supported housing, and sanitation initiatives, coupled with the augmentation of domestic manufacturing capabilities. In addition, leading regional petrochemical producers, including Braskem S.A., are expanding their domestic manufacturing capacities, hence enhancing local supply chains and mitigating dependence on imports.

Brazil
Argentina
The Middle East and Africa bimodal HDPE market size was estimated at USD 0.95 billion in 2025 and is projected to reach USD 1.94 billion by 2035, growing at a CAGR of 7.40% from 2026 to 2035.The Middle East & Africa held a market share of 8.00% in 2025. The growth of the region can be attributed to the rapid regional expansion, extensive investments in infrastructure, and the ongoing proliferation of the industrial packaging sector, along with the ambitious construction initiatives across key global markets, including Saudi Arabia, the United Arab Emirates, and South Africa. Furthermore, African nations are substantially investing in agricultural irrigation and sanitation infrastructure, where durable High-Density Polyethylene (HDPE) pipes serve as a cost-effective and corrosion-resistant alternative to conventional steel.
Bimodal HDPE Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| North America | 18% |
| Europe | 24% |
| Asia-Pacific | 43% |
| Latin America | 7% |
| Middle East & Africa | 8% |
Saudi Arabia
UAE
The global market exhibits a moderately concentrated and highly competitive landscape, led by a few major chemical and petrochemical players. These industry giants are heavily investing in extensive manufacturing capabilities and advanced catalyst developments to enhance processing properties.
| Company | Company Type/Position | Headquarters | Geographic Presence | Offerings | Key Offering/Strength |
| Dow Inc. (USA) | Top-tier multinational chemical and material science leader. | Midland, Michigan, USA | Massive global footprint with manufacturing sites across North America, Europe, Asia-Pacific, and Latin America. | Dow predominantly focuses on polyolefins (PE, PP) rather than pure Polyamide production, but they manufacture specialty compatibilizers and modifiers used to blend Polyamide with other polymers. | CONTINUUM™ Bimodal Polyethylene Resins. They provide extreme environmental stress-crack resistance (ESCR) and long-term hoop strength for high-pressure gas/water pipelines |
| LyondellBasell Industries N.V. | One of the world’s largest plastics, chemicals, and refining companies | Rotterdam, Netherlands | Over 30 countries worldwide, with a heavy manufacturing presence in Europe and North America. | Primarily focused on polyolefins; however, their engineered plastics division produces specialized compounds that compete with or modify high-performance nylons. | Hostalen ACP technology. Widely considered the gold standard for high-performance bimodal HD |
| SABIC | Public petrochemical global pioneer, majority-owned by Saudi Aramco. | Riyadh, Saudi Arabia. | Operations in over 50 countries, leveraging low-cost Middle Eastern feedstock while managing massive supply hubs in Europe, the Americas, and Asia. | Strong specialty plastics portfolio. SABIC produces high-performance Polyamide (PA6 and PA66) compounds through its specialties arm, tailored for extreme heat loops in automotive engines. | Advanced bimodal blow-molding resins designed for lightweight packaging and industrial containers, offering superior processing stability. |
| INEOS Group AG | Privately owned global chemical giant | London, United Kingdom. | Heavily integrated across Europe and North America, with rapidly growing joint ventures and assets in Asia and the GCC. | In addition to being an absolute titan in polyolefins, INEOS produces key chemical intermediates utilized in global nylon production chains. | Large-scale production of specialized bimodal HDPE grades optimized for caps, closures, and heavy-duty industrial blow molding. |

By Processing Method
By Application
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo