Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The global vapor barrier market size was valued at USD 15.87 billion in 2025, is estimated to reach USD 16.97 billion in 2026, and is projected to reach USD 30.99 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 6.92% over the forecast period from 2026 to 2035.Asia Pacific dominated the vapor barrier market with the largest revenue share of 40% in 2025 and is expected to grow at the fastest CAGR of 7.05% during the forecast period. As the percentage of sustainable construction grows, the building codes are tighter, and attention is being paid to buildings becoming more energy-efficient, the number of retrofit projects has been increasing, as has awareness of indoor air quality and mold prevention. Advanced solutions for vapor barrier use are further gaining traction in emerging economies due to the speed of urbanisation and infrastructure development.
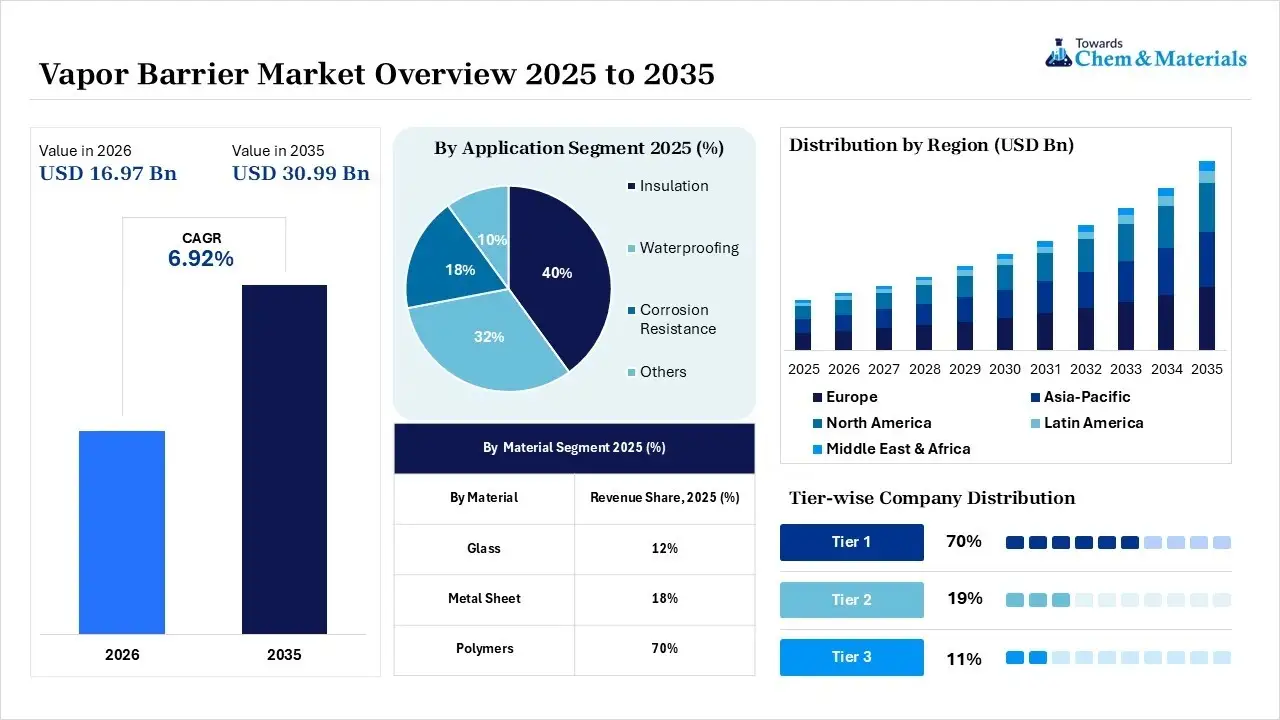
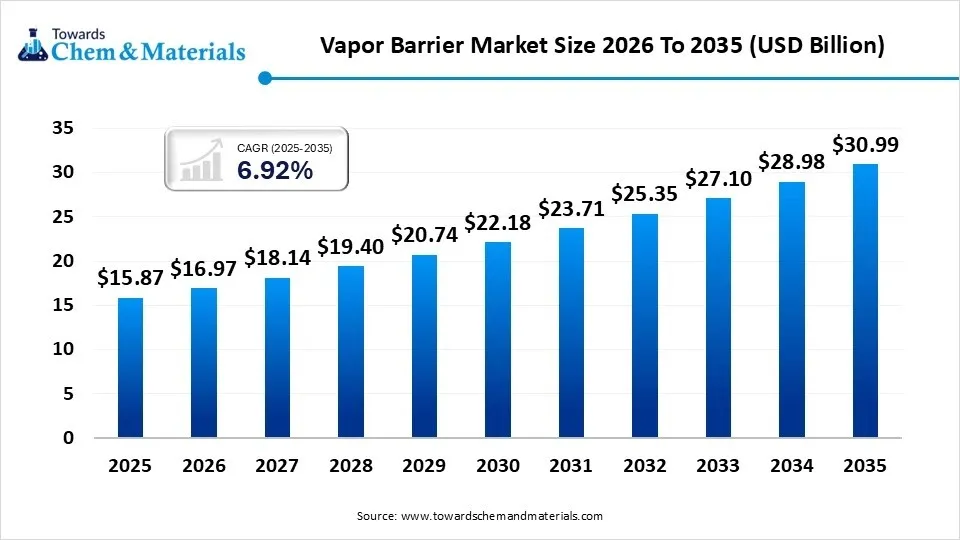
As builders and developers become more interested in energy efficiency, moisture control, and sustainable building practices, the vapor barrier market continues to grow steadily. Advanced vapor control solutions are being used to improve insulation performance and eliminate moisture damage to structures, all in response to strict building codes and green building standards.
There are also fresh growth prospects in the growing retrofit market, increasing construction industry, and the demand for specialized facilities like data centres, cold storage centres, and pharmaceutical manufacturing plants. The industry is undergoing significant changes due to technological innovations such as smart vapor retarders and bio-based membrane solutions, enhancing building performance and sustainability.
| Report Attributes | Details |
| Market Size in 2025 | USD 15.66 Billion |
| Expected Size By 2034 | USD 25.22 Billion |
| Growth Rate from 2025 to 2034 | CAGR 5.44% |
| Base Year of Estimation | 2024 |
| Forecast Period | 2025-2034 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Material, By Application, By Installation, By End Use , By Region |
| Key Companies Profiled | Glenroy Inc., Celplast Metallized Product Ltd., Polifilm Group, ProAmpac Holdings, Optimum Plastics, Inc., 3M Company, Amcor Limited, SAES Getters S.p.A., Kalliomuovi Oy, GLT Products, UFP Industries, Inc., W.R. Meadows, Inc., BMI Icopal, Carlisle Companies Inc. |
Feedstock Procurement
Chemical Synthesis and Processing
Compound Formulation and Blending
One of the major opportunities contributing to the growth of the vapor barrier market is the growing and rapid expansion of the construction industry in the emerging economies, where they are experiencing accelerated urbanization and infrastructural development, leading to increased demand for moisture control solutions in residential, commercial, and industrial buildings. The initiatives, such as the smart city mission and substantial investment in infrastructure development, further boost the demand and growth of the market. The regions with humid conditions require and demand efficient moisture management to prevent structural damage and health hazards, which increases demand
The vapor barrier market has a key challenge that hinders the growth of the market in the developing region, especially the lack of awareness and inconsistent installation practices. Many builders and contractors overlook the importance of or have poor installation techniques, which leads to reduced effectiveness. Additionally, the selection of inappropriate barrier materials for specific climate conditions results in poor results, and limited availability of skilled labor and lack of training also result in poor performance, which results in less growth and is a challenge to overcome.
The polymer segment dominated the vapor barrier market share 70% in 2025. The polymer segment holds a significant share in the market due to its versatility, durability, and cost-effectiveness, which increases the demand for the market. Polymers such as polyethylene, polypropylene, and polyvinyl chloride (PVC) are widely used since they offer excellent moisture resistance and can be easily manufactured into sheets or films. These materials are lightweight, flexible, and suitable for various applications in construction, especially in insulation and under-slab installations, making them a preferred choice for builders and contractors, which increases the demand for the market.
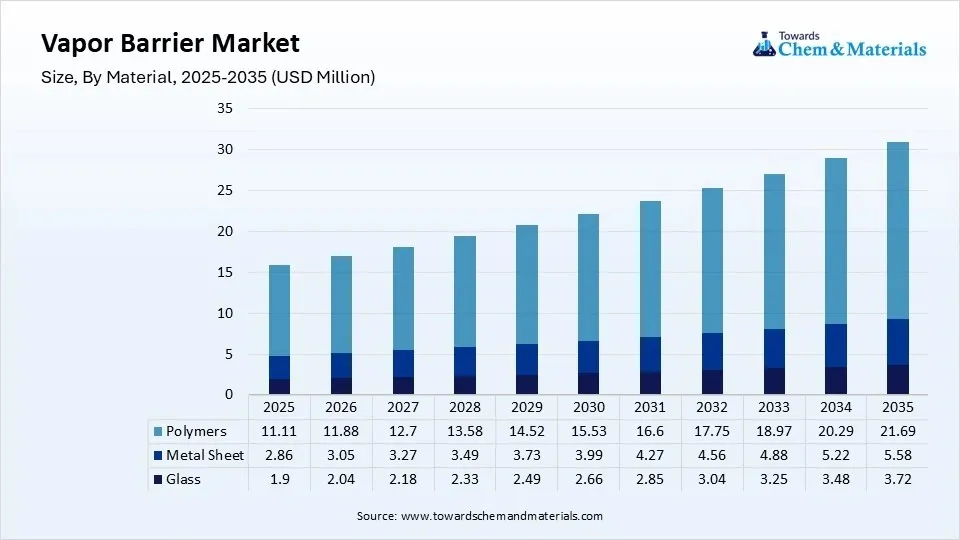
The metal sheet segment expects significant growth in the vapor barrier market during the forecast period. The metal sheet segment in the market is valued for its high strength, durability, and superior resistance to vapor transmission. Typically made from materials like aluminum or galvanized steel, these sheets are used in industrial and commercial buildings where long-term protection and fire resistance are critical. Although heavier and more expensive than polymer options, metal sheets are ideal for harsh environments and are often chosen for roofing and specialized wall applications requiring robust moisture control, which increases the demand and helps in the growth of the market.
The insulation segment dominated the vapor barrier market share 40% in 2025. The insulation segment is a major application area for vapor barriers, as controlling moisture is essential to maintaining the effectiveness of thermal insulation. Vapor barriers are typically installed on the warm side of insulation in walls, roofs, and floors to prevent condensation that can degrade insulating materials and lead to mold growth.
This application improves energy efficiency, indoor comfort, and building longevity, making it a critical component in both residential and commercial construction. The waterproofing segment expects significant growth in the vapor barrier market during the forecast period. In the waterproofing segment, vapor barriers play a vital role in protecting structures from moisture intrusion, especially in basements, foundations, and roofing systems.
These barriers act as a seal to prevent water vapor from penetrating building envelopes, which can lead to structural damage, corrosion, and mold formation. Used alongside other waterproofing materials, vapor barriers enhance the overall moisture management system, ensuring building integrity and longevity in both new construction and renovation projects.
The membranes segment dominated the vapor barrier market in 2024. The membranes segment is a widely used installation type in the market due to its flexibility, ease of application, and reliable performance. These barriers are typically made from polyethylene, bituminous materials, or synthetic polymers and are applied as sheets or rolls.
Membrane vapor barriers are ideal for roofing, walls, and under-slab installations, offering consistent coverage and resistance to moisture penetration. Their adaptability to various surfaces makes them a preferred choice in modern construction practices. The cementitious segment expects significant growth in the vapor barrier market during the forecast period. The cementitious segment includes vapor barriers made from cement-based coatings that are applied to concrete surfaces to block moisture penetration.
These barriers are especially suited for basements, foundations, and water-retaining structures due to their strong adhesion, durability, and compatibility with masonry substrates. Cementitious vapor barriers are easy to apply and offer excellent resistance to hydrostatic pressure, making them a popular choice for both new constructions and repair projects in high-moisture environments.
The construction segment dominated the vapor barrier market in 2025. The construction sector represents the largest end-use for vapor barriers, encompassing residential, commercial, and industrial building projects. Demand is driven by stringent building codes, growing emphasis on energy efficiency, and moisture control in new construction and renovation. Vapor barriers in walls, roofs, floors, and foundations prevent condensation, protect components, and extend building lifespan. Retrofit projects further boost adoption as older buildings are upgraded for improved thermal performance and indoor air quality.
The automotive segment expects significant growth in the vapor barrier market during the forecast period. In the automotive segment, vapor barriers are used to protect the interior part of the vehicle and components from moisture, particularly in doors, roofs, and electric battery compartments for EVs, which drives the growth. Polymer-based films and adhesives are applied to prevent the vehicle from corrosion, mold, and electrical failures. Precision in thickness and compatibility with paints and trim is critical. Growing electric vehicle adoption increases the demand for advanced moisture management to ensure safety, reliability, and extended component life, which drives the growth of the market.
How did the Asia Pacific dominate the Vapor Barrier Market in 2025?
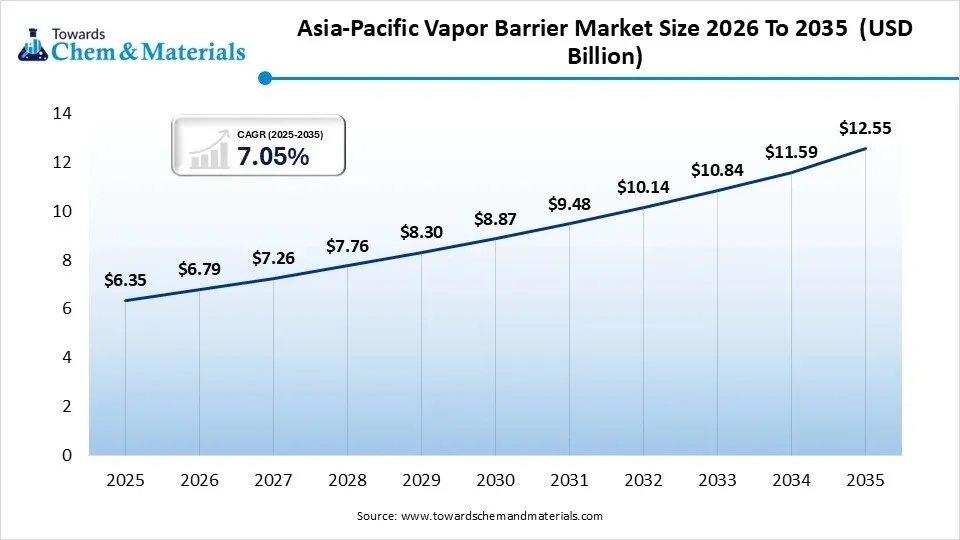
The Asia Pacific vapor barrier market size was estimated at USD 6.35 billion in 2025 and is projected to reach USD 12.55 billion by 2035, growing at a CAGR of 7.05% from 2026 to 2035.Asia Pacific dominated the market with 40% share in 2025, as the region saw a significant volume of both residential and commercial construction activity, especially in high-humidity regions where moisture control is important for the durability of buildings. Demand for vapor barrier membranes increased further throughout the region with the growing use of an energy-efficient building envelope, increased investment in cold storage buildings, and the rapid development of urban infrastructure.
 China
India
North America held 25% market share in 2025 and is expected to grow at the fastest CAGR of 6.2% during the forecast period, as strict building energy codes, broad building retrofit projects, and the building focus on indoor air quality continued. The market grew across the region due to the rise of the use of encapsulated crawl spaces, high-tech insulation systems, and moisture-management techniques in homes and commercial structures.
United States
Canada
Europe held 22% market share in 2025. Energy-efficiency requirements, the need to renovate old buildings, and a high sustainable construction adoption rate were the reasons behind the growth of the market for the vapor barriers. As builders sought to balance moisture control with building envelope performance, smart vapor retarders and breathable membrane technologies met greater demand.
Germany
France
Latin America held 7% market share in 2025, as residential construction expanded, awareness of moisture issues leading to structural damage increased, and the number of commercial construction projects rose. In areas with high humidity levels, demand for moisture control systems was especially high, as moisture control is crucial to maintaining building integrity and comfort for occupants.
Brazil
Chile
The Middle East & Africa held 6% market share in 2025, due to rising investments in commercial infrastructure, massive urban development, and the use of modern building technologies, which supported the growth of this market. The demand for vapor barriers was encouraged because they were needed to guard against moisture penetration of insulation and to improve energy efficiency in extreme weather.
Saudi Arabia
South Africa

By Material
By Application
By Installation
By End-Use
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo