
U.S. Mirror Coatings Market Size, Competitive Landscape Analysis Report 2035
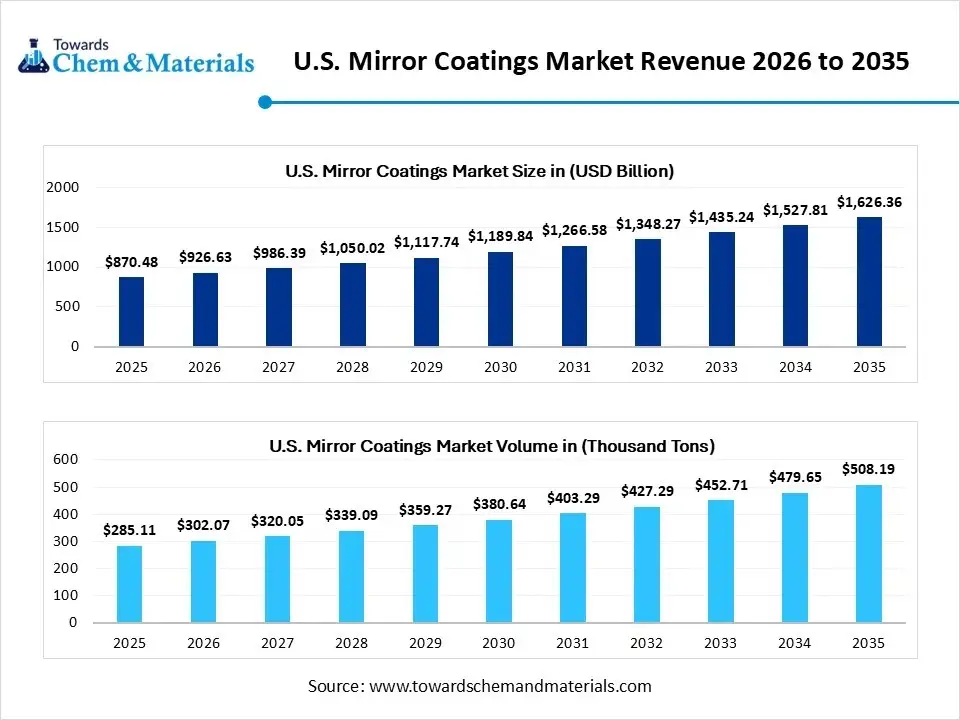
The U.S. mirror coatings market size was estimated at USD 870.48 billion in 2025 and is expected to increase from USD 926.63 billion in 2026 to USD 1,626.36 billion by 2035, growing at a CAGR of 6.45% from 2026 to 2035. In terms of volume, the market is projected to grow from 285.11 thousand tons in 2025 to 508.19 thousand tons tons by 2035. growing at a CAGR of 5.95% from 2026 to 2035. The growth of the market is driven by the growing demand from various industries due to rapid industrialization, such as construction, automotive, solar energy growth, and environmental regulations, which support the growth of the market.
Key Takeaway
- By coating materials, the silver-based coatings segment dominated the market in 2024. The silver-based coatings segment held a 40% share in the market in 2024. Their superior reflectivity and widespread use in decorative, architectural, and automotive applications increase the demand.
- By coating material, the dielectric coatings segment is expected to grow significantly in the market during the forecast period. These coatings offer durability, scratch resistance, and the ability to selectively reflect specific wavelengths of light.
- By deposition technology, the magnetron sputtering segment dominated the market in 2024. The magnetron sputtering segment held a 36% share in the market in 2024. It is favored for architectural glass, automotive mirrors, and specialty electronics.
- By deposition technology, the roll-to-roll vacuum coating segment is expected to grow in the forecast period. This method is critical for lightweight and flexible mirror solutions used in various applications.
- By substrate type, the glass substrates segment dominated the market in 2024. The glass substrates segment held a 55% share in the market in 2024. Their stability, durability, and ability to hold high-quality reflective coatings make them ideal for application.
- By substrate type, the plastic substrates segment is expected to grow in the forecast period. They are particularly suited for automotive, aerospace, and consumer electronics applications
- By product form, the flat mirror panels/sheets segment dominated the market in 2024. The flat mirror panels/sheets segment held a 46% share in the market in 2024. They provide durable, high-quality reflectivity for residential, commercial, and industrial uses
- By product form, the mirror films / metallized films segment is expected to grow in the forecast period. Roll-to-roll vacuum processes allow efficient large-scale production, making these films cost-effective
- By end-use industry, the architectural & construction segment dominated the market in 2024. The architectural & construction segment held a 29% share in the market in 2024. Demand is driven by residential and commercial projects.
- By end-use industry, the solar energy segment is expected to grow in the forecast period. Coated mirrors are critical in concentrating solar power (CSP) systems, enabling efficient energy capture and conversion.
- By distribution channel, the glass fabricators & processors segment dominated the market in 2024. The glass fabricators & processors segment held a 38% share in the market in 2024. They customize and process coated glass panels to meet specific requirements
- By distribution channel, the OEM supply (automotive & smart devices) segment is expected to grow in the forecast period. OEM demand in the US is rising due to the growing use of reflective and smart mirror technologies.
Market Overview
Title- Rising Demand For Durable Materials: U.S. Mirror Coatings Market To Expand
Mirror coatings are thin-film or metallic layers applied to substrates (glass, plastics, metal, or film) to create reflective surfaces. They include metallic silvering/aluminizing, dielectric multilayers, and hybrid systems applied via wet-chemical or vacuum deposition processes to meet optical, decorative, protective, and functional requirements across architectural, automotive, industrial, optical, and consumer applications.
What Are The Key Growth Drivers That Support The Growth Of the U.S. Mirror Coatings Market?
The growth of the market is driven by the growing and rapid industrialization, especially the growing demand from the construction sector due to growing activities resulting from the growing population, which fuels the growth of the market.
The booming automotive sector and demand for mirror coating for improving visibility, sensor function in electric and autonomous vehicles, and also to improve aesthetics, drive the demand for the market. The growth in solar energy due to the expansion of concentrated solar power systems and solar farms demands high-reflectivity coated mirrors to enhance efficiency and support renewable energy goals, fueling the growth and expansion of the market.
Market Trends
- Eco-Friendly Coatings: A significant trend is the development and adoption of environmentally friendly, water-based coatings as manufacturers respond to regulatory pressures and consumer demand for sustainable products.
- Application Segmentation: The architectural segment is a major contributor, but significant growth is also seen in automotive, decorative, and electronics applications.
- Regional Growth: The market is seeing robust growth across various regions, with strong demand in industrial hubs like the Midwest due to the presence of automotive, construction, and manufacturing sectors.
- Research & Development: Market participants are heavily investing in R&D to develop cutting-edge mirror coatings that offer enhanced energy efficiency, anti-reflective properties, and superior durability.
Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 194.65 Million |
| Expected Size by 2034 | USD 304.83 Million |
| Growth Rate from 2025 to 2034 | CAGR 5.11% |
| Base Year of Estimation | 2024 |
| Forecast Period | 2025 - 2034 |
| Segment Covered | By Coating Material, By Deposition Technology, By Substrate Type, By Product Form, By End-Use Industry, By Distribution Channel |
| Key Companies Profiled | The Sherwin-Williams Company, Dynasil Corporation, Ferro Corporation, North American Coating Laboratories, Reynard Corporation, Abrisa Technologies, AccuCoat Inc., Sterling Precision Optics Inc., D & W, Inc., Glass & Mirror Outlet, Ever Better Mirror, Maryland Glass & Mirror Company, Wholesale Glass & Mirror Manufacturer, Lenoir Mirror Company, Avalon Glass and Mirror Manufacturer, Majestic Mirror & Frame Manufacturer, Fab Glass and Mirror Company, Virginia Mirror Company, Guardian Glass, Cardinal Glass Industries |
Market Opportunity
Strong Emphasis On Sustainability And Technological Advancements Are The Key Growth Opportunities That Support The Growth Of The U.S. Mirror Coatings Market.
The key opportunity that supports the growth of the market is the technological advancements and environmental regulations. Innovations in high-performance coatings, including nanotechnology and smart glass technologies, improve reflectivity, durability, UV resistance, and anti-fog properties.
The integration of Artificial Intelligence and IoT in manufacturing processes also contributes to efficiency and innovation. Regulatory frameworks, such as EPA standards on VOCs, encourage the development of eco-friendly, low-emission coatings. Initiatives like LEED certification and federal sustainability programs also stimulate demand for green building materials, including specialized mirror coatings, creating opportunities for the growth and expansion of the market.
Market Challenge
Regulatory Compliance And Raw Material Volatility Hinder The Growth Of The U.S. Mirror Coatings Market.
The key challenges, such as raw material volatility, Prices for key materials like silver, aluminum, and glass are subject to global supply chain issues, energy market fluctuations, and trade policies, directly impacting production costs and profitability.
Developing high-performance mirror coatings necessitates premium raw materials, specialized manufacturing technologies, and skilled expertise, leading to elevated production expenses. U.S. environmental regulations, such as those from the EPA, restrict the use of certain chemicals and require reductions in Volatile Organic Compounds (VOCs), increasing production complexity, formulation costs, and the need for R&D into eco-friendly alternatives. These factors restrict the growth and expansion of the market.
Regional Insights
U.S. Mirror Coatings Market Value Chain Analysis
- Chemical Synthesis and Processing: The mirror coatings are processed by chemical deposition, vacuum deposition, and dielectric coating..
Key players: Guardian Glass, AGC Inc., Fenzi S.p.A., and Saint-Gobain - Quality Testing and Certification: The mirror coatings require Quality Management System (QMS) certifications and Industry-specific performance standards.
- Key players: ABS Quality Evaluations, Inc., American Systems Registrar (ASR), and Eagle Registrations Inc.
- Distribution to Industrial Users: The mirror coatings are distributed to the solar power, automotive, electronics, medical devices, and construction industries.
- Key players: Guardian Glass, AGC Inc., Fenzi S.p.A., and Saint-Gobain.
Segmental Insights
Coating Material
How Did The Based Coatings Segment Dominate The U.S. Mirror Coatings Market In 2024?
The silver-based coatings segment dominated the U.S. mirror coatings market in 2024. Silver-based coatings dominate the US mirror coatings market due to their superior reflectivity and widespread use in decorative, architectural, and automotive applications. Their ability to provide high-quality optical performance makes them a preferred choice for both functional and aesthetic purposes. However, manufacturers are increasingly focusing on advanced protective layers to enhance durability and resistance to corrosion, ensuring long-term performance in both interior and exterior applications.
The dielectric coatings segment expects significant growth in the U.S. mirror coatings market during the forecast period. Dielectric coatings are gaining traction in the US market, particularly in high-performance and specialty applications such as smart mirrors, solar concentrators, and precision optics. These coatings offer durability, scratch resistance, and the ability to selectively reflect specific wavelengths of light. Their role is expanding with the rise of smart devices and renewable energy, where advanced optical coatings are essential. Growing R&D investments are driving innovation in dielectric mirror coating technologies.
Deposition Technology
Which Deposition Technology Segment Dominated The U.S. Mirror Coatings Market In 2024?
The magnetron sputtering segment dominated the U.S. mirror coatings market in 2024. Magnetron sputtering is a widely adopted deposition method in the US mirror coatings market, especially for high-quality, uniform, and durable coatings. It is favored for architectural glass, automotive mirrors, and specialty electronics due to its precision and scalability. The technique supports both silver and dielectric coatings, allowing manufacturers to cater to diverse industry needs. Its ability to deliver consistent optical performance makes it integral to premium-grade mirror production.
The roll-to-roll vacuum coating segment expects significant growth in the U.S. mirror coatings market during the forecast period. Roll-to-roll vacuum coating is increasingly used for mirror films and metallized products in the US, offering cost-effectiveness and suitability for large-scale production. This method is critical for lightweight and flexible mirror solutions used in automotive interiors, consumer electronics, and decorative applications. Its efficiency in handling plastic substrates has further expanded its adoption. The growing demand for innovative and flexible reflective products is boosting roll-to-roll vacuum coating technology in the US.
Substrate Type
How Did the Glass Substrates Segment Dominated The U.S. Mirror Coatings Market In 2024?
The glass substrates segment dominated the U.S. mirror coatings market in 2024. Glass substrates remain the primary choice for mirror coatings in the US, driven by their use in architectural, construction, and automotive applications. Their stability, durability, and ability to hold high-quality reflective coatings make them ideal for traditional flat panels and specialty optical mirrors. With rising construction activity and modernization of residential and commercial spaces, glass-based mirrors continue to dominate the substrate segment of the market.
The plastic substrates segment expects significant growth in the U.S. mirror coatings market during the forecast period. Plastic substrates are witnessing increasing adoption in the US mirror coatings market due to their lightweight, flexible, and impact-resistant properties. They are particularly suited for automotive, aerospace, and consumer electronics applications where weight reduction and durability are critical. With the expansion of smart devices, interior vehicle applications, and portable mirrors, plastic substrates are becoming more relevant. Advances in coating technologies are improving their performance and expanding their potential across industries.
Product Form
Which Product Form Segment Dominated The U.S. Mirror Coatings Market In 2024?
The flat mirror panels/sheets segment dominated the U.S. mirror coatings market in 2024. Flat mirror panels/sheets account for a significant share of the US mirror coatings market, widely used in architectural, decorative, and solar applications. They provide durable, high-quality reflectivity for residential, commercial, and industrial uses. The demand is supported by construction projects and the integration of mirrors in modern interior designs. Additionally, solar power installations increasingly utilize coated flat panels for concentrating and directing sunlight efficiently.
The mirror films / metallized films segment expects significant growth in the U.S. mirror coatings market during the forecast period. Mirror films/metallized products are expanding in adoption due to their lightweight, flexible, and versatile nature. In the US, they are used in automotive interiors, smart devices, and consumer applications requiring thin and portable reflective surfaces. Roll-to-roll vacuum processes allow efficient large-scale production, making these films cost-effective. Their adaptability and ease of integration into different surfaces are driving their uptake in both industrial and consumer-oriented applications.
End-Use Industry
How Did the Architectural & Construction Segment Dominated The U.S. Mirror Coatings Market In 2024?
The architectural & construction segment dominated the U.S. mirror coatings market in 2024. Architectural and construction remains the leading end-use industry in the US mirror coatings market. Demand is driven by residential and commercial projects where mirrors enhance aesthetics, provide energy efficiency, and improve interior lighting. Silver-coated glass mirrors dominate in this sector, while dielectric coatings are gaining ground in premium applications. Growth in smart building technologies and modern design trends further supports expansion in this end-use segment.
The solar energy segment expects significant growth in the U.S. mirror coatings market during the forecast period.
Solar energy is an emerging and fast-growing end-use sector for mirror coatings in the US. Coated mirrors are critical in concentrating solar power (CSP) systems, enabling efficient energy capture and conversion. Dielectric coatings and high-durability silver coatings are particularly important for ensuring long-term optical performance under harsh outdoor conditions. With the US expanding renewable energy capacity, the solar sector is creating strong opportunities for mirror coatings manufacturers.
Distribution Channel
Which Distribution Channel Segment Dominated The U.S. Mirror Coatings Market In 2024?
The glass fabricators & processors segment dominated the U.S. mirror coatings market in 2024. Glass fabricators and processors form a key distribution channel in the US mirror coatings market, bridging the gap between coating manufacturers and end-use industries. They customize and process coated glass panels to meet specific requirements in construction, automotive, and industrial applications. Their role is critical in ensuring that coated products meet safety, quality, and performance standards. This channel remains vital for bulk and project-based supplies.
The OEM supply (automotive & smart devices) segment expects significant growth in the U.S. mirror coatings market during the forecast period. OEM supply (automotive and smart devices) is another significant distribution channel, ensuring direct integration of coated mirrors into vehicles, electronics, and appliances. OEM demand in the US is rising due to the growing use of reflective and smart mirror technologies in next-generation vehicles and consumer devices. This direct supply chain enables manufacturers to tailor coatings for performance, durability, and innovation, fostering long-term collaborations with major OEMs.
Recent Developments
- In July 2025, HOYA, a specialist in vision care, in collaboration with Lumacore Mirroes, recently launched its HOYA Polarized Lenses. They aim to offer cleanliness and durability, resistance to peeling, and long-lasting mirror quality to the consumers.(Source: www.optometrytimes.com)
Top Companies List
- The Sherwin-Williams Company
- Dynasil Corporation
- Ferro Corporation
- North American Coating Laboratories
- Reynard Corporation
- Abrisa Technologies
- AccuCoat Inc.
- Sterling Precision Optics Inc.
- D & W, Inc.
- Glass & Mirror Outlet
- Ever Better Mirror
- Maryland Glass & Mirror Company
- Wholesale Glass & Mirror Manufacturer
- Lenoir Mirror Company
- Avalon Glass and Mirror Manufacturer
- Majestic Mirror & Frame Manufacturer
- Fab Glass and Mirror Company
- Virginia Mirror Company
- Guardian Glass
- Cardinal Glass Industries
Segments Covered
By Coating Material
- Silver-based coatings
- Aluminum-based coatings
- Chromium-based coatings
- Nickel & alloy-based coatings
- Dielectric (oxides, nitrides, fluorides)
- Hybrid metal–dielectric coatings
- Organic/polymeric Mirror Coatings
By Deposition Technology
- Chemical Wet Silvering
- Physical Vapor Deposition (Thermal Evaporation, E-Beam)
- Magnetron Sputtering (DC/RF/Reactive)
- Electroplating / Electro-Deposition
- Atomic Layer Deposition (ALD)
- Roll-to-Roll Vacuum Coating
By Substrate Type
- Glass Substrates (Float, Low-Iron, Tempered, Laminated)
- Plastic Substrates (Acrylic/PMMA, Polycarbonate)
- Metal Substrates (Aluminum, Stainless Steel)
- Film Substrates (Polyester/PET, Other Polymer Films)
By Product Form
- Flat Mirror Panels / Sheets
- Laminated Mirror Assemblies
- Mirror Films / Metallized Films (Rolls)
- Patterned / Decorative Mirrors
- One-Way / Two-Way Mirrors
By End-Use Industry
- Architectural & Construction
- Residential & Furniture
- Automotive & Transportation
- Consumer Appliances & Electronics
- Optical & Scientific Instruments
- Solar Energy (CSP, PV Reflectors)
- Aerospace & Defense
- Healthcare & Medical Devices
- Security & Surveillance
- Industrial & Others
By Distribution Channel
- OEM Supply (Automotive, Appliances, Optics)
- Glass Fabricators & Processors (B2B)
- Wholesale Distributors (Commercial)
- Retail & DIY Outlets (Home Improvement)
- E-Commerce / Online Platforms
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.