
U.S. Chillers Market Size, Competitive Landscape Analysis Report 2035
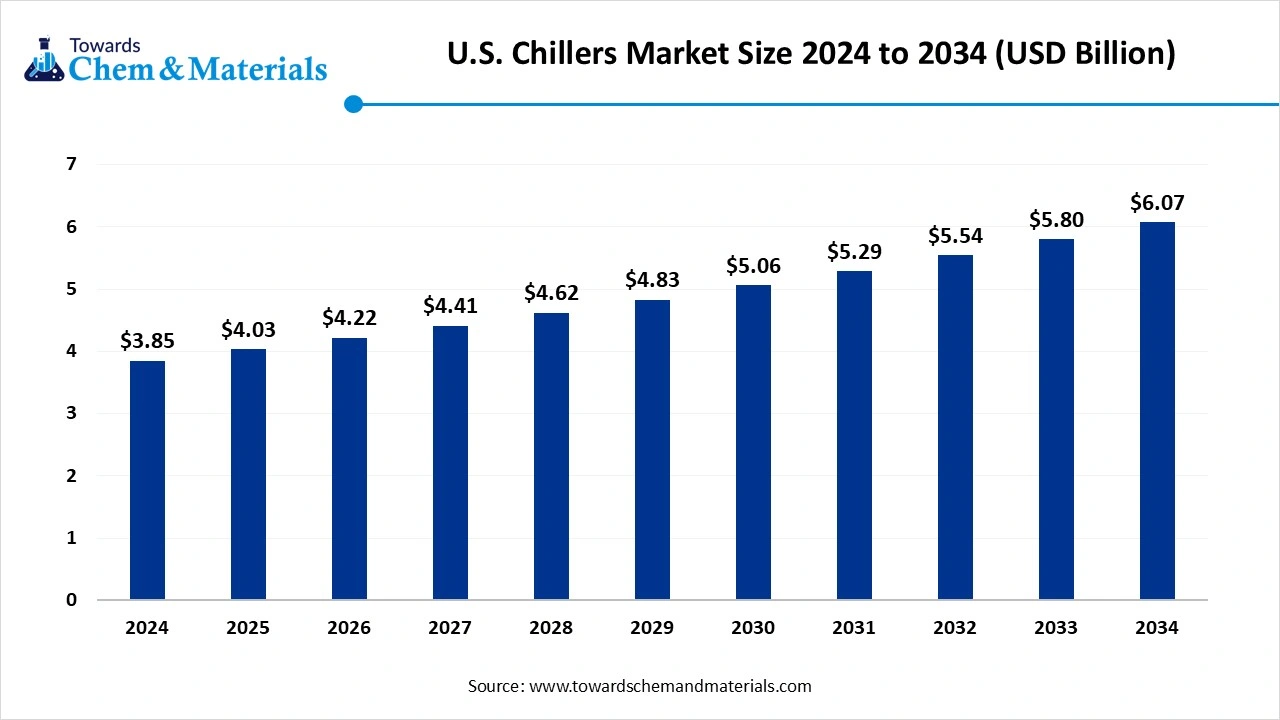
The U.S. chillers market size is expected to grow from USD 1.85 billion in 2025 to USD 1.94 billion in 2026 and is forecast to reach USD 2.94 billion by 2035 at a 4.75% CAGR over 2026-2035. The increasing need for energy-efficient cooling systems in several spaces has fueled industrial growth in recent years.
Key Takeaways
- By type, the water-cooled segment emerged as top top-performing segment in 2025 due to better efficiency.
- By type, the air-cooled segment is likely to experience notable growth during the forecast period, akin to easy installation with less maintenance.
- By application, the commercial application segment led the market in 2025, owing to high demand from offices, hotels, shopping malls, and hospitals.
- By application, the industrial application segment is projected to grow significantly over the forecast period due to the increased need for heavy-duty cooling systems.
- By compressor, screw chillers segment emerged as leading segment in the U.S. chillers market in 2025 owing its strength and reliability.
- By compressor, scroll chillers are likely to register the fastest growth among all segments during the coming years, akin to energy efficiency and affordability.
U.S. Chillers Market Gains Momentum Amid Rising Tech Facilities Demands
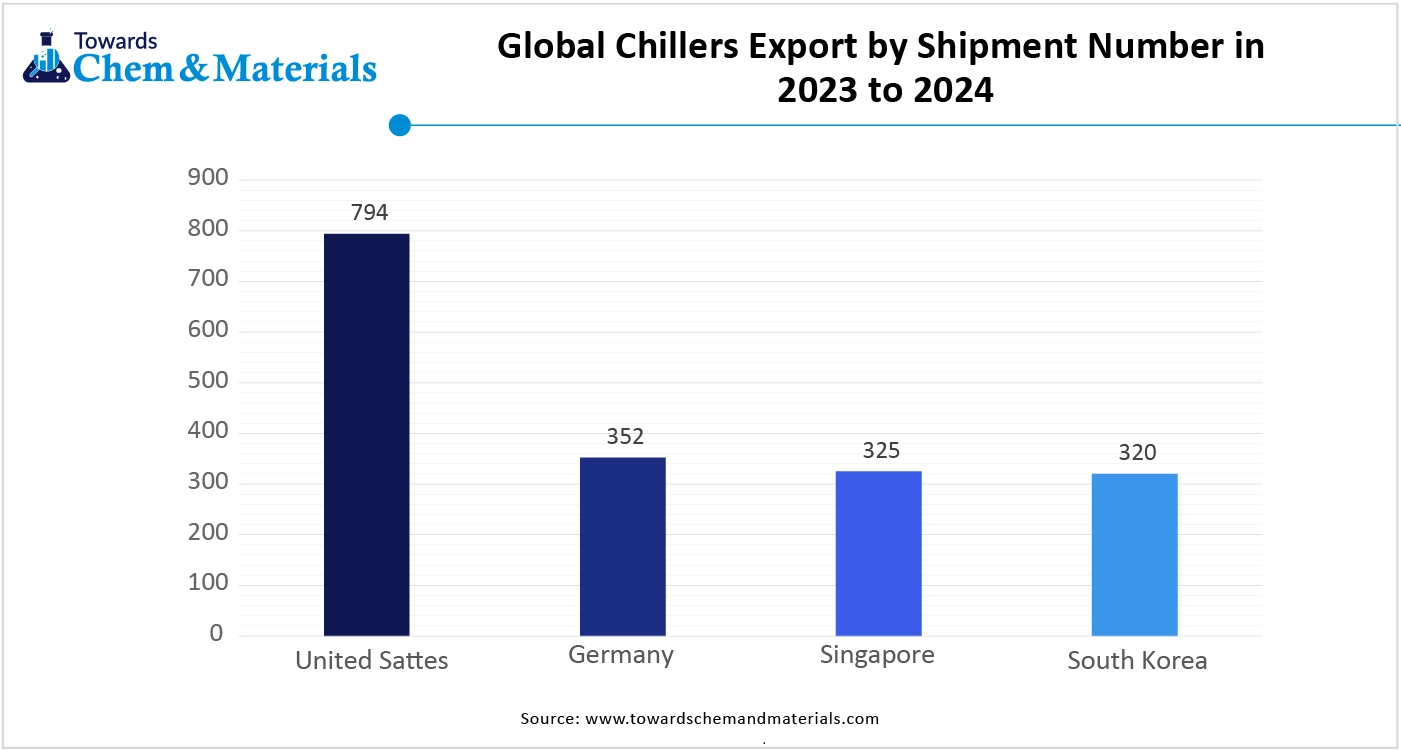
The United States chillers market is expected to see steady growth owing to its wide application in modern infrastructure in the current period. Moreover, several industries are actively seeking efficient cooling systems in the country nowadays, which is contributing to the growth of the market as per the earlier observation. Also, the country's commercial spaces and tech facilities are increasingly demanding advanced temperature control systems in the current period. In this process, technology advances are projected to play a major role in the upcoming period and lead the global consumer base, as expected in the United States.
What is Driving the Growth of the Chillers Industry in the United States?
The increased need for energy-efficient cooling systems is spearheading the U.S. chillers market growth in the current period. Several sectors, such as data centers, factories, buildings, and other commercial sectors, are actively looking for the cost of their electricity bills in the United States, as per the recent observation. By launching smart chillers, the manufacturers are expected to gain a first mover advantage in the country for the future period. Moreover, the United States government is increasingly seen as backing up the green environment initiatives, which is likely to provide substantial advantages for the chillers manufacturers in
Market Trends
- The increasing preferences for eco-friendly and green building development are spearheading the industry growth in the current period. These developers are increasingly observed as installing this type of chiller or the low-emission refrigerants to save energy and water. The modern standards like LEED and others heavily recommending these types energy energy-efficient chillers and green initiatives.
- The sudden surge in internet service and cloud computing has led to an increasing number of data centers in the United States recently, which provides a heavy consumer base to the chiller manufacturers in the current period. These data centers have been observed as generating a lot of heat and requiring powerful cooling systems in recent years.
- The growing adoption of modular and smart chillers is expected to create beneficial opportunities for manufacturers in the coming years, as the smaller units of modular chillers are seen as providing flexibility and being easily upgradable. Moreover, smart chillers are mainly seen in heavy adoption in the enlarged business infrastructure.
Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 1.94 Billion |
| Expected Size by 2035 | USD 2.94 Billion |
| Growth Rate from 2025 to 2035 | CAGR 4.75% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Segment Covered | By Product, By Application, By Compressor |
| Key Companies Profiled | Thermal Care, Inc., Advantage Engineering, Inc., Compressed Air Systems, Inc., Thermal Care, Inc.,Delta Industries, Universal Air & Gas Products (aka Universal Air Products Corp.),Dimplex Thermal Solutions,Ecochillers, Inc., G&D Chillers, Baltimore Aircoil Company, Custom Control Sensors, LLC, Drake Refrigeration, Inc.,Cold Shot Chillers, Thermo Fisher Scientific Inc., American Chillers, Legacy Chillers, Inc.,Chillermen, FLUID CHILLERS, INC., Carrier Global Corporation, TRANE Technologies Plc., Polyscience Inc. |
Market Opportunity
Upgrading Cooling Infrastructure Creates New Opportunities for Manufacturers
The ongoing replacement of old systems in several spaces, such as industrial and commercial, is expected to create lucrative opportunities for U.S. chillers market. Moreover, several industry and commercial spaces are increasingly seen replacing or actively looking for modern cooling systems that are suitable for their modern infrastructure in the current period. Also, several governments in the regions are observed as backing and implementing sustainable and green building initiatives, which are likely to contribute to the chillers market growth during the forecast period.
Market Challenge
High-Tech Cooling Systems Face Resistance from Cost-Conscious Buyers
The high cost of technologically advanced chillers is expected to hamper the U.S. chillers market growth in the upcoming years. In today’s modern era, several small businesses and mid-size commercial places can struggle to afford this chiller or initial investment in the future. Also, government-released regulations are continuously increasing the cost of technology, which can create further barriers for industry growth in the future. Also, new entrants are likely to face these challenges during the projected period.
Is Energy Efficiency the Key Factor Behind Water–Cooled Chillers?
The water-cooled segment held the largest share of the market in 2024, akin to its efficiency for better working in steady end-use environments and large buildings. Also, in large offices, hospitals, factories, and malls are installing water-cooled chillers in the current period. Having unique properties like lower operating costs and strength has actively contributed to the segment's growth in recent years. Also, nations' commercial and institutional spaces are expected to provide a higher number of consumers to the segment in the future.
The air-cooled segment is seen to grow at a notable rate during the predicted timeframe, owing to unique advantages such as easy installation and less maintenance. This chiller does not require any type of water supply is making it ideal for small institutions and areas where water supply or access is very limited, which is anticipated to contribute to the segmental growth during the incoming years. Moreover, air-cooled chillers have gained immense popularity in mid-size and small business firms, as per the recent observation.
What Makes Commercial Applications the Top Contributor to U.S. Chillers Market?
The commercial application segment held the dominant share of the U.S. chillers market in 2024 due to high demand from offices, hotels, shopping malls, hospitals, and schools. These places need constant cooling to keep people comfortable and equipment running properly. Commercial buildings also focus more on energy savings and system reliability, and chillers are key to managing large-scale cooling. Many buildings are also replacing older systems with modern, energy-efficient chillers. Since the commercial construction industry is large and growing in the U.S., the need for reliable cooling solutions remains strong. This has kept commercial applications as the top contributor to chiller demand in recent years.
The industrial application segment is seen to grow at a notable rate during the predicted timeframe. Factories, food processing plants, chemical facilities, and data centers all need heavy-duty cooling systems. As industries expand and upgrade their equipment, they need chillers to control temperature and protect machinery. Also, strict rules for process cooling and safety will drive demand. The rise in U.S. manufacturing and warehousing will push the need for more chillers in production and storage areas. Industrial applications will likely grow faster than commercial ones as industries adopt smart and energy-saving cooling systems to improve productivity and meet new efficiency standards.
Can Screw Chillers Handle Fluctuating Cooling Loads Better Than Others?
The screw chillers segment held the largest share of the market in 2024 owing to screw chillers are strong, reliable, and work well in medium to large cooling systems. They are often used in hotels, hospitals, and manufacturing plants where the cooling load changes throughout the day. Screw compressors can handle these changes without losing efficiency. They also run more quietly and have fewer moving parts, which means fewer breakdowns. For many years, screw chillers have been the go-to choice for dependable and steady cooling. Their long life and ability to handle larger buildings have helped make screw chillers the most used type in the market.
The scroll chillers segment is expected to grow at the fastest rate in the market during the forecast period. Scroll chillers are compact, energy-efficient, and affordable. They are perfect for small to medium-sized buildings like offices, retail stores, and clinics. Scroll compressors are quieter and easier to maintain than other types. As more businesses and building owners look for low-cost, high-efficiency cooling systems, scroll chillers will become a preferred option. They are also ideal for modular systems where extra units can be added when needed. With new building projects and retrofits focusing on efficiency and cost, scroll chillers are set to play a bigger role in the future U.S. chillers market.
Recent Developments
- In May 2025, Modine increased their production capacity of chillers recently. Also, the reason for this expansion is to serve data centre customers, as per the report published by the company. Also, the company is expected to invest $38 million in this initiative, as per the company's claim. (Source: investors.modine.com )
- In October 2024, Pro Refrigeration introduced its latest cooling solution. Moreover, the newly launched chiller is named the PRO Chiller PRO4 Series, as per the report published by the company. Also, this launch is held at the World Dairy Expo in Madison, Wisconsin. (Source : businesswire.com )
- In April 2024, the G&D Chillers unveiled their latest propane technology in the United States industrial and commercial refrigeration industry environment. Also, the newly launched product line is trialing Elite 290 propane chillers, according to a report published by the company. Moreover, the chillers have unique properties like zero global warming potential and cost-effectiveness. (Source: gdchillers.com)
Top Companies List
- Thermal Care, Inc.
- Advantage Engineering, Inc.
- Compressed Air Systems, Inc.
- Thermal Care, Inc.
- Delta Industries
- Universal Air & Gas Products (aka Universal Air Products Corp.)
- Dimplex Thermal Solutions
- Ecochillers, Inc.
- G&D Chillers
- Baltimore Aircoil Company
- Custom Control Sensors, LLC
- Drake Refrigeration, Inc.
- Cold Shot Chillers
- Thermo Fisher Scientific Inc.
- American Chillers
- Legacy Chillers, Inc.
- Chillermen
- FLUID CHILLERS, INC.
- Carrier Global Corporation
- TRANE Technologies Plc.
- Polyscience Inc.
Segment Covered in the Report
By Product Type
- Water-Cooled
- <50kW
- 51-100kW
- 101-500kW
- 501-1000kW
- 1001-1500kW
- >1501kW
- Air-Cooled
- <50kW
- 51-100kW
- 101-500kW
- 501-1000kW
- 1001-1500kW
- >1501kW
By Application
- Commercial
- Corporate Offices
- Data Centers
- Public Buildings
- Mercantile & Service
- Healthcare
- Others
- Industrial
- Chemicals & Petrochemicals
- Food & Beverage
- Metal Manufacturing & Machining
- Medical & Pharmaceutical
- Plastics
- Others
- Residential
By Compressor
- Screw Chillers
- Centrifugal Chillers
- Absorption Chillers
- Scroll Chillers
- Reciprocating Chillers
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.