
Precision Chemicals Market Size, Competitive Landscape Analysis Report 2035
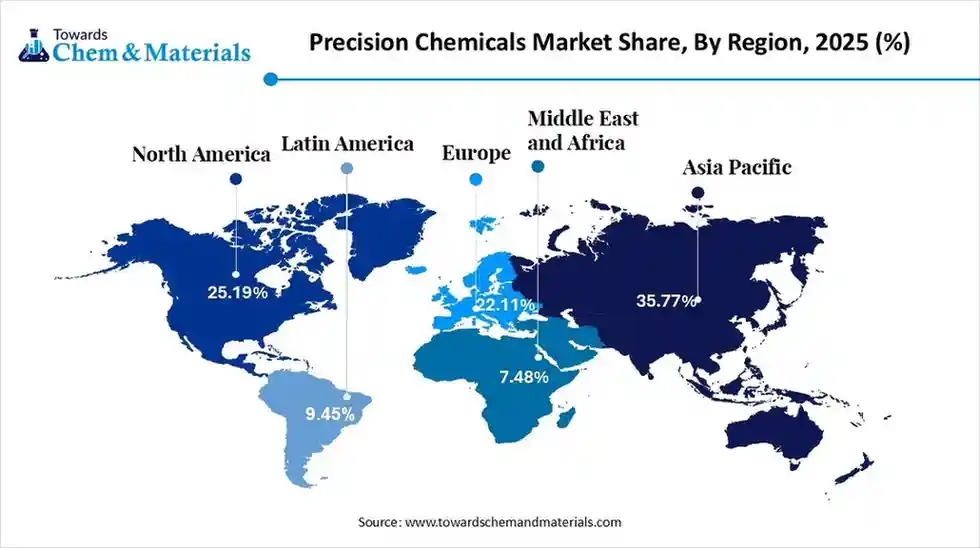
The global precision chemicals market size was estimated at USD 63.92 billion in 2025 and is predicted to increase from USD 68.47 billion in 2026 and is projected to reach around USD 127.16 billion by 2035, The market is expanding at a CAGR of 7.12% between 2026 and 2035. Asia Pacific dominated the precision chemicals market with a market share of 35.77% the global market in 2025.The shift towards higher purity materials has accelerated market growth in recent years.

Key Takeaways
- The Asia Pacific dominated the global precision chemicals market with the largest revenue share of 35.77% in 2025, owing to the region having massive production units of manufacturing electronics, cars, and consumer goods, where precision chemicals have become a crucial element in recent years.
- The North America is anticipated to capture a greater portion of the market with a significant CAGR in the future, due to the ongoing advanced manufacturing and establishment of battery plants and biotech.
- By product type, the active pharmaceutical ingredients (APIs) & advanced intermediates segment dominated the market with approximately 40.55% industry share in 2025 due to the increased demand for tiny amounts of pure and well-documented chemicals in recent years.
- By product type, the high-purity / electronic chemicals segment is expected to grow with approximately 22.88% industry share during the forecast period, due to the sudden surge in energy devices and electronics manufacturing in recent years.
- By service type, the custom synthesis/contract research & manufacturing (CDMO / CMO) segment dominated the market with approximately 54.67% industry share in 2025, akin to the many clients need for unique, small-volume molecules that off-the-shelf products cannot supply.
- By service type, the merchant / off-the-shelf high-purity products segment is expected to grow at a rapid CAGR during the forecast period due to the many factories seeking fast access to validated chemicals without the wait for custom work.
- By application type, the pharmaceuticals segment dominated the market with approximately 42.66% industry share in 2025, owing to the making medicines requiring super clean and reliable chemicals.
- By application type, the electronics & semiconductors segment is expected to grow with rapid CAGR during the forecast period, due to the sudden surge in energy devices and electronics manufacturing in recent years.
- By purity type, the high-purity chemicals segment led the market with the largest revenue share of 38.94% in 2025, due to the many modern products like chips, batteries, and sensors that need chemicals that are almost perfectly clean.
- By purity type, the specialty GMP / pharma-grade segment is expected to grow with a rapid CAGR during the forecast period, due to more companies being seen in the requirement for the chemicals made at a medicine-level quality.
From Electronics to Healthcare: The Demand for Exact Chemistry
The precision chemicals refer to precisely developed chemical products that are primarily made in a very controlled way for exact delivery of performance for the specific task. Moreover, these chemicals are not generally produced in bulk quantities, as per the recent observation. Furthermore, the sector such as electronics, specialty polymers, healthcare, and micro manufacturing has seen under heavy demand for these chemicals over the past few years.
Precision Chemicals Market Trends:
- The emergence of the sub-micron chemicals has attracted increased capital and investment in manufacturing in the current period. Moreover, by working efficiently on extremely small scales, specifically below one micron, the sub-micron segment has gained major attention in applications like EV batteries, micro coatings, and advanced electronics.
- The development of the custom-built chemicals for the cleaner manufacturing systems is likely to lead to robust revenue growth across the sector in the coming years. Moreover, the shift towards renewable energy is also expected to create lucrative growth opportunities during the forecast period.
- The rise of the functional micro additives is strengthening the foundation for future sector growth. As several industries are demanding the material that adds very specific functionalities while not changing entire formulations, where these functional micro additives have created their own industry presence in recent years.
Report Scope
| Report Attribute | Details |
| Market Size Value in 2026 | USD 68.47 Billion |
| Revenue Forecast in 2035 | USD 127.16 Billion |
| Growth Rate | CAGR 7.12% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Dominant Region | Asia Pacific |
| Fastest Growing Region | North America |
| Segment Covered | By Product / Type, By Service / Manufacturing Model, By Application / End-Use Industry, By Purity / Quality Tier, By Region |
| Key companies profiled | Thermo Fisher Scientific, Lonza Group, BASF SE, Evonik Industries, Cambrex Corporation, Jubilant Ingrevia, Wuxi AppTec / Wuxi Biologics, Sumitomo Chemical, Syngene International, CordenPharma, Piramal Pharma Solutions, Asymchem, Samsung Biologics, Johnson Matthey, Honeywell / UOP, Clariant, Albemarle / Arkema |
Built Smarter Today, Evolving Faster Tomorrow
Companies now use smart computer tools to design chemicals before making them in real life. Computers can test thousands of chemical ideas in seconds, so scientists only create the ones that work. This saves time, money, and a lot of wasted materials. Factories are also using tiny, automated reactors that adjust temperature, mixing, and purity on their own, which makes the chemicals very accurate.
Trade Analysis of the Precision Chemicals Market: Import, Export, Consumption, and Production Statistics
- The organic export by China in 2024 has reached $82.7 billion as per the publicly available data.
- The chemical products have become the fourth most exported product in the United States, with a traded value of $243 billion in 2024, according to the report.
Value Chain Analysis of the Precision Chemicals Market:
- Distribution to Industrial Users: Distribution of precision chemicals to industrial users is handled through a combination of large, global chemical distributors and specialized manufacturers direct supply chains, with key players operating in various end-use industries like electronics, pharmaceuticals, and agriculture
- Key Players: Brenntag SE and Azelis Holdings S.A.
- Chemical Synthesis and Processing: Chemical synthesis and processing in the market focus on achieving high purity, specific molecular structures, and consistent quality for demanding applications like electronics and pharmaceuticals. Key players in this sector are a mix of major global chemical manufacturers and specialized contract development and manufacturing organizations (CDMOs)
- Key Players: Merck KGaA and Evonik Industries AG
- Regulatory Compliance and Safety Monitoring: Regulatory compliance and safety monitoring in the precision chemicals market are governed by a complex web of local, national, and international laws aimed at protecting human health and the environment.
- Key Agencies: Globally Harmonized System (GHS) and REACH (Registration, Evaluation, Authorisation, and Restriction of Chemicals)
Precision Chemicals Market Regulatory Landscape: Global Regulations
| Country / Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Environmental Protection Agency (EPA) | Toxic Substances Control Act (TSCA) | Risk-based assessment of new and existing chemicals, public transparency |
| European Union | European Chemicals Agency (ECHA) | REACH Title II (Registration) | High level of protection for human health and the environment |
| China | Ministry of Ecology and Environment (MEE) | MEE Order No. 12 | Environmental management and registration of new chemical substances |
Segmental Insights
Product Type Insights
How did the Active Pharmaceutical Ingredients (APIs) & Advanced Intermediates Segment Dominate the Precision Chemicals Market in 2025?
The active pharmaceutical ingredients (APIs) & advanced intermediates segment led the market with nearly 40.55% market share in 2025, due to growing demand for tiny amounts of pure and well-documented chemicals in recent years. Moreover, by meeting the safety rules, fast reformulations, and clinical needs have been driving the segment growth in recent years, as per the observation.
The high-purity / electronic chemicals segment is expected to grow with approximately 22.88% market share, akin to the sudden surge in energy devices and electronics manufacturing in recent years. Moreover, the products like batteries, displays, semiconductors, and sensors rely on ultra-pure chemicals and materials where near-zero impurities are recommended, which is supporting the segment growth in recent years.
Service Type Insights
Why does the Custom Synthesis / Contract Research & Manufacturing (CDMO / CMO) Segment Dominate the Precision Chemicals Market?
The custom synthesis/contract research & manufacturing (CDMO / CMO) segment dominated the market with approximately 54.67% market share in 2025, akin to the many clients need for unique, small-volume molecules that off-the-shelf products cannot supply. Precision-chemistry firms build dedicated processes, scale methods, and regulatory documentation for each customer. Drug developers, agrochemical innovators, and specialty electronics firms pay these providers to reduce time to market, avoid in-house scale-up risks, and protect IP.
The merchant / off-the-shelf high-purity products segment is expected to grow at a rapid CAGR. Due to the many factories seeking fast access to validated chemicals without the wait for custom work. As electronics and battery makers scale, they prefer trusted, ready-made chemistries that plug straight into their production lines.
Application Type Insights
How did the Pharmaceuticals Segment Dominate the Precision Chemicals Market in 2025?
The pharmaceuticals segment dominated the market with approximately 42.66% market share in 2025, owing to the making medicines requiring super clean and reliable chemicals. Even tiny impurities can change how a drug works, so companies choose suppliers who can guarantee purity every time. Pharma firms also need lots of documents, testing data, and stable batches, and precision chemical makers are built for that.
The electronics & semiconductors segment is expected to grow with fastest market share, akin to their increasing need for the chemicals that are almost perfectly clean. If even a dust-sized impurity lands on a chip, the whole wafer can fail. With the increased demand for more phones, data centers, electric cars, and smart gadgets, companies need even more of these ultra pure chemicals.
Purity Type Insights
Why does the High-Purity / Electronic-Grade Segment Dominate the Precision Chemicals Market?
The high-purity / electronic-grade segment dominated the largest revenue share of 38.94% in 2025, due to the many modern products like chips, batteries, and sensors that need chemicals that are almost perfectly clean. Even tiny impurities can ruin a full production run, so factories prefer chemicals that come with detailed purity checks. Suppliers have built special clean facilities to make sure nothing contaminates these chemicals.
The specialty GMP / pharma-grade segment is expected to grow at a rapid CAGR due to more companies being seen in the requirement for the chemicals made at a medicine-level quality. These chemicals are created in clean, carefully checked facilities and come with full safety and purity records. its not just drug makers, medical device companies, testing labs, and even health-food brands that now want GMP-quality inputs.
Regional Insights
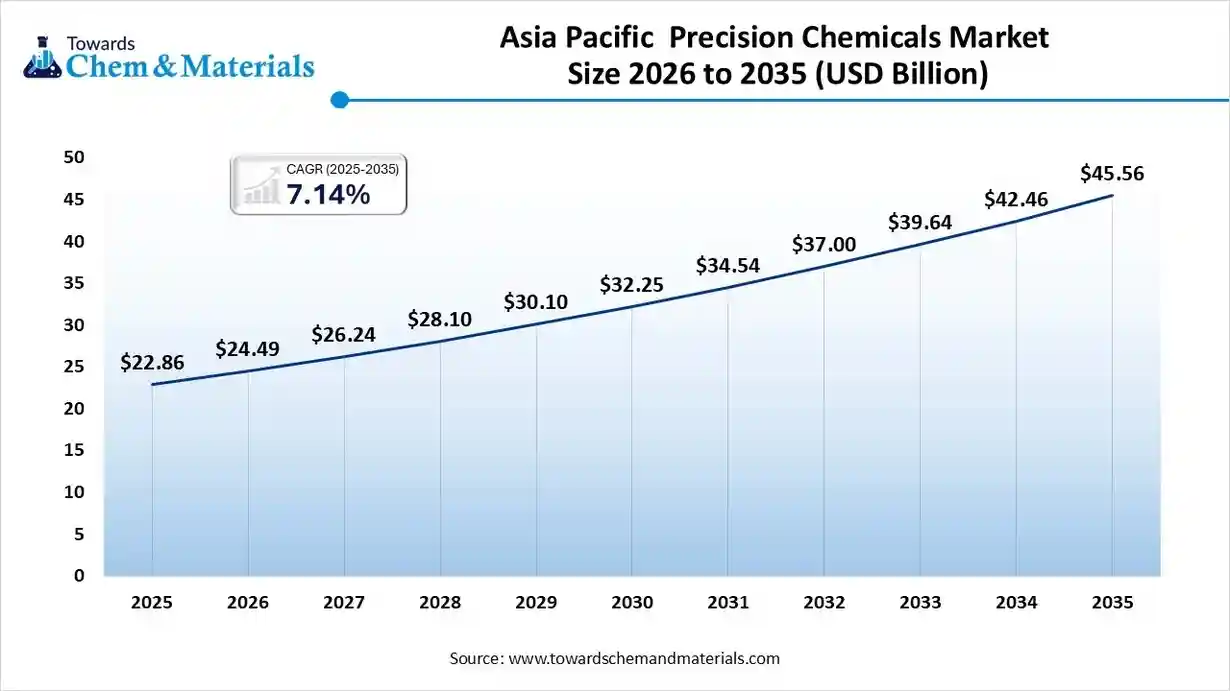
The Asia Pacific precision chemicals market size was valued at USD 22.86 billion in 2025 and is expected to reach USD 45.56 billion by 2035, growing at a CAGR of 7.14% from 2026 to 2035. Asia Pacific dominated the precision chemicals market in 2025, owing to the region having massive production units of manufacturing electronics, cars, and consumer goods, where precision chemicals have become a crucial element in recent years. Moreover, the regional countries such as India, China, and Japan have seen in heavier investment in battery parks and ultra-clean chemicals plants in recent years.
China’s Strong Local Supply Chain Continues to Anchor Its Precision Chemical Leadership
China maintained its dominance in the precision chemicals market, akin to the greater investment towards the strengthening foundation of the local supply chain and production in the past few years. Moreover, factors such as low cost, faster delivery, and deep raw material supply have elevated the earning potential for producers in the current period, as per the country survey.
North America Precision Chemicals Market Examination
North America is expected to capture a major share of the market with a rapid CAGR, due to the ongoing advanced manufacturing and establishment of battery plants and biotech. Moreover, the region is looking for the minimization of export dependence while boosting local production facilities, where the governments are increasingly involved in recent years.
High Purity Chemicals Leadership is Positioning the United States as a Key Global Market
The United States is expected to emerge as a prominent country for the precision chemicals market in the coming years, due to the emergence of global brands for high-purity chemicals in the region. Moreover, the manufacturers are heavily focused on tight supply security and IP protection for these types of high-purity products in the region nowadays.
Europe Precision Chemicals Market Evaluation
Europe is a notably growing region owing to the prioritization of high-quality, niche technology, and sustainability by local manufacturers. Moreover, the presence of the stronger automotive sector and semiconductor sectors is set to enable high return ventures for precision chemicals manufacturers in the coming years as per the future industry expectations.
Germany Emerges as a Hub for Tailored Chemistries
Germany is expected to gain a major industry, akin to the increasing demand for the low-volatility, green, and tightly specified chemistries for the specific and advanced engine parts and industrial coatings in the coming years. Moreover, the region has an engineering and research institutions culture which supports the development of bespoke chemistry in recent years.
Precision Chemicals Market Study in the Middle East and Africa
The Middle East and Africa are expected to capture a notable share of the industry owing as these regions are observed in building factories and not just selling raw oil. New hubs for solar panels, medicines, and hi-tech parts need special chemicals that were once imported. Countries like the UAE, Saudi Arabia, and South Africa are inviting foreign companies to build clean chemical plants close to factories, cutting delivery time.
Clean Plants and Fast Delivery Models are Enhancing Saudi Arabia’s Precision Chemical Supply Chain Saudi Arabia is expected to emerge as a prominent country for the precision chemicals market in the coming years due to changing fast and the need for better chemicals for new industries. Big projects and factories mean more demand for pure, specialty chemicals used in batteries, medicines, and high-tech coatings. The country is building clean plants near the places that use these chemicals, so deliveries are quick.
South America Precision Chemicals Market Evaluation
South America is a notably growing region. As factories are slowly moving from rough-and-ready ways to more careful, modern production, it is better for precision chemicals. Mines, food plants, and car part makers need cleaner, specialist chemicals to make better products. Local companies want nearby suppliers, so they dont wait weeks for imports.
Brazil’s Shift Towards the Tech-Driven Manufacturing
Brazil is expected to gain a major industry owing to the factories in the country are getting more modern. Food, medicine makers, and car parts factories want purer, dependable chemicals to make products that sell globally. Brazil is also moving into battery parts and other tech fields, which need special chemical ingredients.
Recent Developments
- In December 2025, Croda established a strategic partnership with Amino. Also, the main motive behind the collaboration is to boost the global supply of high-purity amino acids, as per the published report.(Source: www.indianchemicalnews.com)
Top Vendors in the Precision Chemicals Market & Their Offerings:
- Thermo Fisher Scientific: A world leader in serving science, providing instruments, reagents, and software for life science research, analytical challenges, and pharmaceutical manufacturing.
- Lonza Group: A Swiss multinational contract manufacturing (CDMO) company for the pharmaceutical, biotechnology, and nutrition sectors, providing drug development services and custom manufacturing.
- BASF SE: The largest chemical company in the world by revenue, producing performance chemicals, specialty chemicals, and functional polymers used across various industries.
Top Companies in the Precision Chemicals Market

- Thermo Fisher Scientific
- Lonza Group
- BASF SE
- Evonik Industries
- Cambrex Corporation
- Jubilant Ingrevia
- Wuxi AppTec / Wuxi Biologics
- Sumitomo Chemical
- Syngene International
- CordenPharma
- Piramal Pharma Solutions
- Asymchem
- Samsung Biologics
- Johnson Matthey
- Honeywell / UOP
- Clariant
- Albemarle / Arkema
Segments Covered in the Report
By Product / Type
- Active Pharmaceutical Ingredients (APIs) & Advanced Intermediates
- High-Purity / Electronic Chemicals
- Fine Chemicals & Building Blocks
- Catalysts & Specialty Additives
- Biocatalysts / Enzymes & Biochemicals
- Analytical Standards & Specialty Reagents
By Service / Manufacturing Model
- Custom Synthesis / Contract Research & Manufacturing (CDMO / CMO)
- Merchant / Off-the-shelf High-Purity Products
- Toll Manufacturing / Private-label supply.
By Application / End-Use Industry
- Pharmaceuticals
- Electronics & Semiconductors
- Agrochemicals & Crop-protection intermediates
- Specialty Coatings & Functional Materials
- Research & Diagnostics / Life-science reagents
By Purity / Quality Tier
- High-Purity / Electronic-grade
- Research-grade & Reagent grade
- Specialty GMP / Pharma-grade
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.