Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The global nitrogenous fertilizer market size was valued at USD 68.45 billion in 2025, is estimated to reach USD 72.52 billion in 2026, and is projected to reach USD 122.01 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.95% over the forecast period from 2026 to 2035.Asia Pacific dominated the nitrogenous fertilizer market with the largest revenue share of 70% in 2025 and is expected to grow at the fastest CAGR of 6.02% during the forecast period. In terms of volume, the nitrogenous fertilizer market is projected to grow from 119.23 million metric tons in 2025 to 173.96 million metric tons by 2035. growing at a CAGR of 3.85% from 2026 to 2035.In the era of technology and sustainability improvements, farmers are the major contributors to this trend with their implementation of advanced farming practices. Also, the green ammonia and hydrogen emergence is likely to lead to growth during the projected time. Market Highlights

The global adoption of modern agricultural practices and food security has played a strategic role in the industry's growth. Also, in the developed and developing regions, farmers are increasingly shifting towards the solution of better crop yield farms, with limited land, where nitrogenous fertilizers have emerged as an ideal option. Furthermore, the huge regions such as the Asia Pacific and Europe have observed greater demand in recent years.
The industry is experiencing transformation due to changing environmental regulations, rising sustainability concerns, and growing pressure to reduce greenhouse gas emissions associated with fertilizer production and application. Manufacturers are investing in cleaner production technologies, low-carbon ammonia projects, and energy-efficient manufacturing processes to improve environmental performance while maintaining production capacity.
The global manufacturers are investing in green ammonia production. Major fertilizer companies are investing in facilities that use renewable energy instead of natural gas to produce ammonia.
For instance, in June 2026, the company called ACME signed an agreement for the expansion of green hydrogen and ammonia production in Oman, as per the published report.(Source: www.enerdata.net)
Manufacturers are investing heavily in carbon capture and storage technologies at ammonia and fertilizer production facilities. These projects help reduce carbon emissions while maintaining existing production infrastructure.Farmers are demanding higher fertilizer efficiency, encouraging investments in enhanced-efficiency fertilizers and digital nutrient management platforms. Companies are developing products that improve nitrogen utilization while reducing nutrient losses.
| Report Attributes | Details |
| Market Size in 2026 | USD 72.52 Billion/ 123.82 Million Metric Tons |
| Market Size by 2035 | USD 122.01 Billion/ 173.96 Million Metric Tons |
| Growth Rate from 2025 to 2035 | CAGR 5.95% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Product, By Application, By Region |
| Key Companies Profiled | Yara International ASA, Nutrien Ltd., CF Industries Holdings, Inc., SABIC (Saudi Basic Industries Corporation), EuroChem Group, OCI Global, Koch Industries, Inc. |
The industry is actively turning from fossil-fuel-based ammonia production toward renewable-energy-powered green ammonia manufacturing. Traditionally, ammonia production depended heavily on natural gas, resulting in substantial carbon emissions. In the current period, manufacturers are integrating electrolysis technologies that use renewable electricity to produce hydrogen for ammonia synthesis. Moreover, artificial intelligence, digital process monitoring, and carbon capture systems are being incorporated into fertilizer manufacturing facilities.
Production & Processing
Quality Testing and Certification
Distribution to Industrial Users
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Environmental Protection Agency (EPA) | 40 CFR Part 418 (Subparts B, C, and D): This section of the Clean Water Act establishes strict limits on wastewater discharges from the manufacturing process. Subpart B covers Ammonia, Subpart C targets Urea formulation, and Subpart D dictates rules for Ammonium Nitrate. | Mitigating hazardous industrial runoffs into national waterways, preventing catastrophic chemical plant explosions, and managing local supply transparency through mandatory state-level product registrations. |
| Europe | The European Chemicals Agency (ECHA) | Regulation (EU) 2019/1009 (Annex I, Part II): The core EU Fertilising Products Regulation. | Harmonizing the internal European market via CE-marking, enforcing strict limits on heavy metal contaminants, regulating specialized stabilization additives |
| China | SAMR (State Administration for Market Regulation) | MARA Decree No. 8 (Articles 7 to 12): The administrative rules for fertilizer registration. | ecuring domestic food supplies by prioritizing internal distribution, controlling soil degradation from over-fertilization, and implementing strict export customs. |
Food Security Supporting Fertilizers
The expansion of food industries and food needs has opened profitable avenues for manufacturing nowadays. Additionally, increasing population growth, changing dietary habits, and limited agricultural land are encouraging farmers to maximize crop yields. Nitrogen fertilizers play a vital role in improving plant growth, productivity, and soil nutrient balance. Furthermore, governments across many countries are supporting agricultural modernization and food security programs, which are increasing fertilizer consumption.
Environmental Concerns Restriction
The increasing environmental concern related to excessive fertilizer usage is expected to create growth barriers for the industry during the forecast period. The overapplication of nitrogen fertilizers can contribute to soil degradation, water pollution, greenhouse gas emissions, and nutrient runoff. In recent years, governments and environmental organizations have introduced stricter regulations regarding fertilizer application and emissions control.
Precision Agriculture Opportunities
The development of smart and sustainable fertilizer solutions is anticipated to unlock innovative business opportunities for producers in the coming years. In the current period, farmers are increasingly seeking products that improve nutrient efficiency while reducing environmental impact. Enhanced efficiency fertilizers, controlled-release formulations, and precision agriculture technologies are creating new growth opportunities. Furthermore, the rise of green ammonia production powered by renewable energy is opening new investment avenues for manufacturers.
The urea segment dominated the market with 36% share in 2025, akin to it offers high nitrogen content, cost-effectiveness, easy availability, and broad crop compatibility. In the current period, urea remains the most widely used nitrogen fertilizer across cereals, grains, oilseeds, fruits, and vegetable cultivation. Farmers prefer urea because it delivers rapid plant growth while remaining affordable compared to several alternative nitrogen sources. Furthermore, established production infrastructure and extensive distribution networks have strengthened its market position globally.
 The ammonia segment held the 13% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.90% in the forecast period, owing to it serves as the foundation for most nitrogen fertilizer production. In recent years, increasing investments in green ammonia and low-carbon ammonia technologies have transformed market dynamics. Furthermore, ammonia is gaining attention not only as a fertilizer feedstock but also as a potential hydrogen carrier and clean energy solution. Governments and industries are supporting ammonia-related projects to achieve sustainability targets and reduce carbon emissions.
Nitrogenous Fertilizer Market Share, By Product, 2025 (%)
| By Product | Revenue Share, 2025 (%) |
| Urea | 36% |
| Methylene Urea | 6% |
| Ammonium Nitrate | 15% |
| Ammonium Sulfate | 11% |
| Ammonia | 13% |
| Calcium Ammonium Nitrate | 9% |
| Other Products | 10% |
The cereals & grains segment dominated the market with 46% share in 2025, owing to crops such as wheat, rice, corn, and barley require significant nitrogen inputs to achieve high productivity levels. In the current period, these crops represent the largest share of global agricultural production and food consumption. Farmers depend on nitrogen fertilizers to improve grain quality, crop growth, and overall yield performance. Furthermore, government food security initiatives often prioritize cereal production due to its importance in feeding growing populations.
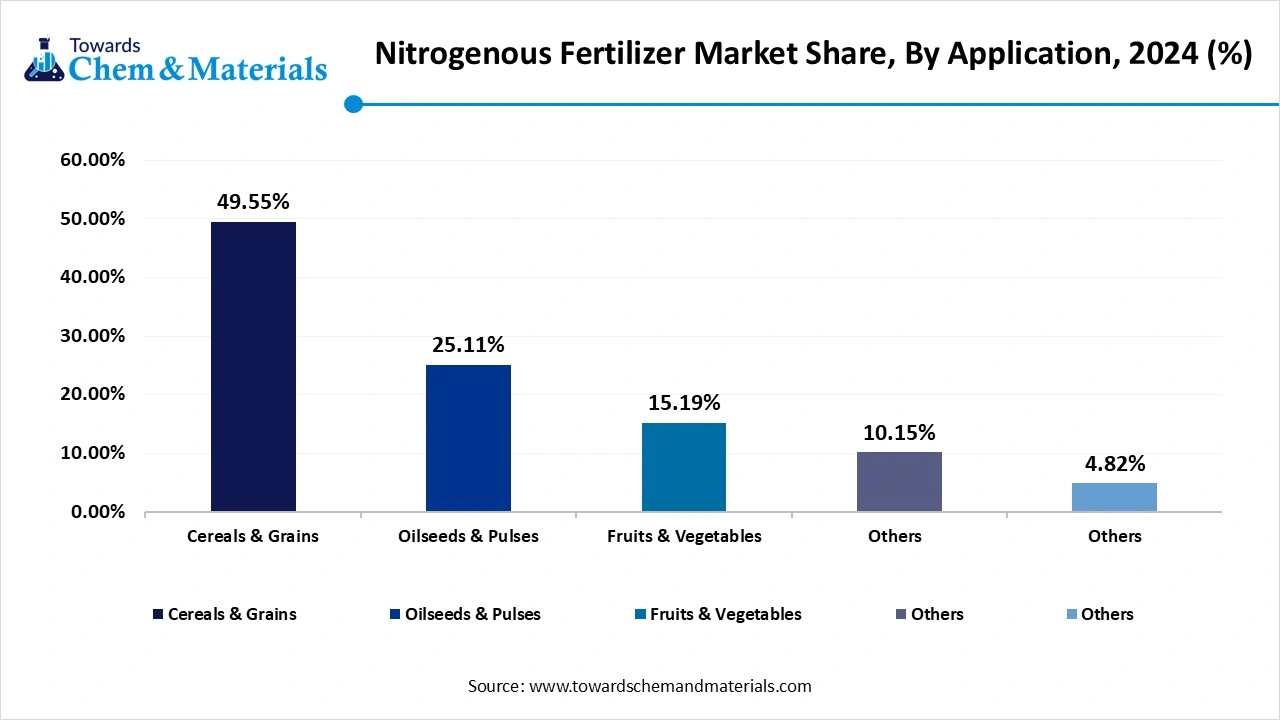
The fruit & vegetables segment held the 20% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 6.90% in the forecast period, owing to consumers are increasingly seeking healthier diets and nutrient-rich food products. In recent years, demand for fresh produce has increased significantly across both developed and emerging economies. Farmers are expanding fruit and vegetable cultivation to meet rising market demand, creating greater fertilizer requirements. Furthermore, controlled-environment agriculture, greenhouse farming, and precision horticulture are becoming more common. These production systems require accurate nutrient management, supporting nitrogen fertilizer consumption.
Nitrogenous Fertilizer Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Cereals & Grains | 46% |
| Oilseeds & Pulses | 22% |
| Fruits & Vegetables | 20% |
| Other Applications | 11% |
How will Asia Pacific Dominate the Nitrogenous Fertilizer Market in 2025?
The Asia Pacific nitrogenous fertilizer market size was estimated at USD 47.92 billion in 2025 and is projected to reach USD 86.02 billion by 2035, growing at a CAGR of 6.02% from 2026 to 2035.Asia Pacific dominated the market with a share of 70% in 2025, due to it containing some of the world's largest agricultural economies and highest population concentrations. Countries across the region require substantial food production to meet growing demand. Furthermore, extensive cultivation of rice, wheat, corn, and other staple crops supports continuous fertilizer consumption. Government support programs, fertilizer subsidies, and expanding agricultural modernization initiatives are strengthening market growth.

China
Japan
Nitrogenous Fertilizer Market Evaluation in Europe
The Europe nitrogenous fertilizer market size was estimated at USD 5.48 billion in 2025 and is projected to reach USD 10.37 billion by 2035, growing at a CAGR of 6.59% from 2026 to 2035.Europe is notably growing with 8% market share in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 6.50% in the forecast period, owing to the its aggressive sustainability targets and ongoing transition toward low-carbon fertilizer production. In recent years, governments and industry participants have invested heavily in green ammonia, renewable energy integration, and carbon reduction technologies. Furthermore, environmental regulations are encouraging the adoption of advanced fertilizers that improve nutrient efficiency and reduce emissions. Precision agriculture is becoming increasingly widespread across European farming systems.
Germany
Italy

North America Nitrogenous Fertilizer Industry Conditions
The North America nitrogenous fertilizer market size was estimated at USD 6.85 billion in 2025 and is projected to reach USD 12.81 billion by 2035, growing at a CAGR of 6.46% from 2026 to 2035.North America held the 10% market share in 2025, owing to increasing adoption of precision agriculture, advanced farming equipment, and sustainable nutrient management practices. In recent years, farmers have increasingly focused on maximizing productivity while reducing environmental impacts. Furthermore, substantial investments in green ammonia, carbon capture technologies, and low-carbon fertilizer production are supporting industry expansion.
United States
Canada
Nitrogenous Fertilizer Market Survey in Latin America
The Latin America nitrogenous fertilizer market size was estimated at USD 4.79 billion in 2025 and is projected to reach USD 9.15 billion by 2035, growing at a CAGR of 6.69% from 2026 to 2035.Latin America held the 7% market share in 2025 due to expanding agricultural exports and increasing cultivation of high-demand crops. The region plays a vital role in global food supply chains, creating strong fertilizer demand. Furthermore, rising investments in agricultural productivity improvement programs are encouraging greater adoption of nutrient management practices. Also, the expansion of soybean, corn, sugarcane, and specialty crop production continues to support market growth.
Brazil
Argentina
Middle East and Africa Nitrogenous Fertilizer Sector Observation
The Middle East and Africa nitrogenous fertilizer market size was estimated at USD 3.42 billion in 2025 and is projected to reach USD 6.71 billion by 2035, growing at a CAGR of 6.97% from 2026 to 2035.The Middle East and Africa held the 5% market share in 2025, akin to increasing investments in food security, agricultural modernization, and fertilizer manufacturing capacity. Many countries are seeking to reduce dependence on food imports by improving domestic agricultural productivity. Furthermore, the region possesses significant natural gas resources that support ammonia and fertilizer production. Governments are investing in irrigation systems, desert agriculture projects, and sustainable farming technologies.
Saudi Arabia
UAE
Competition in the nitrogenous fertilizer market is no longer based only on production capacity. Leading companies are increasingly focusing on clean ammonia, lower emissions, energy efficiency, and digital farming solutions. Also, companies are building partnerships with energy, hydrogen, and logistics businesses to strengthen their global presence.
| Sr.No | Organization | Headquarters | Nation | What offering to the Industry Growth | Major Services |
| 1 | Yara International ASA | Oslo | Norway | Accelerates modern market expansions by spearheading the commercialization of low-carbon green ammonia. | Mass production of synthetic agricultural minerals (including specialized urea and unique nitrates), delivery of chemical emission-reduction agents |
| 2 | Nutrien Ltd. | Saskatoon, Saskatchewan | Canada | Drives cross-border logistics continuity by managing a unique, integrated network that connects deep manufacturing assets straight to individual commercial farming sectors. | High-volume distribution of essential anhydrous ammonia compounds, direct-to-farm crop input retail sales, custom chemical-soil analysis blending. |
| 3 | CF Industries Holdings, Inc. | Northbrook, Illinois | United States | Guarantees market predictability through massive, high-volume capacity scaling across core industrial hubs | Bulk manufacturing of raw anhydrous ammonia blocks and fluid mixtures (such as intensive liquid UAN), large-scale maritime and rail logistics terminal management. |
By Product
By Application
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo