
Mild Steel Market Size, Competitive Landscape Analysis Report 2035
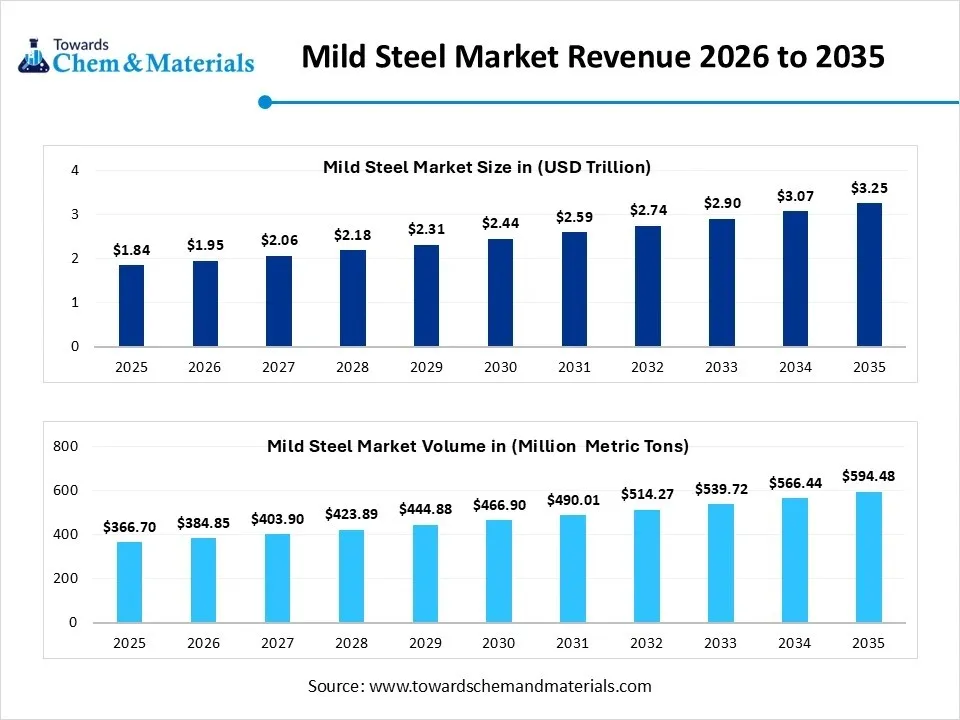
The global mild steel market size was valued at USD 1.84 trillion in 2025, is estimated to reach USD 1.95 trillion in 2026, and is projected to reach USD 3.25 trillion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.85% over the forecast period from 2026 to 2035.Asia Pacific dominated the mild steel market with the largest revenue share of 61% in 2025 and is expected to grow at the fastest CAGR of 5.95% during the forecast period. In terms of volume, the mild steel market is projected to grow from 366.7 million metric tons in 2025 to 594.5 million metric tons by 2035. growing at a CAGR of 4.95% from 2026 to 2035.The ongoing growth of machinery, equipment, and fabrication sectors is a major factor leading market growth. Also, supportive government policies and investments coupled with the soaring manufacturing and industrial activity across the globe can create new market avenues soon in the future.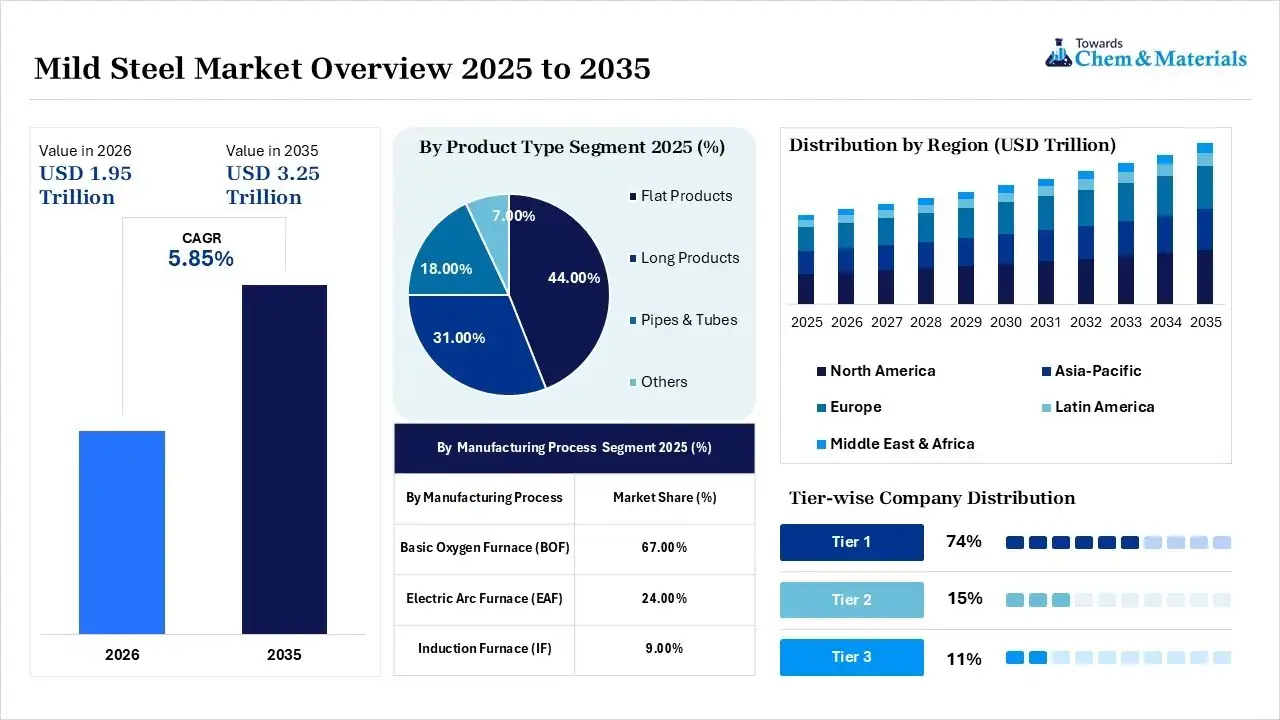
Market Highlights
- By region, Asia Pacific dominated the market with a share of 61.00% in 2025 and is expected to grow at a CAGR of 4.80% over the forecast period.
- By region, North America held a market share of 13.00% in 2025 and was expected to grow at the fastest CAGR of 5.80% over the forecast period.
- By product, the flat products segment dominated the market with the largest share of 44.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period.
- By manufacturing process, the basic oxygen furnace (BOF) segment dominated the market with the largest share of 67.00% in 2025 and is expected to grow at a CAGR of 4.70% over the forecast period.
- By manufacturing process, the electric arc furnace (EAF) segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 6.40% over the forecast period.
- By form, the coil segment dominated the market with the largest share of 33.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period.
- By form, the pipe & tube segment held a market share of 9.00% in 2025 and is expected to grow at the fastest CAGR of 5.90% over the forecast period.
- By thickness, the 3–6 mm segment dominated the market with the largest share of 38.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period.
- By thickness, the 6–12 mm segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 5.70% over the forecast period.
- By application, the building & construction segment dominated the market with the largest share of 36.00% in 2025 and is expected to grow at a CAGR of 5% over the forecast period.
- By application, the energy & power segment held a market share of 9.00% in 2025 and is expected to grow at the fastest CAGR of 6.20% during the projected period.
- By distribution channel, the direct sales segment dominated the market with the largest share of 52.00% in 2025 and is expected to grow at a CAGR of 5.10% over the forecast period.
- By distribution channel, the steel service centers segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 5.90% during the study period.
The ongoing shift towards clean and renewable energy is creating an increase in demand for mild steel, including solar farm mounting structures, wind turbine towers, offshore platform foundations, and grid modernization equipment, presenting lucrative opportunities in the market.
- In January 2026, China's first million-ton-level near-zero carbon steel facility is fully operational in Zhanjiang, Guangdong. Operated by a subsidiary of Baosteel, the plant pioneers hydrogen-based smelting to minimize fossil fuel reliance. This infrastructure integrates a 1 Mt capacity hydrogen shaft furnace, an electric arc furnace, and a continuous casting sequence.(Source: mexicobusiness.news)
- Therefore, the incorporation of threaded globe valves and other components in energy infrastructure installations further boosts demand for mild steel across the upstream and midstream energy industries over the projected period.
Global Investment Flow for Mild Steel 2025
The global investment flow for the market is undergoing a significant geographical and structural reallocation, transitioning away from standard blast furnace expansions in emerging economies such as China and increasingly transitioning towards low-carbon "green steel" technologies and developing market infrastructure.
- In June 2026, China's steel exports reached 10.341 million tonnes in May, reflecting an 8.9% month-over-month increase. However, cumulative shipments for the first five months of the year totaled 44.554 million tons.(Source: www.sunsirs.com)
The investment flows are specifically targeting emerging economies like Vietnam, Egypt, and Saudi Arabia. These countries are positioning themselves as new regional manufacturing hubs by drawing cross-border investments to build out local construction supply chains.
Mild Steel Market Trends
- The increase in automotive manufacturing across the globe is the latest trend in the market, shaping positive market growth. As advanced high-strength steels (AHSS) and aluminum alloys are replacing conventional mild steel in some structural applications and closure panels, mild steel retains growth in underbody components, brackets, and fuel tanks.
- In recent years, there has been a growing demand for steel in manufacturing military aircraft. Military aircraft need materials with excellent durability, strength, and resistance to extreme conditions. Steel, with its high reliability and strength, is a first choice for different components within these aircraft.
- Ongoing technological innovations are the future trend in the market, driving market expansion. These advancements include an extensive range of innovations, from automotive developments and artificial intelligence to the development of cutting-edge materials and production processes
AI-Powered Predictive Formulations in the Mild Steel Market
AI-powered predictive formulations in the market use data-driven and machine learning models to forecast, simulate, and optimize the microstructural properties and overall performance of low-carbon steels. Furthermore, AI frameworks are able to precisely predict key metrics such as Ultimate Tensile Strength (UTS), Yield Strength, and elongation before the steel even reaches a physical testing lab.
Supply Chain Analysis of the Mild Steel Market
Production & Processing
- It includes the creation of raw steel from iron ore via a blast furnace/basic oxygen furnace or melting scrap (via an electric arc furnace).
- The processing includes shaping and refining this steel through hot rolling, cold rolling, and coating.
ArcelorMittal: One of the world's leading steel and mining companies, operating globally with a strong presence in the Americas, Europe, and Africa. - Other Key Players: Tata Steel, Nucor Corporation
Quality Testing and Certification
- It includes standardized inspection protocols and verifies documentation utilized to prove a steel batch's physical, chemical, and mechanical properties.
These crucial steps guarantee the material's durability, load-bearing capacity, and industrial compliance with safety standards. - JSW Steel: One of India's largest integrated steel companies, utilizing modern methods of testing steel quality for structural and commercial applications.
- Other Key Players: Tata Steel, ArcelorMittal
Distribution to Industrial Users
- It includes the supply chain channels that connect major steel market players directly with downstream B2B consumers, including manufacturing, automotive, energy, and construction firms.
Distributors bypass retail traders to offer customized, bulk, and processed steel products directly to these industrial facilities. - Tata Steel: A historic legacy brand providing high-quality, flat, and long mild-steel products to construction and automotive sectors.
- Other Key Players: APL Apollo Tubes, Shyam Metalics
Mild Steel Market’s Regulatory Landscape: Global Regulations
| Country / Region | Regulatory Body | Key Regulations & Standards | Focus Areas |
| Global / International | International Organization for Standardization (ISO) | ISO 630, ISO 4950, ISO 14001, ISO 5001 | Structural steel specs, environmental management, energy efficiency |
| United States | Environmental Protection Agency (EPA), OSHA, ASTM International | Clean Air Act, ASTM A36, ASTM A513, OSHA 29 CFR | Carbon emissions, structural steel grading, workplace safety |
| European Union | European Committee for Standardization (CEN), European Commission | EN 10025, EU ETS, CBAM, Construction Products Regulation (CPR) | Structural steel standards, carbon trading, import carbon tax |
What are the Types of Mild Steel?
- Hot Rolled Mild Steel:This steel is shaped at very high temperatures (over 927°C). It is rougher and generally used for heavy structural components, like I-beams and railway tracks.
- Cold Rolled Mild Steel: Cold-rolled mild steel is produced by further rolling hot-rolled steel below its recrystallization temperature, improving surface finish, dimensional accuracy, and mechanical properties.
- Galvanized Mild Steel: Galvanized mild steel is widely used in applications where zinc coating is required to improve corrosion resistance, including outdoor structures, agricultural equipment, and selected construction products.
Market Dynamics
Driver
Surge in Investments in Energy Sector
Investments in renewable energy infrastructure are the major factor driving the growth of the market. The shift towards sustainable energy sources, like solar and wind power, needs significant amounts of steel for the construction of solar panels, turbines, and other infrastructure. In addition, this transition also aligns well with many extensive sustainability goals. As major countries are focusing on minimizing carbon emissions, the need for mild steel in energy projects is likely to rise.
Restraint
Severe Raw Material Volatility
Input costs for iron scrap, ore, and coking coal fluctuate unpredictably, which fuels structural pricing shifts, increasing mild steel prices. This is the major factor hindering the growth of the market. Moreover, growing trade barriers, retaliatory tariffs, and quotas globally complicate international trade flows and limit export prospects. Adopting clean technologies such as green hydrogen needs huge upfront investment, which is difficult for businesses to cope with.
Opportunity
Rise in Green Steel Initiatives
The ongoing investment in Electric Arc Furnaces (EAF) and hydrogen-based manufacturing addresses stringent low-carbon regulatory environments, creating lucrative opportunities in the market while fulfilling global B2B procurement needs for sustainable manufacturing materials. Furthermore, implementing Industry 4.0 standards such as real-time supply chain monitoring and AI-driven predictive maintenance allows companies to capture major market share in the near future.
Segmental Insights
Product Type Insight
The flat products segment dominated the market with the largest share of 44.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period. The dominance of the segment can be attributed to the ongoing urbanization, expanding infrastructure, and automotive production investments. In addition, the construction industry heavily relies on flat steel for roofing, cladding, and modular design because of its ease of flexibility and assembly.
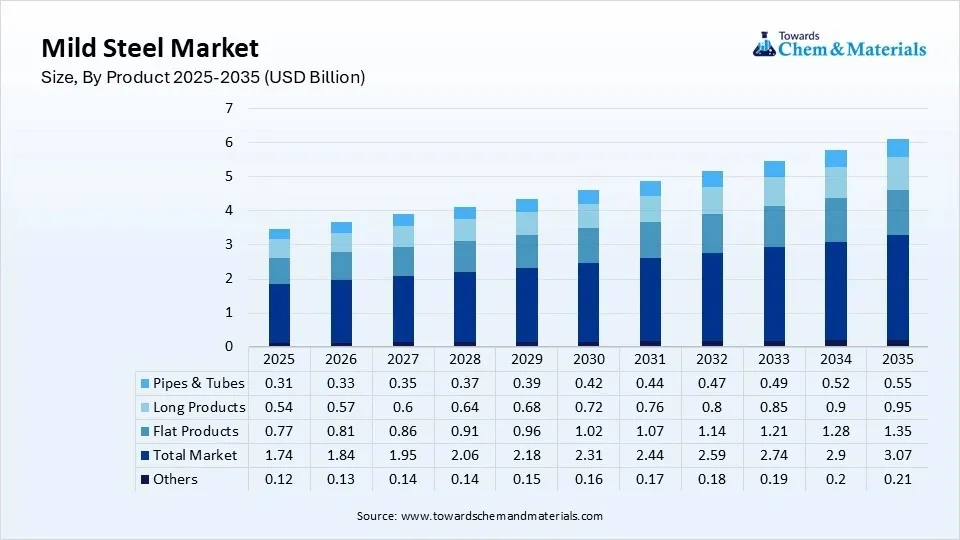
The pipes & tubes segment held a market share of 18.00% in 2025 and is projected to grow at a CAGR of 5.80% during the forecast period, according to the report’s segment forecas. The growth of the segment can be credited to its growing demand in water management and energy pipeline networks along with its cost-effectiveness. Mild steel offers exceptional ductility and weldability at a lower price point as compared to stainless or alloy steels.
Mild Steel Market Share, By Product, 2025(%)
| By Product Type | Market Share (%) |
| Flat Products | 44.00% |
| Long Products | 31.00% |
| Pipes & Tubes | 18.00% |
| Others | 7.00% |
Manufacturing Process Insight
The basic oxygen furnace (BOF) segment dominated the market with the largest share of 67.00% in 2025 and is expected to grow at a CAGR of 4.70% over the forecast period. The growth of the segment can be linked to the ongoing urbanization and advent of mega-construction projects in emerging economies. The extensive usage of mild steel sheets, bars, and long steel in shipbuilding, machinery, and consumer goods propels steady baseline growth.
The electric arc furnace (EAF) segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 6.40% over the forecast period. The growth of the segment can be driven by its lower operational costs, sustainability mandates, and scrap metal abundance. In addition, EAFs rely mainly on recycled ferrous scrap. Increasing urbanization and scrap collection infrastructures are offering a cost-effective and steady supply of raw materials.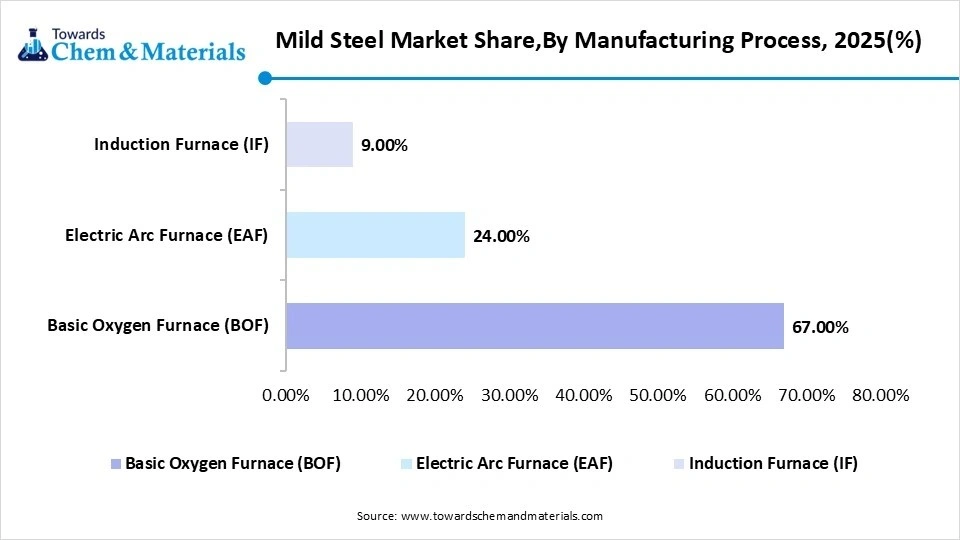
- In February 2026, ArcelorMittal confirmed a strategic €1.3 billion investment to construct an electric arc furnace (EAF) at its Dunkirk facility. Scheduled to launch in 2029, the two-million-tonne EAF will reduce CO₂ emissions by two-thirds compared to traditional blast furnaces, utilizing a mix of scrap, HBI/DRI, and hot metal.
(Source: corporate.arcelormittal.com)
Mild Steel Market Share,By Manufacturing Process, 2025(%)
| By Manufacturing Process | Market Share (%) |
| Basic Oxygen Furnace (BOF) | 67.00% |
| Electric Arc Furnace (EAF) | 24.00% |
| Induction Furnace (IF) | 9.00% |
Form Insight
The coil segment dominated the market with the largest share of 33.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period. The dominance of the segment is owing to the growing need for durable and lightweight materials across various sectors along with the surge in infrastructure investments globally. Mild steel coils are generally used in shipbuilding and consumer appliances because of their benefits.
The pipe & tube segment held a market share of 9.00% in 2025 and is expected to grow at the fastest CAGR of 5.90% over the forecast period. The growth of the segment is due to extensive infrastructure development and heavy industrialization coupled with the rise in urbanization in emerging economies. The cost-effective and abundant availability of carbon and mild steel makes it the most preferred choice for large-scale projects.
Mild Steel Market Share,By Form, 2025(%)
| By Form | Market Share (%) |
| Coil | 33.00% |
| Sheet | 18.00% |
| Plate | 16.00% |
| Bar | 12.00% |
| Rod | 8.00% |
| Pipe & Tube | 9.00% |
| Structural Steel | 4.00% |
Thickness Insight
The 3–6 mm segment dominated the market with the largest share of 38.00% in 2025 and is expected to grow at a CAGR of 5.20% over the forecast period. The growth of the segment can be attributed to the ongoing shift towards cost-effective and lightweight manufacturing. Moreover, this segment offers the crucial balance of tensile strength and weight. Mild steel in this thickness range is more formable, weldable, and inexpensive as compared to other alloys.
The 6–12 mm segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 5.70% over the forecast period. The growth of the segment can be credited to the growing demand in residential housing and extensive use of these dimensions for concrete reinforcement stirrups. Furthermore, extensive regional infrastructure, including expressways and metro rail networks, is increasingly fueling bulk procurement of this thickness still.
Mild Steel Market Share,By Thickness, 2025(%)
| By Thickness | Market Share (%) |
| Up to 3 mm | 26.00% |
| 3–6 mm | 38.00% |
| 6–12 mm | 24.00% |
| Above 12 mm | 12.00% |
Application Insight
The building & construction segment dominated the market with the largest share of 36.00% in 2025 and is expected to grow at a CAGR of 5% over the forecast period. The dominance of the segment can be linked to the increasing transition towards prefabricated modular construction and rising adoption of green building standards. Also, government spending on public infrastructure such as railways, bridges, and utilities boosts demand further.
The energy & power segment held a market share of 9.00% in 2025 and is expected to grow at the fastest CAGR of 6.20% during the projected period. The growth of the segment can be driven by growing investments in grid modernization and electric vehicle (EV) component manufacturing. Moreover, the push towards zero-emission generation technologies mainly depends on magnetic and structural steels to facilitate performance and structural integrity.
Mild Steel Market Share,By Application, 2025(%)
| By Application | Market Share (%) |
| Building & Construction | 36.00% |
| Automotive | 16.00% |
| Machinery & Equipment | 14.00% |
| Shipbuilding | 6.00% |
| Energy & Power | 9.00% |
| Railways | 5.00% |
| Consumer Goods | 8.00% |
| Agriculture | 4.00% |
| Others | 2.00% |
Distribution Channel Insight
The direct sales segment dominated the market with the largest share of 52.00% in 2025 and is expected to grow at a CAGR of 5.10% over the forecast period. The dominance of the segment can be attributed to the growing demand for smooth and large-volume supply chains coupled with the ongoing urbanization. Major market players form direct procurement contracts to ensure consistent material availability, which helps consumers to sidestep logistics delays.
The steel service centers segment held a market share of 24.00% in 2025 and is expected to grow at the fastest CAGR of 5.90% during the study period. The growth of the segment can be credited to the growing need for customized processing and localized inventory management. Also, steel service centers are crucial in bridging the gap between raw steel mills and end-users.
Mild Steel Market Share, By Distribution Channel, 2025(%)
| By Distribution Channel | Market Share (%) |
| Direct Sales | 52.00% (Dominating) |
| Steel Service Centers | 24.00% |
| Distributors & Wholesalers | 18.00% |
| Online Sales | 6.00% |
What are the Benefits of Mild Steel?
Mild steel is a highly versatile, affordable, and durable material preferred in construction and manufacturing. Its low carbon content offers exceptional malleability, high tensile strength, and better weldability, which makes it easy to cut, shape, and machine without fracturing.
The low carbon content enables electrical current to pass through smoothly without changing the structural integrity of the metal. It can be precisely and easily joined using standard welding methods without needing special preheating or expensive equipment.
Regional Analysis
How did Asia Pacific dominate the Mild Steel Market in 2025?
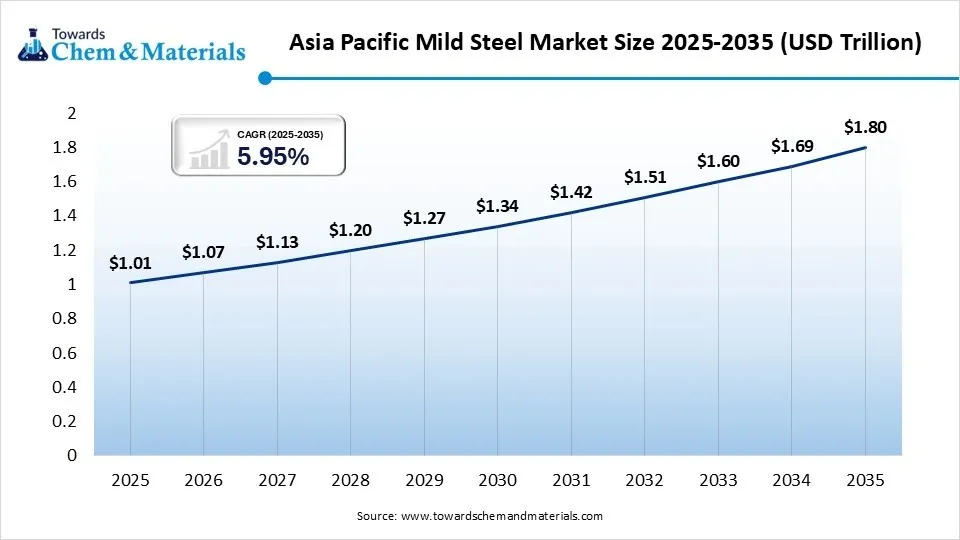
The Asia Pacific mild steel market size was estimated at USD 1.01 trillion in 2025 and is projected to reach USD 1.80 trillion by 2035, growing at a CAGR of 5.95% from 2026 to 2035. Asia Pacific dominated the market with a share of 61.00% in 2025 and is expected to grow at a CAGR of 4.80% over the forecast period. The dominance of the region can be attributed to the increasing product demand from the automotive, construction, and heavy machinery sectors along with the government investments in transportation networks. In addition, mild steel remains the material of choice because of its exceptional ductility, weldability, and high affordability.
 China
The Chinese government is heavily pumping capital into major public works, railway expansions, and green energy such as wind and solar infrastructure, which creates baseline structural steel demand. In addition, a surge in domestic and international demand for Chinese-manufactured vehicles and appliances fuels steel consumption further.
India
The integration of Industry 4.0, automation, and AI in domestic rolling mills is reducing production costs and improving product precision. Increasing incomes and domestic manufacturing pushes like the PLI scheme for specialty steel substantially increase consumption in automotive chassis manufacturing.
North America Mild Steel Market Growth Factor
The North America mild steel market size was estimated at USD 0.29 trillion in 2025 and is projected to reach USD 0.54 trillion by 2035, growing at a CAGR of 6.41% from 2026 to 2035.North America held a market share of 13.00% in 2025 and was expected to grow at the fastest CAGR of 5.80% over the forecast period. The growth of the region can be credited to the stringent energy-efficient building codes and huge government spending on public infrastructure. Robust domestic reshoring efforts and industrial automation demand equipment parts, heavy machinery, and sheet metal components.
United States
Major players in the country, such as United States Steel Corp., are investing billions in new mills and Electric Arc Furnaces (EAF), which aligns well with green production goals. Moreover, regional manufacturing is highly impacted by nationwide trade policies and tariffs.
Canada
Major domestic market players are shifting from traditional blast furnaces to sustainable electric arc furnaces (EAF) to hit environmental targets, propelling investment into modernized, high-quality production. To counter global tariffs and supply chain vulnerabilities, the federal government consistently supports projects that utilize Canadian-made steel.
Europe Mild Steel Market Growth Factor
The Europe mild steel market size was estimated at USD 0.33 trillion in 2025 and is projected to reach USD 0.60 trillion by 2035, growing at a CAGR of 6.16% from 2026 to 2035.Europe held a market share of 16.00% in 2025 and was expected to grow at a CAGR of 4.40% over the forecast period. The growth of the region can be linked to the rapid implementation of decarbonization mandates and supply chain realignments along with the shift towards green steel. Market growth is majorly reliant on customizable cutting and processing capabilities for various production demands.
Germany
Extensive investments in Germany's renewable energy targets, specifically wind turbine components, solar panel support structures, and power grid frames, are creating localized demand for structural steel and coils. Moreover, the integration of automated roll-forming, 3D modeling, and advanced metallurgical alloys is facilitating overall manufacturing efficiency.
France
An increasing shift toward modular and prefabricated steel frameworks to minimize construction times and carbon footprints is one of the major factors driving country growth. The shift to EAF production increases the industry’s reliance on electricity, which makes operations highly sensitive to energy price fluctuations.
Latin America Mild Steel Market Growth Factor
The Latin America mild steel market size was estimated at USD 0.11 trillion in 2025 and is projected to reach USD 0.21 trillion by 2035, growing at a CAGR of 6.68% from 2026 to 2035.Latin America held a market share of 5.00% in 2025 and was expected to grow at the fastest CAGR of 5% during the projected period. The growth of the region can be driven by the ongoing shift towards electric vehicles and lighter automotive components along with the rapid urbanization in the major countries. Moreover, growing demand for automotive structural parts is fuelling the consumption of hot-rolled and cold-rolled mild steel products.
Brazil
The costly Brazilian agricultural sector needs constant production and maintenance of farm equipment, storage silos, and transport, creating steady regional demand for steel plates, beams, and bars. Major players are increasingly investing billions into local downstream capacity, enhancing the scalability and precision of domestically manufactured steel products.
Argentina
Mild steel consumption is witnessing strong backing from local manufacturing, automotive production, and expanding energy operations. Also, major companies in the country are using Argentina's abundant renewable resources to manufacture green, sustainable products and reduce operational costs.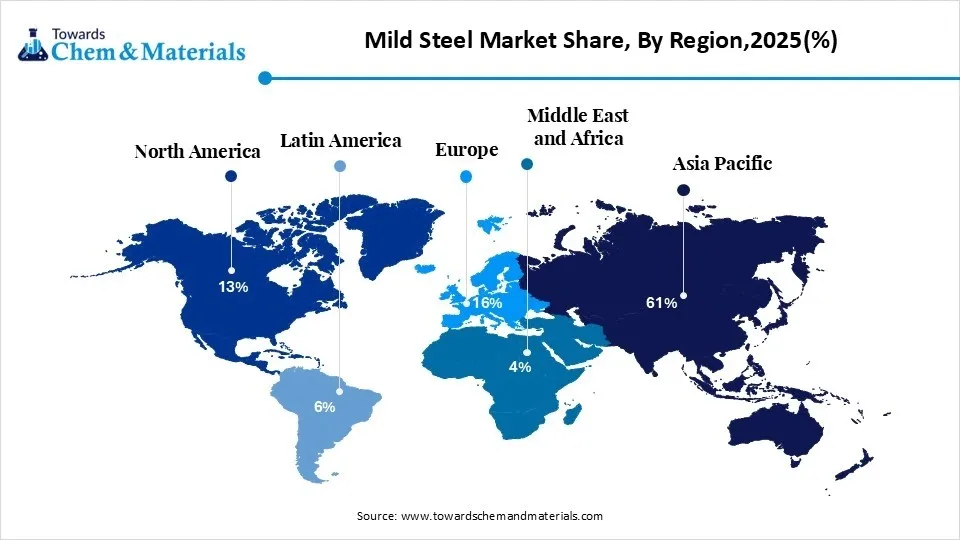
Middle East & Africa Mild Steel Market Growth Factor
The Middle East & Africa mild steel market size was estimated at USD 0.09 trillion in 2025 and is projected to reach USD 0.18 trillion by 2035, growing at a CAGR of 7.18% from 2026 to 2035.The Middle East & Africa held a market share of 5.00% in 2025 and was expected to grow at a CAGR of 5.30% over the forecast period. The growth of the region can be attributed to the extensive smart city and infrastructure investments along with the transition towards modular construction methods. Furthermore, substantial investment by major regional players is increasing domestic steel production.
Saudi Arabia
The shift towards renewable energy needs significant mild steel fabrication for utility-scale solar and wind infrastructure. New local production hubs for the defense, automotive, and heavy machinery segments are generating flat-steel consumption streams away from conventional construction, leading to country growth soon.
UAE
The UAE government has enforced policies that encourage the use of locally sourced and produced steel. This impels domestic mills and processing hubs based in strategic manufacturing zones such as Dubai to scale their operations and fulfil regional demands.
Competitive Analysis
The market remains highly consolidated yet fiercely competitive, fuelled by strong infrastructure demand and increasing manufacturing compliance costs. Major market players are transitioning their emphasis towards electric arc furnace (EAF) manufacturing, 'green steel' investments, and localized scrap policies.
ArcelorMittal is strategically allocating capital toward high-return opportunities to drive sustainable growth. The corporation is advancing its high-quality renewable energy portfolio, scaling Electric Arc Furnace (EAF) capacity to satisfy the growing demand for low-carbon steel.
- Nippon Steel Corporation is highlighting its mild steel strategy for expanding its global production footprint, transitioning to integrated electric arc furnace (EAF) "green steel" production.(Source: cdn.arcelormittal.com )
(Source:gmk.center )
Recent Developments
- In October 2025, Steel Dynamics, Inc. introduced BIOEDGE™ and EDGE™, two new lower-embodied-carbon steel product lines designed to assist clients in meeting their greenhouse gas reduction and sustainability objectives. Both product offerings are manufactured using electric arc furnace (EAF) technology.(Source: www.prnewswire.com)
Strategic Profiles of Key Players Shaping the Mild Steel Market
| Company | Company Type / Position | Headquarters | Geographic Presence | Offerings | Key Offering / Strength |
| ArcelorMittal | Integrated Global Tier-1 Producer / Market Leader | Luxembourg | Europe, Americas, Asia, Africa | Hot-rolled, cold-rolled, and galvanized mild steel sheets, coils, and structural sections | Massive global supply chain scale and advanced automotive-grade low-carbon mild steel variants |
| China Baowu Steel Group | State-Owned Enterprise / Largest steel producer by 2025 crude-steel production | Shanghai, China | Asia-Pacific dominance with an expanding global export footprint | Heavy mild steel plates, commercial sheets, wire rods, and structural profiles for infrastructure | Unmatched production capacity, cost-leadership, and high-volume supply reliability |
| Nippon Steel Corporation | Premium Integrated Manufacturer / Technological Innovator | Tokyo, Japan | Asia manufacturing base with joint ventures in the Americas and Europe | High-purity mild steel sheets, formable cold-rolled coils, and specialized structural steels | Superior material consistency, strict quality control, and advanced formability for manufacturing |
- POSCO Holdings
- Nucor Corporation
- HBIS Group
- Ansteel Group
- Jiangsu Shagang Group
- Tata Steel Limited
- JSW Steel
Mild Steel Market Segments
By Product Type
- Flat Products
- Hot-Rolled Coil (HRC)
- Cold-Rolled Coil (CRC)
- Steel Plates
- Steel Sheets
- Long Products
- Rebars
- Wire Rods
- Merchant Bars
- Structural Sections
- Pipes & Tubes
- Seamless Pipes
- Welded Pipes
- Hollow Sections
- Others
- Strips
- Flats
- Profiles
By Manufacturing Process
- Basic Oxygen Furnace (BOF)
- Electric Arc Furnace (EAF)
- Induction Furnace (IF)
By Form
- Coil
- Sheet
- Plate
- Bar
- Rod
- Pipe & Tube
- Structural Steel
By Thickness
- Up to 3 mm
- 3–6 mm
- 6–12 mm
- Above 12 mm
By Application
- Building & Construction
- Automotive
- Machinery & Equipment
- Shipbuilding
- Energy & Power
- Railways
- Consumer Goods
- Agriculture
- Others
By Distribution Channel
- Direct Sales
- Steel Service Centers
- Distributors & Wholesalers
- Online Sales
By Regions
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.