
Low-Density Polyethylene (LDPE) Market Size, Competitive Landscape Analysis Report 2035
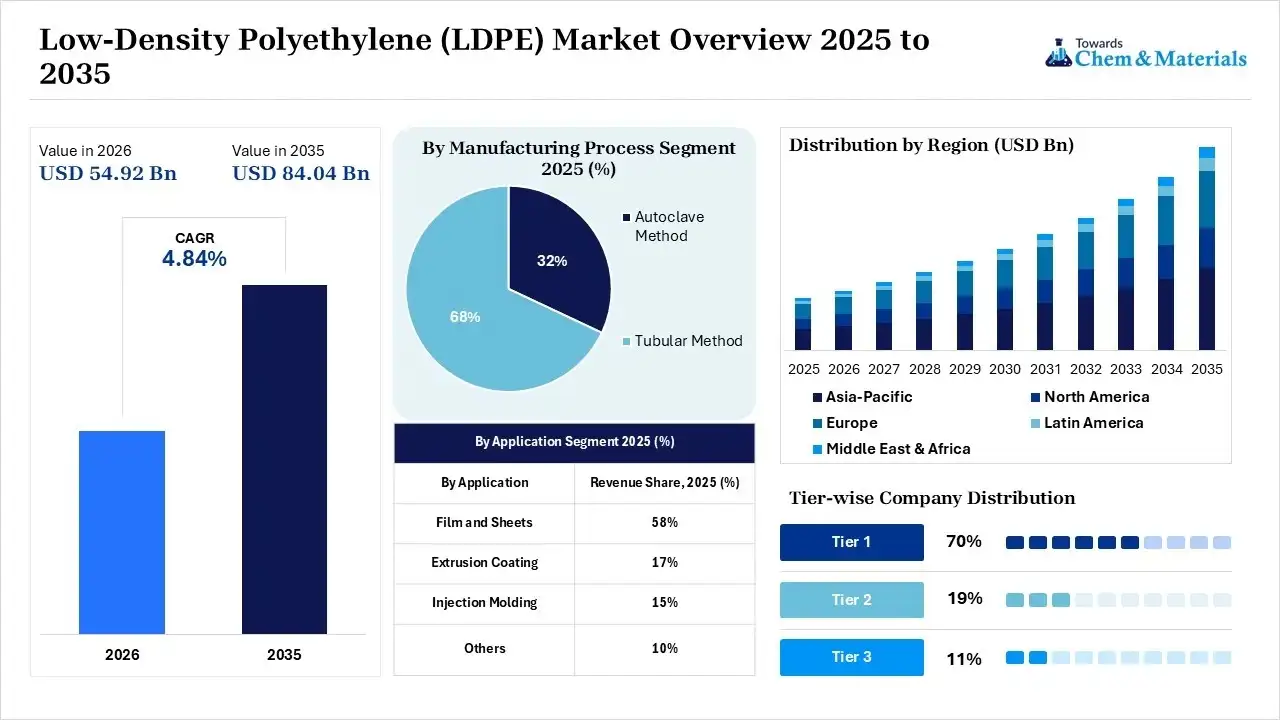
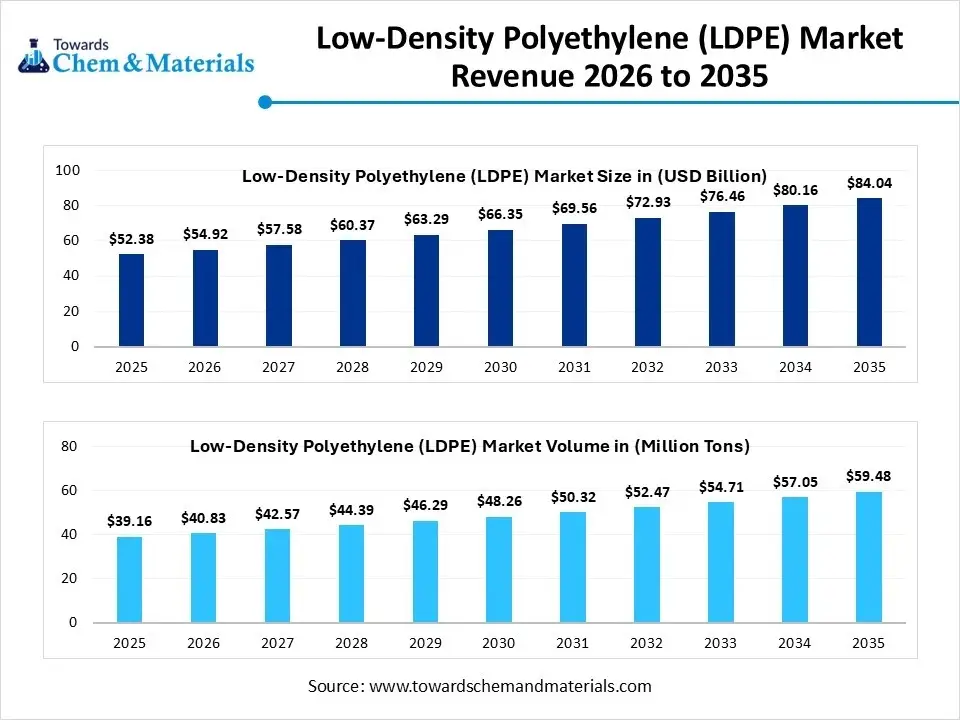
The global low-density polyethylene (LDPE) market size was valued at USD 52.38 billion in 2025, is estimated to reach USD 54.92 billion in 2026, and is projected to reach USD 84.04 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 4.84% over the forecast period from 2026 to 2035.Asia Pacific dominated the low-density polyethylene market with the largest revenue share of 46% in 2025 and is expected to grow at the fastest CAGR of 4.96% during the forecast period. In terms of volume, the low-density polyethylene market is projected to grow from 39.16 million tons in 2025 to 59.48 million tons by 2035. growing at a CAGR of 4.27% from 2026 to 2035.Food, pharmaceutical, and e-commerce are the key application areas that are driving the growth of the market. Growth in the use of these in agricultural film, medical packaging, and wire and cable insulation, as well as substantial investment in recyclable and bio-based LDPE grades, is additionally bolstering market expansion.
Market Highlights
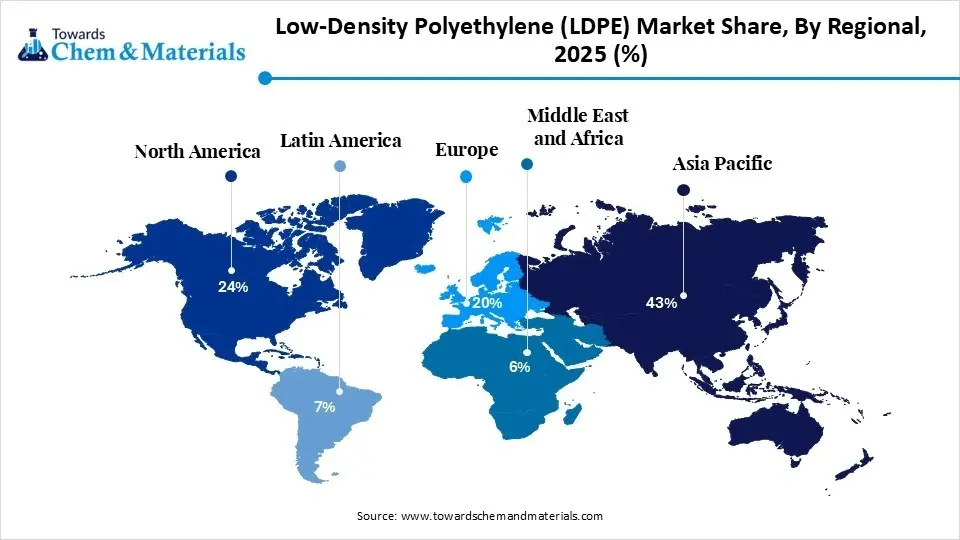
- By region, Asia Pacific dominated the market share 43% in 2025. the growth is driven by rapid industrialization, urbanization, and an increasing middle-class population.
- By manufacturing process, the tabular method segment dominated the market share 68% in 2025. The increasing demand for premium-grade LDPE drives the growth.
- By application, the film and sheets segment dominated the low-density polyethylene (LDPE) market share 58% in 2025. Rising demand for sustainable and eco-friendly alternatives drives the growth of the market.
The market of Low-Density Polyethylene (LDPE) continues to grow because of its applications in flexible packaging, agricultural films, cable insulation, consumer goods, and medical applications. The expansion of e-commerce and packaged food markets has made the packaging materials lightweight, durable, and moisture-resistant. The increasing penetration of renewable energy systems, EV charging stations, and telecommunication networks is also contributing to LDPE usage in wire and cable.
In addition, sustainability initiatives are also leading the way in innovation of recyclable, chemically recycled, and bio-based LDPE grades for the goals of the circular economy. Medical packaging applications are also emerging as a lucrative growth segment due to the rising demand for sterile and high-purity packaging.
- For instance, in January 2026, Braskem released its I'm green™ bio-based LDPE grade for healthcare and hygiene packaging applications, which provides material from renewable feedstock that has a negative cradle-to-gate carbon footprint, high stiffness, and temperature resistance.(Source: www.braskem.com)
Rising Demand for Durable and Flexible Materials
Low-density polyethylene is a type of thermoplastic polymer that is made from the monomer ethylene, with having the properties like flexibility, low density, and high ductility, which results from its highly branched molecular structure. This structure gives the LDPE its characteristics, like lightweight, chemical resistance, waterproofing, and easy processing into thin films and sheets. They are commonly used in plastic bags, packaging films, containers, insulation for wires and cables, and various other consumable goods.
The drivers for the growth of the low-density polyethylene (LDPE) market are the rising demand for flexible and lightweight packaging across various industries, including food and beverage, pharmaceuticals, and consumer goods. LDPE’s excellent moisture barrier properties, durability, and ease of processing make it ideal for applications such as films, bags, and wraps.
Additionally, the rapid growth of e-commerce has increased the need for protective and adaptable packaging materials. Furthermore, the rapid urbanization and infrastructure development, especially in emerging economies, are driving the use of LDPE in construction films, insulation, and agricultural applications, further fueling market expansion.
Market Trends
- The growing demand for sustainable and recycled LDPE due to the shift towards biobased LDPE and environmental regulation has helped the market to grow.
- The surge in demand for lightweight, flexible, and moisture-resistant packaging for e-commerce, food, and pharmaceuticals drives the market's growth.
- Innovation and technological advancement in processing and manufacturing methods, like autoclave and tubular methods, improve and strengthen the process efficiency.
- Use of AI and IoT for process optimization and digitalization in supply chain management, especially in logistics, inventory, and quality control, helps the market to grow.
Market Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 54.92 Billion/ 40.83 Million Tons |
| Expected Size by 2035 | USD 84.04 Billion/ 59.48 Million Tons |
| Growth Rate from 2025 to 2035 | CAGR is 4.84% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Manufacturing Process, By Application, By Region |
| Key Companies Profiled | Braskem, Chevron Phillips Chemical Company, INEOS, Mitsui Chemicals Inc., Formosa Plastics Corporation, Reliance Industries Limited, SABIC, Sasol, LyondellBasell Industries Holdings B.V, China Petrochemical Corporation, Shell, Petkim Petrokimya Holding A.Åž, Qatar Petrochemical Company (QAPCO) Q.P.J.S.C., Exxon Mobil Corporation, BASF SE |
Market Opportunity
The Growing Demand for Sustainable and Recyclable Packaging Solutions
One significant opportunity in the low-density polyethylene (LDPE) market is the increasing demand for sustainable and recyclable packaging materials, particularly in emerging economies. As environmental regulations tighten and consumer awareness around plastic pollution grows, companies are actively seeking eco-friendly alternatives to conventional plastics, which drives the growth of the market.
This shift creates a favorable market environment for LDPE manufacturers that can innovate with recycled or bio-based LDPE solutions. By investing in advanced recycling technologies and sustainable production methods, manufacturers can not only meet regulatory requirements but also tap into a growing segment of environmentally conscious consumers, thus gaining a competitive edge and unlocking new revenue streams.
Market Challenge
The Growing Regulatory Pressure and Ban on Single-Use Plastic
A major challenge in the low-density polyethylene (LDPE) market is the growing regulatory pressure and backlash against single-use plastics. Governments worldwide are implementing bans and restrictions on plastic bags and packaging, which are key applications for LDPE.
This has forced manufacturers to adopt recycled content, which is costly and technologically demanding which ultimately hindering the growth and is a challenge. The inconsistent recycling infrastructure is also a big limitation and challenge to overcome.
Supply Chain Analysis of the Low-Density Polyethylene (LDPE) Market
Feedstock Procurement
- The process includes the sourcing of ethylene obtained mainly from natural gas liquids and the naphtha cracking process that are used as primary raw materials for the production of LDPE. The availability, stability, and efficiency of the feedstocks are important factors in production costs and the supply of polyethylene resins to the downstream producers.
- ExxonMobil Chemical Company: A major global refiner and producer of ethylene and petrochemical feedstocks, with integrated refining and petrochemical operations to supply large-scale ethylene production for LDPE manufacturing.
- Other Key Players: LyondellBasell Industries, SABIC
Chemical synthesis and processing.
- In this step, ethylene monomers are subjected to high-pressure free-radical polymerization to give LDPE resin having a branched structure of its molecules. Advanced reactor technologies increase the efficiency of production, consistency of the product, and utilization of the energy, while allowing manufacturers to satisfy the increasing demand of the packaging, agriculture, and industrial sectors.
- Dow Inc.: One of the world's largest producers of LDPE that applies sophisticated polymerization technologies to create high-value-added LDPE grades for global applications in packaging, industrial, and specialty markets.
- Other key players: Reliance Industries Limited, Sinopec.
Compound Formulation and Blending
- It contains additives like antioxidants, UV stabilizers, slip agents, and processing aids, which improve the flexibility and durability, weather resistance, and processing performance of LDPE resin. Special formulations allow LDPE to be used in various packaging films, also in agricultural covers, medical products, and cable insulation.
- INEOS Group: Formulates specialty polyethylene products for enhanced processing characteristics and end product properties in a variety of industrial and packaging applications.
- Other Key Players: SABIC, Dow Inc.
Market Segmental Insights
Manufacturing Process Insights
The autoclave method segment dominated the low-density polyethylene (LDPE) market share 32% in 2025. The autoclave process is one of the two primary methods used to manufacture Low-Density Polyethylene (LDPE). In this process, polymerization of ethylene occurs at very high pressures and elevated temperatures around 200–300°C in a stirred high-pressure reactor, or autoclave.
The high-pressure conditions promote the formation of long-chain branching, giving LDPE its distinctive properties like softness, flexibility, high clarity, and good impact resistance. LDPE produced through the autoclave process is especially suitable for high-quality films, coatings, and pharmaceutical or food-grade packaging, where optical clarity and mechanical flexibility are crucial.
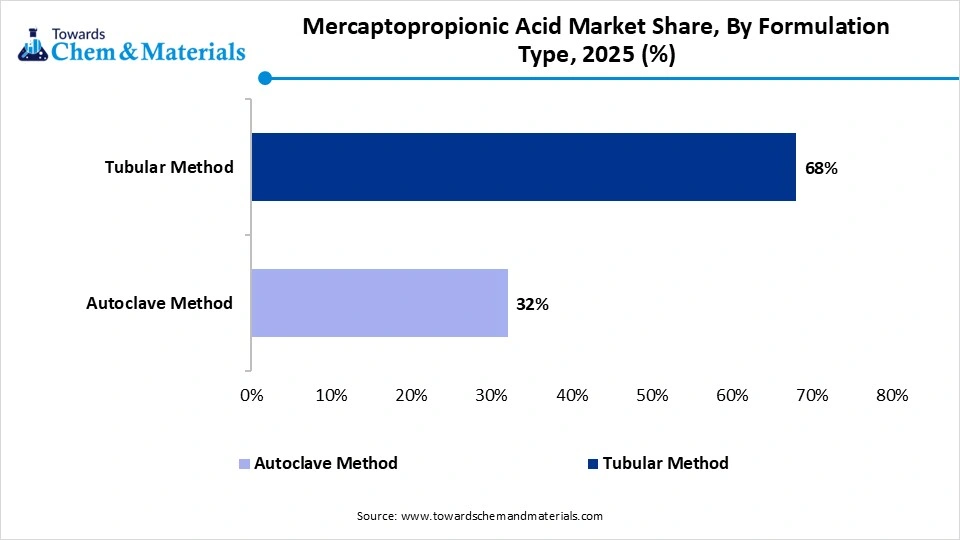 While this process is more energy-intensive and costly than the tubular method, it allows for better control over molecular structure, resulting in premium-grade LDPE, which increases the demand for the segment and helps in the expansion of the market.
The tubular method segment expects significant growth in the low-density polyethylene (LDPE) market during the forecast period. The tubular process is the other primary method used to produce Low-Density Polyethylene (LDPE) and differs significantly from the autoclave process.
In this method, ethylene polymerization occurs in a vertical tubular reactor at moderate pressures and high temperatures, about 200–300°C. The polymerization is initiated by a free radical catalyst, and the process occurs in a continuous flow system, where the polymer is formed and then extruded out of the reactor. The tubular process is more cost-effective and energy-efficient compared to the autoclave method, making it suitable for large-scale production of LDPE.
However, the polymer produced by this process tends to have less branching than that from the autoclave process, resulting in lower flexibility and clarity. As a result, LDPE made via the tubular process is typically used for industrial applications, such as piping, packaging films, and agricultural films, where high strength and durability are prioritized over optical properties, which drives the demand for the market in the industrial sector.
Application Insights
The film and sheets segment dominated the low-density polyethylene (LDPE) market share 58% in 2025. Film and sheet are the largest application segments in the market, accounting for a significant share due to LDPE’s excellent flexibility, moisture resistance, and lightweight properties.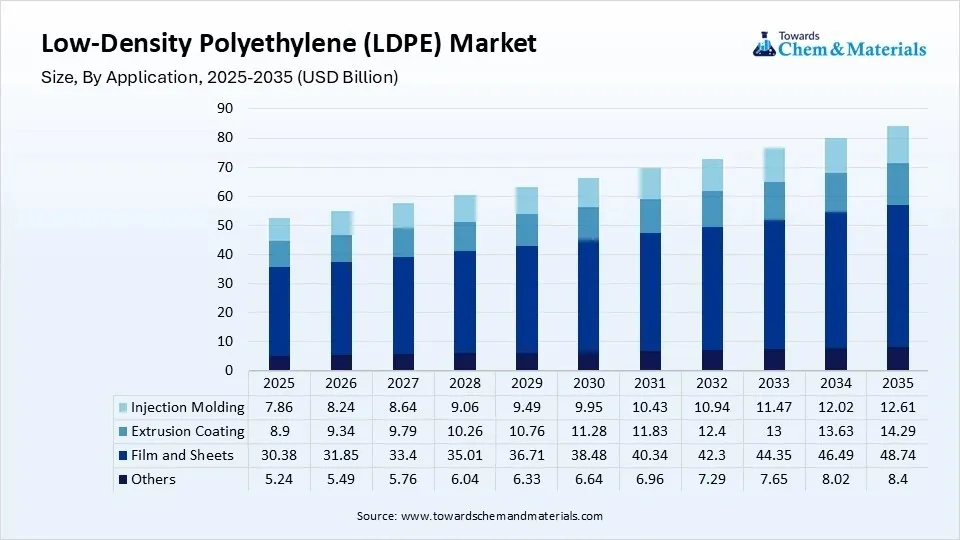
LDPE films are widely used in packaging, including grocery bags, shrink wraps, bread bags, and food packaging films, where transparency, softness, and sealing ability are essential. In agriculture, LDPE films are used for greenhouse covers, mulch films, and silage bags, providing UV protection and preserving soil moisture.
Construction-grade sheets made from LDPE are employed as vapor barriers and protective wraps due to their chemical resistance and durability. The segment benefits from the rising demand for sustainable and recyclable packaging solutions, with manufacturers increasingly integrating recycled content into film and sheet production to meet environmental regulations and consumer expectations.
The extrusion coating segment expects significant growth in the low-density polyethylene (LDPE) market during the forecast period. Extrusion coating is a key application of Low-Density Polyethylene (LDPE), where a thin layer of LDPE is melted and applied to substrates such as paper, aluminum foil, or other plastic films to enhance their properties. This process significantly improves the moisture resistance, grease barrier, and sealability of the coated material, making it ideal for liquid packaging cartons (like milk and juice boxes), food wrappers, and paper cups.
LDPE’s good adhesion, flexibility, and clarity make it a preferred material for this process. The extrusion coating segment is experiencing steady growth, especially in the food and beverage industry, driven by the rising need for hygienic and durable packaging. Additionally, advancements in multilayer coating technologies are expanding the use of LDPE in complex packaging structures that combine multiple barrier and mechanical properties, which drives the growth of the market.
Regional Insights
How did the Asia Pacific dominate the Low-Density Polyethylene (LDPE) Market in 2025?
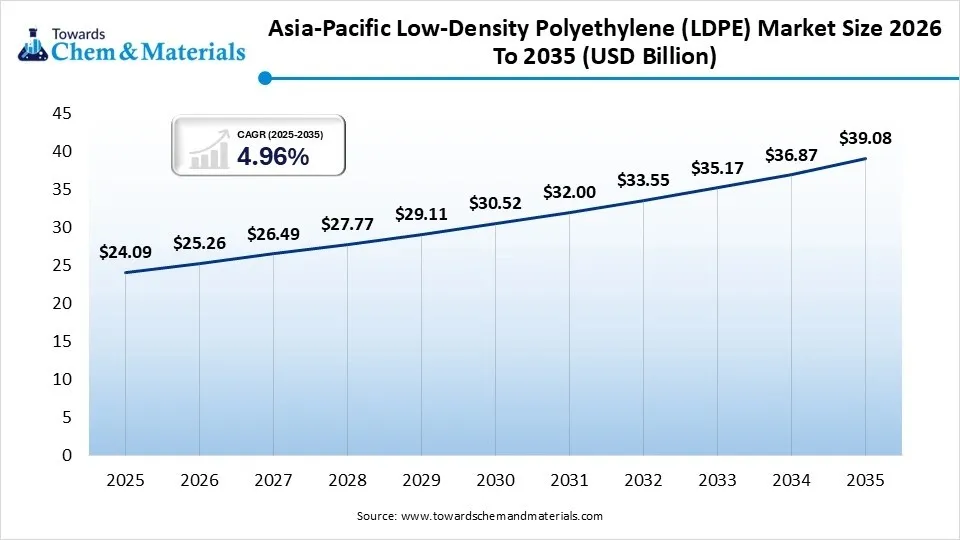
The Asia Pacific low-density polyethylene market size was estimated at USD 24.09 billion in 2025 and is projected to reach USD 39.08 billion by 2035, growing at a CAGR of 4.96% from 2026 to 2035.Asia Pacific dominated the market with 46% share in 2025, owing to its high packaging manufacturing industry, growing food processing industry, and increasing e-commerce activities. The market enjoyed the growth momentum from strong demand for flexible packaging films, agricultural covers, and consumer goods packaging. Moreover, the production capacity gains of petroleum chemicals and the rise of industrialisation in emerging economies further boosted the consumption capabilities and supply of LDPE in the region.
 China
- The large packaging manufacturing base resulted in high consumption of LDPE films, pouches, and protective wraps.
- The growth of e-commerce resulted in a rise in the need for lightweight mailers, courier bags, and stretch films.
- Large-scale production of competitive LDPE resins was possible through integrated petrochemical complexes for the converters.
India
- The expanding packaged food industry increased the demand for LDPE films, pouches, and flexible forms of packaging.
- The use of LDPE for greenhouse covers and mulch film applications was expanded with growing agricultural activities.
- As retail stores and e-commerce channels increased their share of the market, consumers' demand for affordable polyethylene-based packaging materials grew.
The North America low-density polyethylene market size was estimated at USD xx billion in 2025 and is projected to reach USD xx billion by 2035, growing at a CAGR of xx% from 2026 to 2035.North America held 21% market share in 2025 and is expected to grow at the fastest CAGR of 5.8% during the forecast period, with good demand in the food packaging, healthcare packaging, industrial films, and wire and cable insulation applications of LDPE. The cost-competitive ethylene production was made possible by the availability of abundant shale-gas-based ethylene feedstocks, while the rise of recycling ethylene and circular economy activities saw the growth of sustainable LDPE products in various industries.
United States
- Demand for LDPE films, wraps, and protective packaging was high in the strong food packaging industry.
- Nationwide, competitive LDPE manufacturing and steady availability of feedstocks were facilitated by the shale-based ethylene production.
- As recycling efforts increased, there was a growth in the development of circular and post-consumer recycled polyethylene grades.
Canada
- The growth of the packaging and consumer goods industries contributed to the high consumption of flexible LDPE-based materials.
- The country's polyethylene resin production and supply were reliable, with strong support from the petrochemical industry.
- The new sustainability goals led to the use of recyclable and recycled LDPE packaging solutions.
Europe held 18% market share in 2025, owing to the increasing demand for sustainable packaging materials and the regulations favouring the recovery of plastics. Demand drivers continued to be food, pharmaceutical, and industrial packaging applications. The investments in chemical recycling technology, bio-based polyethylene, and circular economy programs continued to drive innovation and further solidify the region's leadership in the development of sustainable LDPE.
Germany
- The growing demand for high-performance LDPE film and bag applications in the large packaging conversion industry.
- Regulations on the circular economy encouraged the use of polyethylene products that are made from recycled and renewable-feedstock products throughout the country.
- The demand for LDPE protective films and packaging materials was high in the industrial sector.
France
- Specialty LDPE grades had a strong impact on consumption in the food and pharmaceutical packaging markets.
- The rise of sustainable initiatives drove the use of bio-based and recyclable polyethylene packaging in the country.
- Continued growth of the market for LDPE was seen across industries owing to the increasing need for lightweight packaging materials.
Latin America held 8% market share in 2025, owing to an increase in the demand for packaged foods, agricultural films, and consumer products. The growing food processing industries and retail distribution networks led to the growing demand for flexible packaging materials. The demand for flexible packaging materials was high due to the expansion of retail distribution networks and food processing industries. The increased use of greenhouse films, mulch films, and protective films in agriculture also made a significant contribution to the consumption of LDPE in the region.
Brazil
- The flexible LDPE packaging application was in demand by the large food processing industry at the national level.
- Moisture-retaining mulch and greenhouse films increased with the expansion of the agricultural sector.
- Higher consumption of polyethylene packaging and film products was fueled by the increasing consumption of consumer goods.
Chile
- Demand for protective packaging applications and greenhouse film applications grew a great deal due to good agricultural exports.
- The continued demand for food packaging was a driver of steady demand for LDPE films and wraps.
- The adoption of polyethylene-based agricultural solutions all over the country was encouraged by the modernization of farming practices.
The Middle East & Africa held 7% market share in 2025, due to favourable support from the petrochemical manufacturing capabilities, a rise in packaging production, and agricultural activities. The market was expanding throughout the region with competitive LDPE production driven by the availability of abundant feedstock and the growing demand for flexible packaging, industrial liners, greenhouse films, and healthcare packaging applications.
 Saudi Arabia
- Widespread petrochemical facilities provided the world with ample supply and export potential for LDPE.
- The rising demand in demand for polyethylene films, bags, and protective wrapping materials in the growing packaging sector.
- Development projects for agriculture led to the use of LDPE greenhouse and irrigation film solutions.
South Africa
- Due to the expansion of the retail and food packaging sectors, the consumption of flexible LDPE products has risen considerably.
- Demand for polyethylene films and crop protection materials was driven by increasing agricultural activities.
- Industry packaging demands have increased the use of durable packaging solutions, based on LDPE.
Recent Developments
- In February 2026, NOVA Chemicals launched two grades of recycled polyethylene (rPE-IN3 and rPE-IN4) for non-food applications in North America. The recycled LDPE and LLDPE grades were created at the company's SYNDIGO1 mechanical recycling facility for can liners, shrink films, protective packaging, carry-out bags, and heavy-duty sacks.(Source: www.indianchemicalnews.com)
- In November 2025, Borouge introduced Bormed LE6607-PH, the first medical-grade LDPE product made in the United Arab Emirates, in November 2025. The material, which is based on Borealis' Bormed technology, was developed for pharmaceutical and medical packaging applications such as blow-fill-seal bottles, ampoules, and sterile packages for the healthcare sector.(Source: plasticstoday.com)
Top Companies List
- Braskem
- Chevron Phillips Chemical Company
- INEOS
- Mitsui Chemicals, Inc.
- Formosa Plastics Corporation
- Reliance Industries Limited
- SABIC
- Sasol
- LyondellBasell Industries Holdings B.V
- China Petrochemical Corporation
- Shell
- Petkim Petrokimya Holding A.Åž
- Qatar Petrochemical Company (QAPCO) Q.P.J.S.C.
- Exxon Mobil Corporation
- BASF SE
Segments Covered in the Report
By Manufacturing Process
- Autoclave Method
- Tubular Method
By Application
- Film and Sheets
- Extrusion Coating
- Injection Molding
- Others
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.