Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The ductile iron pipes market size was valued at USD 14.54 billion in 2025, is estimated to reach USD 15.39 billion in 2026, and is projected to reach USD 25.67 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.85% over the forecast period from 2026 to 2035.Asia Pacific dominated the ductile iron pipes market with the largest revenue share of xx% in 2025 and is expected to grow at the fastest CAGR of 5.96% during the forecast period. In terms of volume, the ductile iron pipes market is projected to grow from 12.16 million metric tons in 2025 to 20.09 million tons by 2035 growing at a CAGR of 5.15% from 2026 to 2035. The growth of the market is attributed to the high investments in water infrastructure, the growing urbanization, the demand for durable pipeline solutions, and the growing wastewater management projects. New coatings, precision centrifugal casting, and trenchless installation technologies are also being developed for pipelines, helping to enhance pipeline performance and ensure long-term market growth.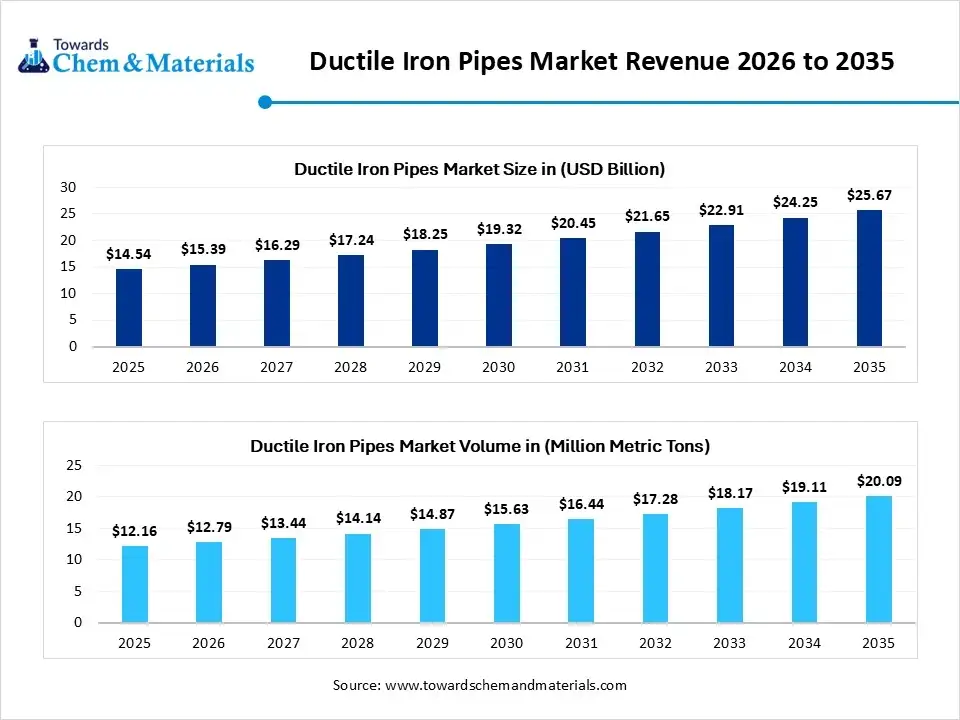
Ductile Iron Pipes are centrifugally cast-iron pipes manufactured using ductile cast iron, a type of iron known for its high strength, elasticity, and impact resistance. These pipes are extensively used in water and wastewater transportation systems due to their durability, corrosion resistance (often enhanced by linings/coatings), and long service life. Ductile iron offers better performance compared to traditional gray cast iron due to its nodular graphite inclusions. There is an increasing focus on eco-friendly water management practices; hence, these iron pipes are preferred for their long service life and durability, which makes them a crucial choice among manufacturers.
The market is growing due to rising investments in drinking water distribution, wastewater management, and the modernization of urban infrastructure in developed and emerging economies. Demand for pipeline systems that are high-strength, pressure-resistant, and government-supported is still growing, as is the use of water in industry.
The market is also expanding as a result of the availability of new opportunities for smart water grids, trenchless pipeline rehabilitation, and desalination infrastructure. Polyurethane, epoxy, ceramic, and cement mortar coatings, precision centrifugal casting technology, and joint technologies are being developed to further improve corrosion resistance, installation speed, and pipeline service life.
| Report Attributes | Details |
| Market Size in 2025 | USD 17.66 Billion |
| Market Size by 2034 | USD 32.77 Billion |
| Growth rate from 2024 to 2025 | CAGR 7.11% |
| Base Year of Estimation | 2024 |
| Forecast Period | 2025 - 2034 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Diameter, By Application, By Installation Technique, By Lining Type, By Coating Type, By End-Use Sector, By Pressure Rating, By Sales Channel, By Region |
| Key Profiled Companies | Saint-Gobain PAM (France), Jindal SAW Ltd. (India), Kubota Corporation (Japan), American Cast Iron Pipe Company (USA), U.S. Pipe (USA), Electrosteel Castings Ltd. (India), McWane Inc. (USA), Tata Metaliks (India), Benxi Beiying Iron and Steel (China), Xinxing Ductile Iron Pipes Co., Ltd. (China), AMSTED Industries (USA), Svobodny Sokol (Russia), Angang Group Yongtong Ductile Cast Iron Pipe Co., Ltd. (China), Duktus Rohrsysteme Wetzlar GmbH (Germany), Atlantic States Cast Iron Pipe Company (USA), Zhejiang Weifeng Pipe Industry Co., Ltd. (China), Shanxi Ductile Iron Pipes Co., Ltd. (China), Saint-Gobain PAM España (Spain), United Gulf Pipe Manufacturing Co. (Oman), Binhai New Area Tianjin Pipe Co. Ltd. (China) |
Stringent Government Standards
Regulatory bodies globally are mandating the use of nontoxic, safe, and anti-corrosion materials to ensure good water quality for public health. Their ability to bear high external loads and internal pressures enables them to comply with the strict performance standards fixed for industrial and municipal water systems. Furthermore, this regulatory environment propels the demand for long-lasting and long-lasting pipe materials in retrofitted water networks, creating future opportunities in the market.
Competition from Substitute Materials
Substitutes such as HDPE, PVC, and steel are the major alternatives to the ductile iron pipes in the market. These materials offer crucial benefits such as lower installation costs and corrosion resistance, hindering market growth further. Moreover, poor port and road infrastructure can delay the supply of raw materials and hence the distribution of end products, affecting the market expansion negatively.
Feedstock Procurement:
Chemical Synthesis and Processing
Compound Formulation and Blending:
The water distribution segment holds a significant share of the ductile iron pipes market, supported by the growing global emphasis on providing safe and dependable drinking water. Governments and local authorities, particularly in developing economies, are investing heavily in expanding and upgrading water supply infrastructure to meet rising demand in urban and semi-urban areas. Ductile iron pipes are widely used in these projects because they offer excellent strength, a long operational lifespan, and the ability to withstand high internal pressure as well as external loads, making them a reliable choice for water transmission and distribution networks.
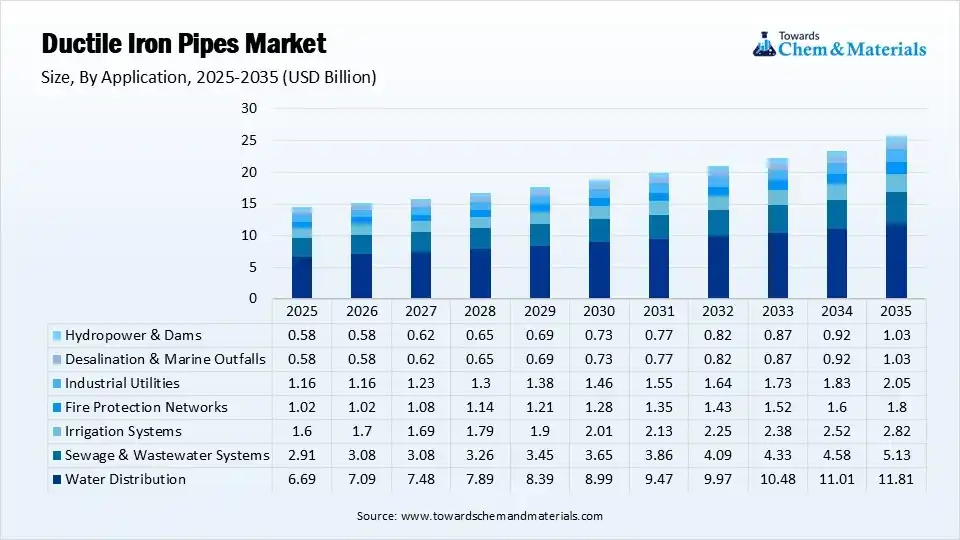 The sewage & wastewater systems segment is expected to witness the fastest growth during the forecast period. Rapid urbanization and increasing wastewater generation are driving the need for modern sewer networks that can efficiently transport large volumes of wastewater while minimizing leaks and failures. Ductile iron pipes are well suited for these systems due to their high mechanical strength, corrosion resistance, and ability to perform under challenging ground conditions and varying pressure levels. Their long service life and low maintenance requirements make them an ideal solution for both gravity-fed and pressurized wastewater infrastructure, particularly in densely populated urban areas.
How did the Asia Pacific Dominate the ductile iron pipes market in 2025?
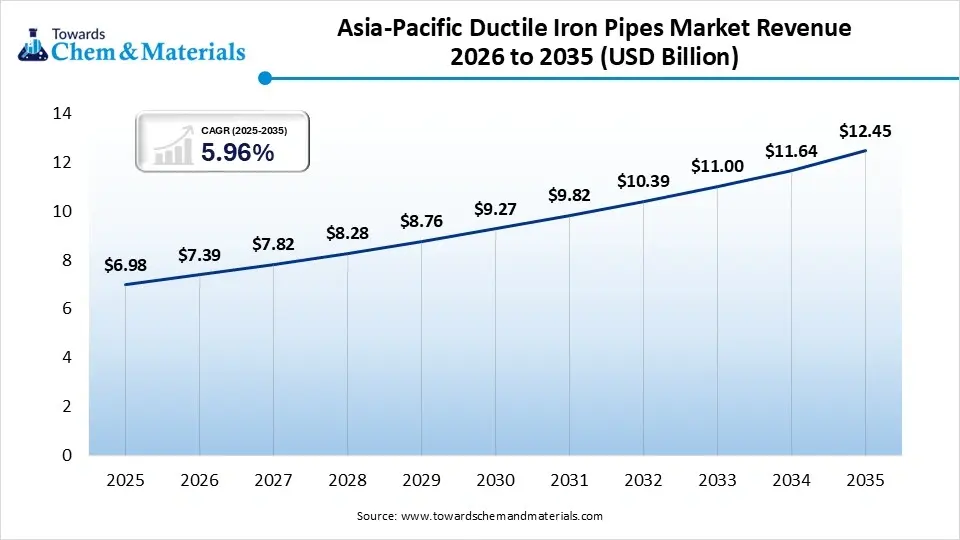
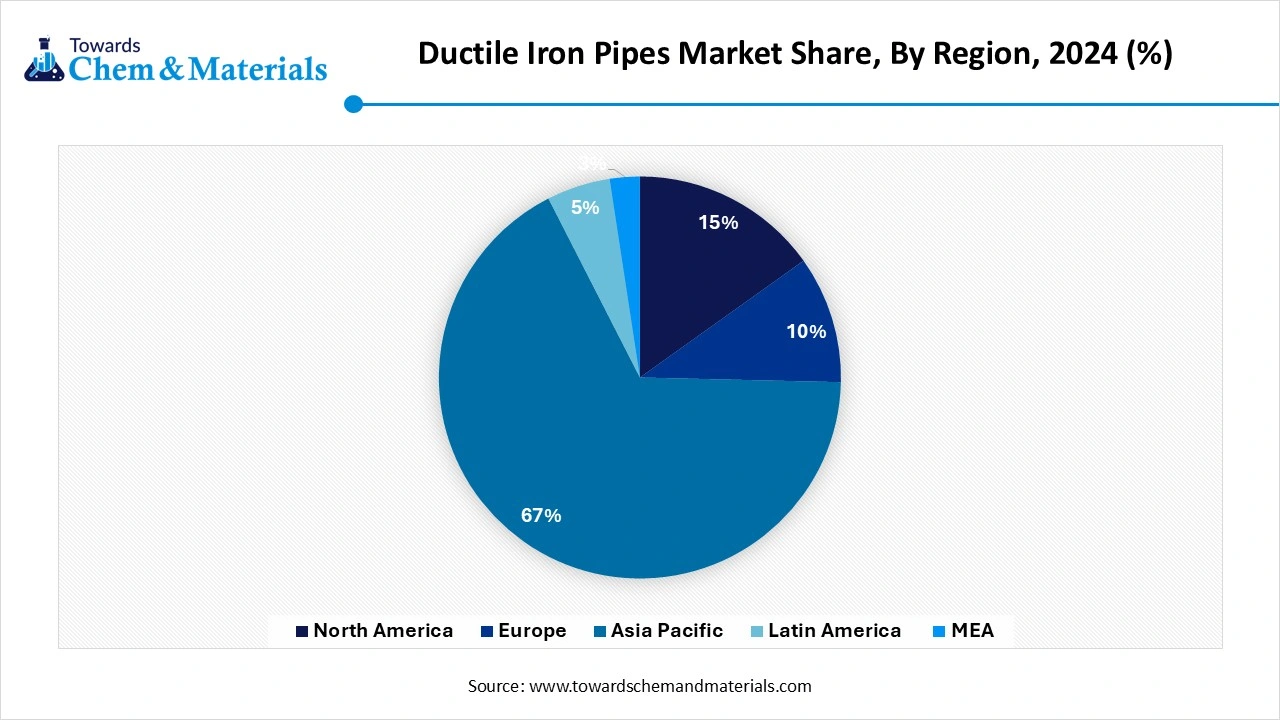
The Asia Pacific ductile iron pipes market size was estimated at USD 6.98 billion in 2025 and is projected to reach USD 12.45 billion by 2035, growing at a CAGR of 5.96% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 48% in 2025, due to the presence of a rapidly developing urban population, growing water infrastructure and rising government investments in drinking water and sanitation projects. As more industries develop and irrigation continues to grow, pipelines continue to be installed throughout the region. Further, the increased use of durable water transmission systems further bolsters the long-term growth of the market.
 China
India
North America held 17% market share in 2025 and is expected to grow at the fastest CAGR of 6.8% during the forecast period, because of aging water infrastructure, the rising investment in water infrastructure rehabilitation, and modernization of municipal pipeline networks. Utilities have a preference for the use of pipeline systems that will last a long time and have a minimal risk of corrosion affecting the water distribution system. Other attractive aspects of the region are technological developments that facilitate regional market expansion.
United States
Canada
Europe held 20% market share in 2025, as it invests in improving water facilities, introducing environmental sustainability measures and upgrading the ageing pipeline network. Regulatory requirements promote the use of pipes that are durable and recyclable such as ductile iron pipes. Pipeline quality and quality of operations are still being enhanced by technological innovation.
Germany
France
Latin America held 6% market share in 2025, because growth in the sanitation program, water distribution program, and industrial development has increased the demand for ductile iron pipes. Water supply networks are maintained by government investment for market expansion. Pipeline demand for the mining and energy industries also drives demand in the region.
Brazil
Chile
The Middle East & Africa held 9% market share in 2025, as more and more investments are made in water transmission projects, urban development, and desalination infrastructure. Increasing industrial development and water security projects enable pipeline installation. For long life of infrastructure, durable corrosion resistant pipe systems are still required.
Saudi Arabia
South Africa
By Application
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo