Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
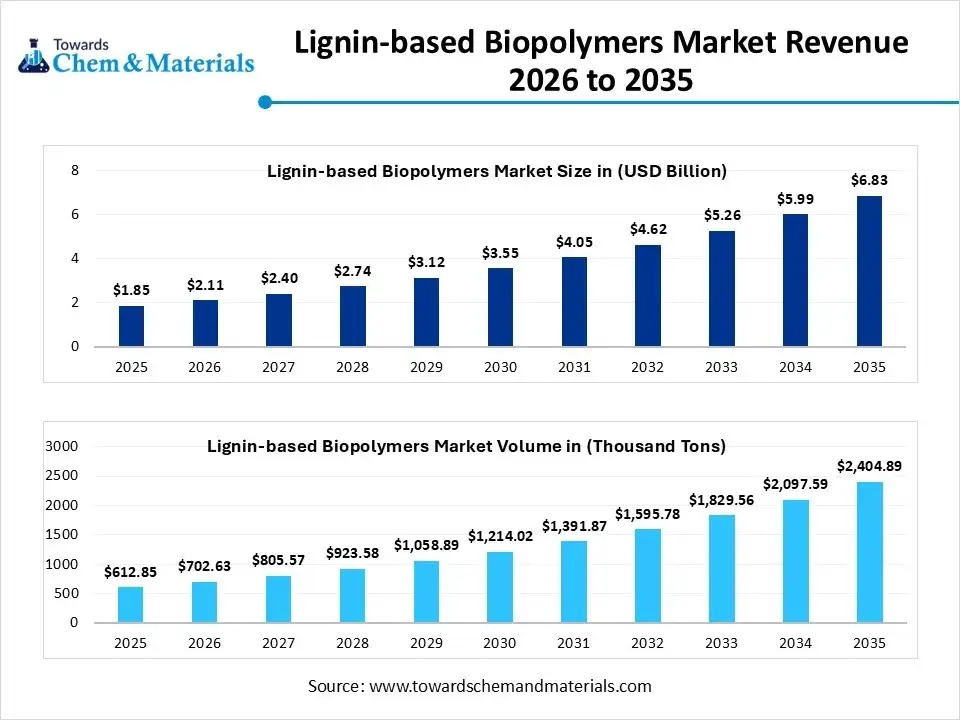
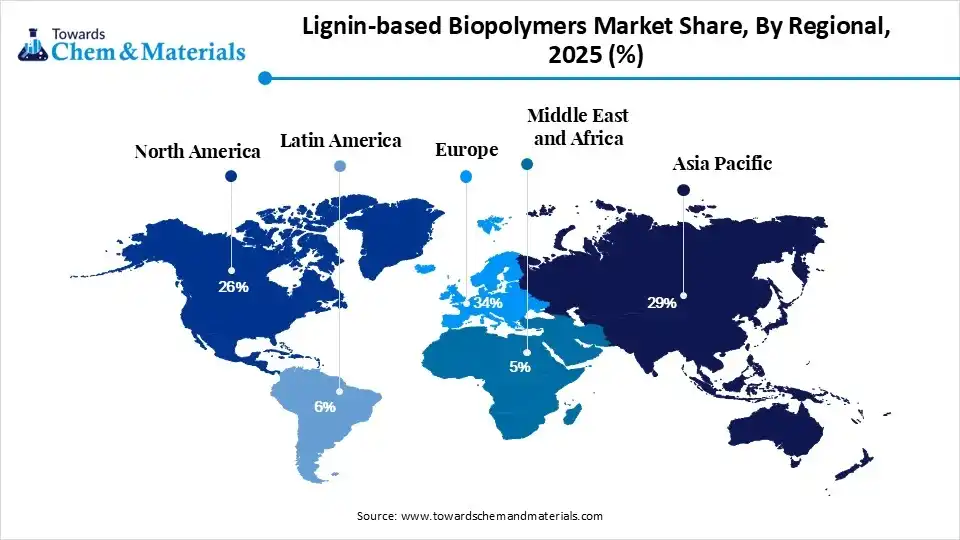
The lignin-based biopolymers market size was valued at USD 1.85 billion in 2025, is estimated to reach USD 2.11 billion in 2026, and is projected to reach USD 6.83 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 13.95% over the forecast period from 2026 to 2035.Europe dominated the lignin-based biopolymers market with the largest revenue share of 34% in 2025 and is expected to grow at the fastest CAGR of 15.81% during the forecast period. In terms of volume, the lignin-based biopolymers market is projected to grow from 612.85 thousand tons in 2025 to 2,404.89 thousand tons by 2035. growing at a CAGR of 14.65% from 2026 to 2035.The growth of the market is driven by the global shift toward a circular bioeconomy, strict environmental regulations on single-use plastics, and rising demand for low-carbon, renewable raw materials across packaging, construction, and automotive industries. Government incentives for green construction and investments, by key players, fuel the growth of the market, according to the report.
What Is the Significance of the Lignin-based Biopolymers Market?
The market for lignin-based biopolymers is highly important because it offers a scalable, low-carbon, circular economy alternative to plastics and chemicals derived from petroleum. As the second most plentiful natural polymer on Earth, lignin valorization helps decrease reliance on fossil fuels, reduce greenhouse gas emissions, and repurpose waste from the paper industry into valuable materials. Growth in this market is driven by leading companies moving towards sustainability, such as Borregaard, Stora Enso, UPM Biochemicals, MetGen, and Ingevity.
For instances,
For instances,
| Report Attributes | Details |
| Market Size and Volume in 2026 | USD 2.11 Billion/ 702.63 Thousand Tons |
| Revenue Forecast in 2035 | USD 6.83 Billion/ 2,404.89 Thousand Tons |
| Growth Rate | CAGR 13.95% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Europe |
| Segment Covered | By Product Type, By End Use, By Region |
| Key Companies Profiled | Borregaard, Stora Enso, UPM Biochemicals, MetGen & Lignolix, Ingevity, Nippon Paper Industries Co., Ltd., Asian Lignin Manufacturing Pvt. Ltd., Aditya Birla Chemicals, Prisma Renewable Substances, Valmet Oyj, Lignin Industries AB, Liquid Lignin Company LLC, Green Agrochem, Shenyang Xingzhenghe Chemical Co., Ltd., Changzhou Shanfeng Chemical Industry Co., Ltd., Burgo Group S.p.A., Domsjö Fabriker AB, Rayonier Advanced Materials / RYAM, Glonis Biotech, West Fraser |
The global lignin-based biopolymers market is experiencing rapid growth. The integration of artificial intelligence is resolving historical challenges of structural heterogeneity and feedstock variability, transitioning lignin from a low-value paper-mill byproduct into high-performance sustainable materials. AI algorithms simulate lignin behavior under thermal and chemical conditions to tailor resin and biopolymer properties like strength and thermal stability for specific applications. Platforms like LignoCity utilize smart measurements and AI matrices to develop new elastic materials and streamline lab-to-market scaling.
| Country / Region | Regulatory Body | Key Regulations | Focus Areas | Notable Notes |
| United States | Environmental Protection Agency (EPA); United States Department of Agriculture (USDA) | Toxic Substances Control Act (TSCA); USDA BioPreferred Program | Bio-based polymers, renewable feedstocks | The U.S. supports lignin-based biopolymers through green chemistry initiatives and sustainable material programs. |
| European Union | European Chemicals Agency (ECHA); European Commission | REACH Regulation; EU Circular Economy Action Plan | Biodegradable materials, circular economy | Europe promotes lignin-based polymers as sustainable alternatives to petroleum-derived plastics. |
| Canada | Natural Resources Canada (NRCan); Environment and Climate Change Canada | Canadian Environmental Protection Act | Forest biomass utilization, sustainable materials | Canada benefits from abundant forestry resources for lignin extraction and biopolymer production. |
| China | Ministry of Ecology and Environment (MEE); National Development and Reform Commission (NDRC) | Circular Economy Promotion Law; Green Manufacturing Policies | Renewable chemicals, industrial sustainability | China is increasing investment in biomass-derived polymers and lignin valorization technologies. |
| Finland | Ministry of Economic Affairs and Employment; Finnish Forest Centre | Bioeconomy Strategy; Environmental Protection Regulations | Wood-based biopolymers, sustainable forestry | Finland is a leading innovator in lignin valorization and advanced forest-based biomaterials. |
| Brazil | Ministry of Environment and Climate Change; Brazilian Development Bank (BNDES) | National Bioeconomy Policies | Biomass-based materials, renewable polymers | Brazil supports lignin-based biopolymer development through its strong pulp and paper industry infrastructure. |
| Drivers | Restrains | Opportunities |
| Circular Economy & Decarbonization: Rising demand for low-carbon, biodegradable materials that lower greenhouse gas emissions compared to traditional synthetics like PE. | Lack of Standardization: The absence of a harmonized regulatory framework or universally accepted technical benchmarks impedes downstream integration. This makes quality control difficult for precision sectors like pharmaceuticals or electronics. | Sustainable Packaging & Bioplastics:Brands are heavily utilizing bio-based materials to lower their carbon footprint. Lignin serves as an eco-friendly barrier and polymer additive that maintains packaging strength and durability. |
| Construction & Green Building: Expanding infrastructure demand for lignin-based concrete admixtures, supported by government green building initiatives such as the EU's climate-neutral targets. | Feedstock Dependency: Lignin supply is heavily dependent on the output and operational configurations of the pulp and paper industry. Any fluctuations here directly impact raw material availability and pricing. | Phenolic Resins & Wood Adhesives:Lignin-based resins improve thermal stability and mechanical strength, making them highly lucrative for foam insulation, plywood, and construction adhesives. |
| Material Versatility: Advances in fractionation technology allow lignin to be used successfully in high-value bioplastics, carbon fibers, resins, and coatings. | Competition from Mature Alternatives:It struggles to compete against established bio-based alternatives like PLA or PHA, which dampens investor confidence. | Precursors for Carbon Fiber:There is mounting research and development interest in using lignin as a low-cost, renewable precursor to manufacture lightweight carbon fibers, primarily targeted at the automotive and aerospace industries. |
Product Type Insights
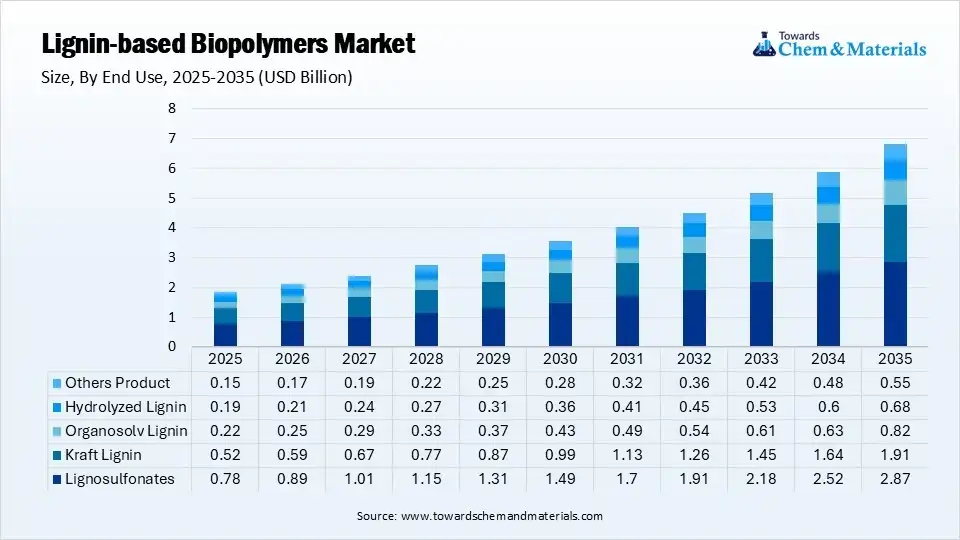
The lignosulfonates segment dominated the market with 42% share in 2025, driven by green chemistry mandates. Rapid growth stems from their exceptional water solubility, cost-effectiveness, and superior dispersing capabilities as a renewable replacement for fossil-based chemicals. They are heavily utilized as plasticizers, water reducers in concrete admixtures, soil conditioners in agriculture, and pellet binders in animal feed. Rapid urbanization and massive infrastructure investments in countries like India and China are driving high demand for concrete admixtures and agricultural binders.
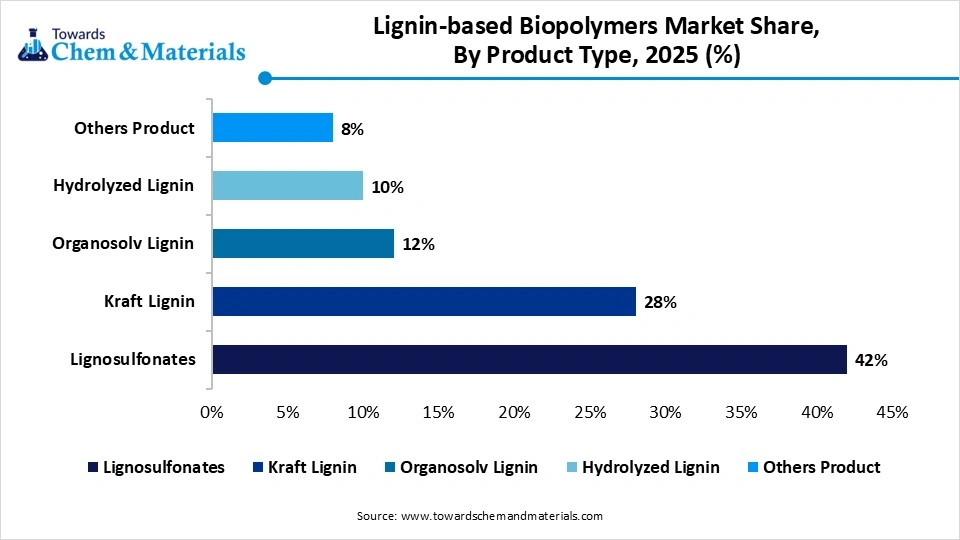
The organosolv lignin segment held 12% market share in 2025 and is expected to have the fastest growth with a CAGR of 11.2% in the forecast period, due to its high purity, sulfur-free composition, and low ash content, making it an ideal precursor for advanced green chemicals and sustainable materials. It is increasingly utilized to manufacture high-performance carbon fibers, activated carbon, vanillin, and phenolic resins. As companies face stricter environmental regulations and ESG metrics, organosolv lignin provides excellent thermal stability and acts as an eco-friendly plastic substitute to reduce greenhouse gas emissions.
Lignin-based Biopolymers Market Share, By Product Type, 2025 (%)
| By Product Type | Revenue Share, 2025 (%) |
| Lignosulfonates | 42% |
| Kraft Lignin | 28% |
| Organosolv Lignin | 12% |
| Hydrolyzed Lignin | 10% |
| Others Product | 8% |
The construction segment dominated the market with 38% share in 2025, driven by tightening green building standards and the need to replace petroleum-based materials. Innovations in fractionation technologies are allowing lignin to serve as a partial bitumen replacement in bio-based asphalt, lowering carbon emissions, and acting as a durable polymer in sewage and drainage piping networks. Striving for green certifications such as LEED, BREEAM, or the EU's climate-neutral building initiatives by 2050 is pushing contractors to adopt low-carbon materials.
 The packaging segment held 18% market share in 2025 and is expected to have the fastest growth with a CAGR of 10.8% in the forecast period, due to tightening single-use plastic regulations and surging demand for eco-friendly, circular-economy materials. Lignin acts as a green reinforcement and barrier, lowering the carbon footprint of food and consumer packaging. Advancements in extraction technologies allow for highly purified lignin, making it an excellent replacement for fossil-derived phenols in packaging resins, coatings, and biodegradable films.
How did Europe dominate the Lignin-based Biopolymers Market in 2025?
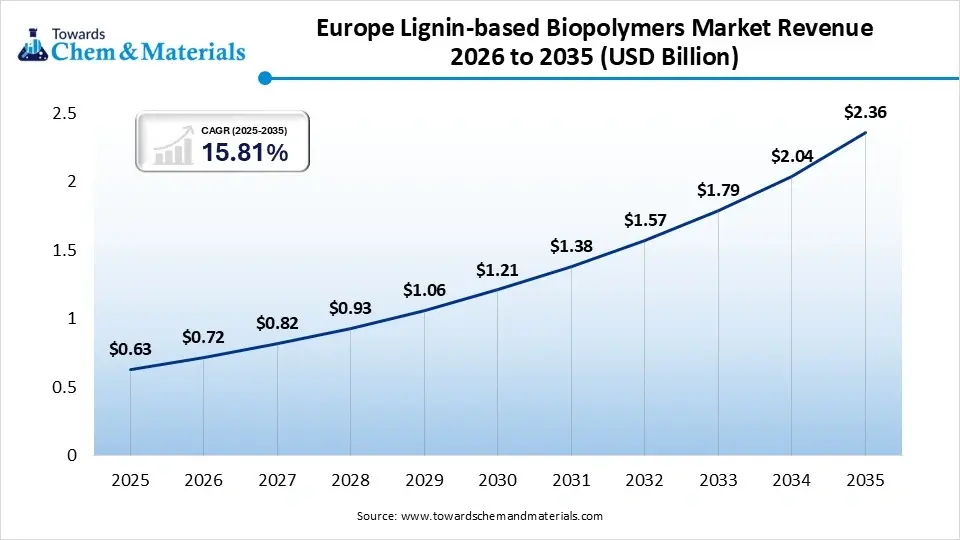
Europe lignin-based biopolymers market size was estimated at USD 0.63 billion in 2025 and is projected to reach USD 2.36 billion by 2035, growing at a CAGR of 15.81% from 2026 to 2035.Europe dominated the market with a share of 34% in 2025. This dominance stems from strict carbon policies, integrated pulp infrastructure, and rapid circular-economy adoption. The European Green Deal mandates full climate neutrality by 2050. Regulations restricting chrome in drilling, single-use plastic bans, and green public procurement mandates forced industries to replace fossil-based inputs with traceable, renewable alternatives like lignin. The EU's packaging legislation strictly accelerated recyclability and compostability targets, directly boosting bio-based material adoption.
 Germany
Italy
France
Asia Pacific Lignin-based Biopolymers Market Growth Factor
The Asia Pacific lignin-based biopolymers market size was estimated at USD 0.54 billion in 2025 and is projected to reach USD 2.01 billion by 2035, growing at a CAGR of 14.05% from 2026 to 2035.Asia Pacific held the market share of 29% in 2025 and is expected to have the fastest growth with a CAGR of 10.20% in the forecast period. Growth is driven by rapid urbanization, massive concrete demand, intensive agriculture, and strict government regulations against agro-industrial pollution. Surging infrastructure projects in China, India, and Southeast Asia heavily boost the demand for lignin-derived dispersants used in concrete admixtures. Governments are investing in bio-based industrial parks & mandating lignin valorization to decrease pollution.
India
China
Japan
North America Lignin-based Biopolymers Market Growth Factor
The North America lignin-based biopolymers market size was estimated at USD 0.48 billion in 2025 and is projected to reach USD 1.81 billion by 2035, growing at a CAGR of 14.19% from 2026 to 2035.North America held the market share of 26% in 2025, is primarily driven by strict ESG mandates to replace fossil-based chemicals, the U.S. infrastructure push, and mature pulp extraction technologies. Driven by ESG regulations and carbon-efficiency goals, biopolymers are replacing traditional fossil-derived phenols in resins, adhesives, and binders. Rapid growth in eco-friendly, bio-based packaging solutions is driving the demand for the biomaterial. The highly mature pulp and paper industry in the U.S. and Canada provides accessible Kraft Lignin and Lignosulfonates extraction pipelines.
U.S.
Canada
Latin America Lignin-based Biopolymers Market Growth Factor
The Latin America lignin-based biopolymers market size was estimated at USD 0.11 billion in 2025 and is projected to reach USD 0.44 billion by 2035, growing at a CAGR of 14.87% from 2026 to 2035.Latin America held the market share of 6% in 2025. It is driven primarily by the rising demand for sustainable packaging, rapid urbanization boosting construction, and a strong agricultural sector prioritizing eco-friendly inputs and soil conditioners. Lignin is broadly used in the region as a dispersant for pesticides, a soil conditioner, and an animal feed pellet binder, supported by countries like Brazil shifting toward sustainable farming. Growing infrastructure & residential expansion are enhancing the consumption of lignin-based concrete admixtures.
Brazil
Argentina
Middle East and Africa Lignin-based Biopolymers Market Growth Factor
The Middle East and Africa lignin-based biopolymers market size was estimated at USD 0.09 billion in 2025 and is projected to reach USD 0.38 billion by 2035, growing at a CAGR of 15.49% from 2026 to 2035.The Middle East and Africa held the market share of 5% in 2025, driven heavily by green building frameworks in the UAE, South Africa's forestry sector, and circular economy agendas that reduce synthetic polymer reliance. The UAE is integrating lignin-based materials into smart cities. Concrete admixtures for mega-projects dominate regional demand. Rapid urbanization in the UAE and smart city frameworks is heavily increasing demand for sustainable, carbon-neutral concrete plasticizers, adhesives, and insulation foams.
Saudi Arabia
UAE
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | Kemira Oyj | Helsinki | Finland | One of the world's leading suppliers of sludge dewatering polymers and wastewater treatment chemicals with extensive municipal and industrial customer base | Cationic & anionic polyacrylamides, coagulants, ferric salts, sludge dewatering chemicals |
| 2 | Ecolab Inc. (Nalco Water) | Saint Paul, Minnesota | USA | Global leader in water treatment chemistry and sludge management solutions through Nalco Water division | Flocculants, coagulants, sludge conditioners, wastewater treatment chemicals |
| 3 | BASF SE | Ludwigshafen, Rhineland-Palatinate | Germany | Major producer of high-performance water treatment polymers used in sludge thickening and dewatering | Zetag polymers, flocculants, coagulants, performance chemicals |
| 4 | SNF Group | Andrézieux-Bouthéon, Loire | France | World's largest manufacturer of polyacrylamide-based flocculants widely used in sludge treatment | Polyacrylamides, flocculants, coagulants, sludge conditioning polymers |
| 5 | Solenis LLC | Wilmington, Delaware | USA | Major specialty chemical company serving wastewater and sludge processing applications globally | Flocculants, coagulants, dewatering aids, sludge treatment additives |
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | Kurita Water Industries Ltd. | Tokyo | Japan | Strong presence in industrial water treatment and sludge reduction technologies across Asia and globally | Sludge conditioners, coagulants, wastewater treatment chemicals |
| 2 | Veolia Water Technologies | Paris | France | Integrated sludge treatment solutions provider combining chemicals and treatment technologies | Conditioning chemicals, sludge treatment reagents, dewatering solutions |
| 3 | Accepta Ltd. | Bradford, England | United Kingdom | Specialized supplier of wastewater and sludge treatment chemicals across municipal and industrial sectors | Flocculants, coagulants, sludge dewatering chemicals |
| 4 | Hubbard-Hall Inc. | Waterbury, Connecticut | USA | Established specialty chemical producer serving industrial wastewater and sludge treatment markets | Coagulants, flocculants, wastewater treatment formulations |
| 5 | Ovivo Inc. | Montréal, Québec | Canada | Significant player in sludge processing and wastewater treatment with integrated chemical programs | Sludge conditioning chemicals, treatment additives, dewatering solutions |
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | BWA Water Additives UK Ltd. | Manchester, England | United Kingdom | Specialist water treatment chemical company with growing wastewater and sludge treatment portfolio | Flocculants, coagulants, specialty treatment chemicals |
| 2 | Beckart Environmental Inc. | Kenosha, Wisconsin | USA | Focused wastewater treatment chemical supplier with sludge management expertise | Sludge conditioners, polymers, coagulants |
| 3 | AMCON Inc. | Yokohama, Kanagawa | Japan | Specialized sludge treatment company combining dewatering technology and treatment chemicals | Coagulants, sludge treatment reagents, dewatering solutions |
| 4 | SUEZ Water Technologies & Solutions | Trevose, Pennsylvania | USA | Strong wastewater treatment chemical portfolio and sludge processing expertise | Flocculants, coagulants, sludge conditioning chemicals |
| 5 | Aries Chemical Inc. | Beaver Falls, Pennsylvania | USA | Niche supplier focused on wastewater and biosolids treatment chemicals | Ferric salts, coagulants, sludge treatment products |
By Product Type
By End Use
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo