
Cyclohexanone Market Size, Competitive Landscape Analysis Report 2035
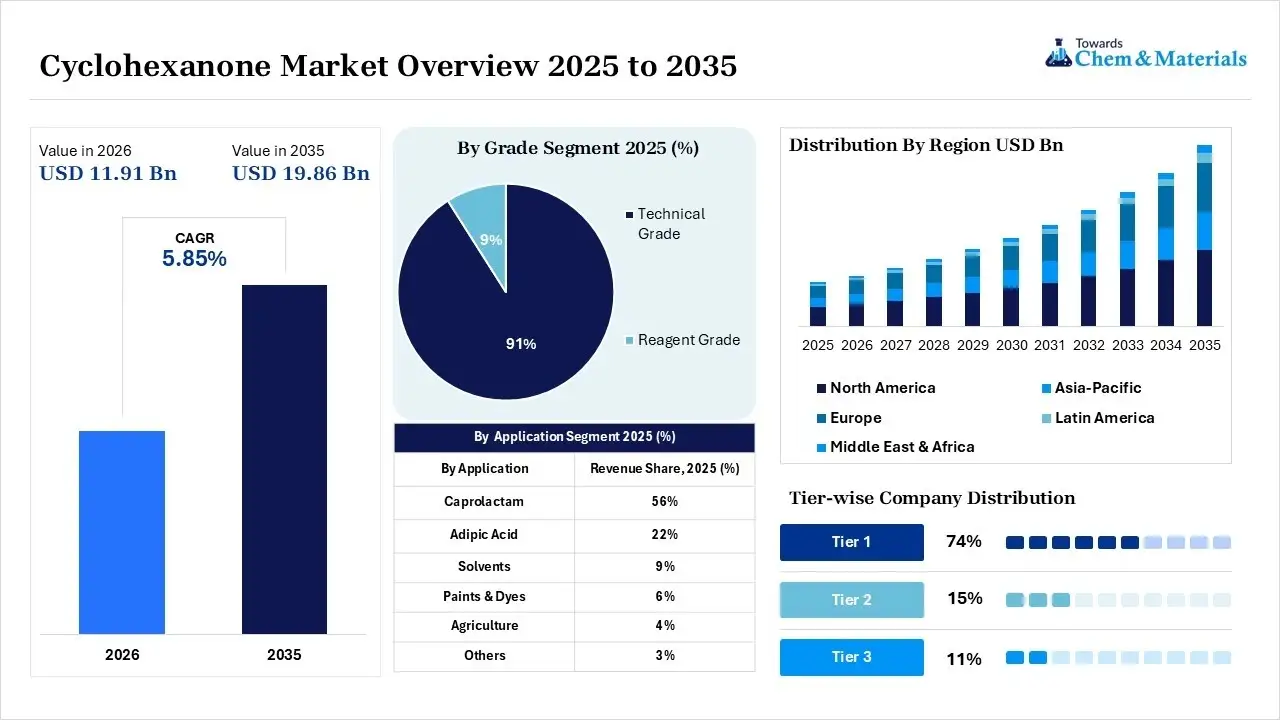
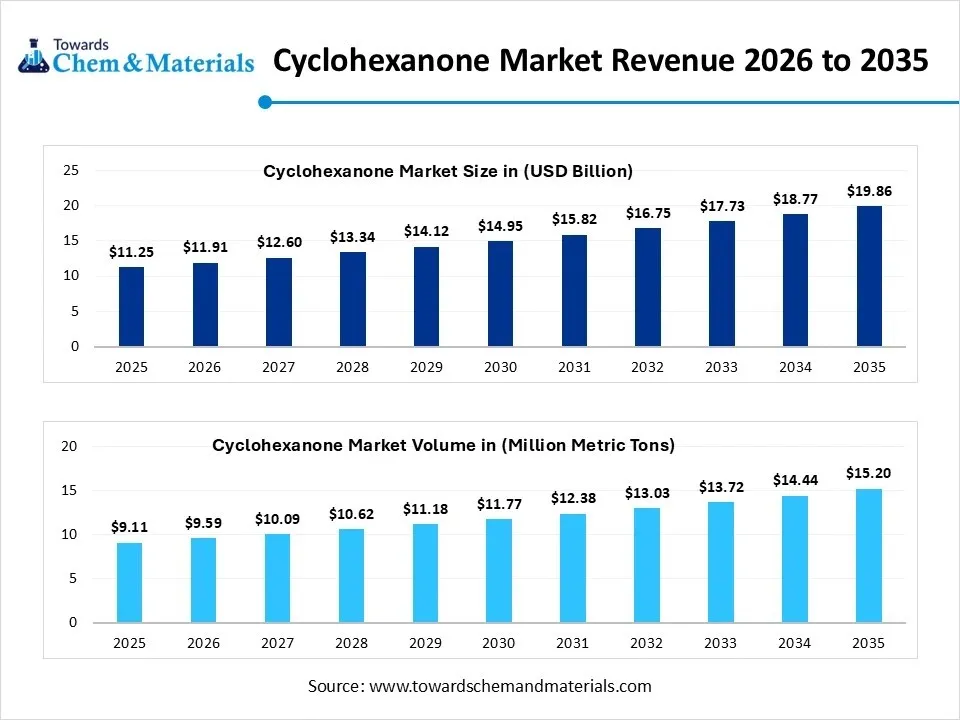
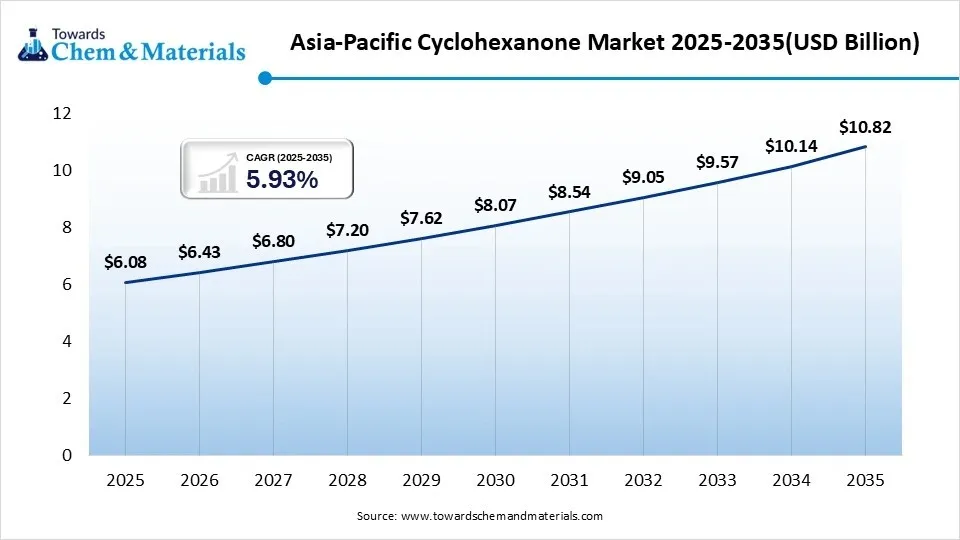
The cyclohexanone market size was valued at USD 11.25 billion in 2025, is estimated to reach USD 11.91 billion in 2026, and is projected to reach USD 19.86 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.85% over the forecast period from 2026 to 2035.Asia Pacific dominated the cyclohexanone market with the largest revenue share of 54% in 2025 and is expected to grow at the fastest CAGR of 5.93% during the forecast period. The market is steadily driven by rising demand as a key intermediate in nylon 6 production, along with expanding applications in coatings, paints, adhesives, solvents and specialty chemicals, supported by growing automotive, textile, electronics and industrial manufacturing sectors.
 Market Highlights
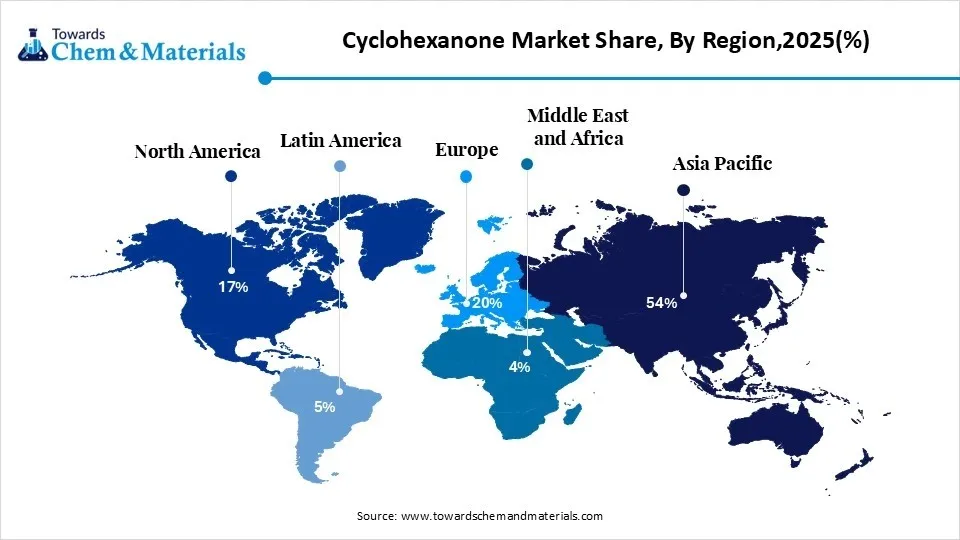
- By region, Asia Pacific dominated the market with the largest share of 54.00% in 2025. The dominance of the region can be attributed to the strong textile and automotive industries, which sustain demand. China and India continue expanding nylon and chemical manufacturing capacities. Integrated petrochemical investments accelerate regional growth.
- By region, North America held a market share of 17.00% in 2025 and was expected to grow at the fastest CAGR of 6.5% over the forecast period. The growth of the region can be credited to the mature chemical processing infrastructure, which supports stable cyclohexanone consumption. Automotive and industrial applications remain significant. Investments in specialty chemicals sustain market development.
- By application, the caprolactam segment dominated the market with the largest share of 56.00% in 2025. Nylon 6 production continues to drive the largest cyclohexanone consumption. Growing textile and engineering plastics industries sustain demand. Capacity expansions in Asia support long-term market growth.
- By application, the solvents segment held a market share of 9% in 2025 and is expected to grow at the fastest CAGR of 6.50% during the projected period. Demand from resin and specialty solvent applications remains stable. Industrial cleaning operations increase solvent consumption. Chemical processing industries support market expansion.
- By grade, the technical grade segment dominated the market with the largest share of 91.00% in 2025. Bulk industrial production of caprolactam and adipic acid requires technical-grade material. Cost efficiency supports widespread industrial adoption. Large-volume chemical manufacturing drives sustained demand.
- By grade, the reagent segment held a market share of 9.00% in 2025 and is expected to grow at the fastest CAGR of 6.70% over the forecast period. Laboratory research and pharmaceutical applications increase demand for high-purity products. Analytical testing requirements expand globally. Specialty chemical production supports premium-grade consumption.
According to Towards Chemicals and Materials Analytics and Consulting, the global cyclohexanone market volume was valued at 9.11 million metric tons in 2025 and is expected to surpass around 15.20 million metric tons by 2035, accelerating a compound annual growth rate (CAGR) of 5.95% over the forecast period from 2026 to 2035.
The cyclohexanone market is witnessing steady growth, driven by its indispensable role as a chemical intermediate in the production of caprolactam and adipic acid, the two key raw materials used to manufacture nylon 6 and nylon 6,6. As global demand for lightweight engineering plastics, synthetic fibers, automotive components, industrial textiles and consumer goods continues to rise, cyclohexanone remains a critical building block in the chemical value chain. It is also widely used as a solvent in paints, coatings, adhesives, inks, pesticides and pharmaceutical intermediates, broadening its industrial significance.
A major trend shaping the market is the increasing emphasis on operational efficiency and sustainable manufacturing. producers are investing in advanced oxidation technologies, process optimization and energy-efficient production methods to improve product quality while reducing emissions and resource consumption. Growing investments in automotive electrification, infrastructure development and textile manufacturing are supporting long-term demand for nylon, which in turn drives cyclohexanone consumption. Manufacturers are also strengthening supply chain resilience through capacity optimization and strategic investments to meet the evolving needs of downstream industries.
The market benefits from integrated production facilities where benzene is converted into cyclohexanone and subsequently processed into caprolactam or adipic acid, ensuring greater cost efficiency and supply reliability. This integrated approach is especially important as demand for engineering plastics and high-performance fibers expands across mobility, electronics and industrial applications.
- For instance, in November 2025, AdvanSix highlighted continued investments in operational excellence and supply reliability while reporting its financial results. The company emphasized disciplined production management across its Nylon Solutions and Chemical Intermediates businesses to support customer demand amid changing market conditions. (Source: www.advansix.com)
Market Trends
- Rising demand for nylon due to its expanding applications in automotive, electrical, textile and packaging industries drives growth.
- Growing usage of cyclohexanone as a solvent in paints, coatings, adhesives, and plastics drives the demand.
- Shift towards bio-based feedstocks, like research and production of bio-based cyclohexanone from renewable resources.
- Increasing environmental regulations on hazardous chemicals are pushing companies to improve production efficiency and waste management.
Market Report Scope
| Report Attributes | Details |
| Market Volume in 2025 | USD 11.91 Billion / 9.59 Million Metric Tons |
| Expected Volume by 2035 | USD 19.86 Billion/ 15.20 Million Metric Tons |
| Growth Rate from 2025 to 2035 | CAGR 5.85% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Application , By Grade, By Region |
| Key Companies Profiled | Gujarat State Fertilizers & Chemicals Limited (GSFC), Asahi Kasei Corporation, BASF, Domo Chemicals, Ostchem, Fibrant, Shreeji Chemicals., JIGCHEM UNIVERSAL, ARIHANT SOLVENTS AND CHEMICALS, Qingdao Hisea Chem Co., Ltd., LUXI GROUP, Chang Chun Group, UBE Corporation |
Supply Chain Analysis
Feedstock Procurement and Basic Chemical Production
- The cyclohexanone supply chain begins with the procurement of benzene and hydrogen, derived from crude oil refining and petrochemical operations. Benzene is hydrogenated to produce cyclohexane, which is subsequently oxidized or dehydrogenated to manufacture cyclohexanone.
- AdvanSix: it is a fully integrated producer of benzene derivatives, cyclohexanone, phenol, acetone and caprolactam. Its integrated manufacturing network enables efficient feedstock utilization and reliable supply for the downstream nylon and chemical industries.
- Other Key Players: DOMO Chemicals, UBE Corporation, Asahi Kasei Corporation.
Chemical Synthesis
- Cyclohexane undergoes catalytic oxidation or phenol hydrogenation to produce cyclohexanone. Manufacturers focus on improving catalyst efficiency, reducing energy consumption and optimizing process yields to enhance production economics.
- DOMO Chemicals: the company manufactures cyclohexanone as part of its integrated polyamide value chain, supplying high-quality intermediates for engineering plastics, textiles, automotive and industrial applications.
- Other Key Players: AdvanSix, BASF SE, UBE Corporation
Purification, Quality Control and Storage
- Cyclohexanone undergoes purification through distillation and quality testing to ensure compliance with industrial specifications for purity, moisture content and chemical composition. The product is then stored in dedicated chemical storage tanks under controlled conditions.
- BASF SE: The company maintains rigorous quality assurance systems across its chemical intermediates portfolio, ensuring cyclohexanone meets the performance and purity requirements.
- Other Key Players: AdvanSix, DOMO Chemicals
Distribution and Industrial Supply
- It is distributed through bulk tankers, ISO containers, railcars and chemical logistics networks to nylon manufacturers and specialty chemical companies.
- Brenntag: It is one of the world’s largest chemical distributors, supplying cyclohexanone and other chemical intermediates through its global logistics network.
- Other key Players: Univar Solutions, HELM AG
Cyclohexanone Market Opportunity
What is the Significant Opportunity for the Growth of the Cyclohexanone Market?
One significant opportunity in the cyclohexanone market lies in the development and commercialization of bio-based cyclohexanone as a sustainable alternative to the conventional petrochemical-derived version. With increasing global emphasis on reducing carbon emissions and environmental impact, industries are seeking greener production methods. Bio-based cyclohexanone, derived from renewable feedstocks such as biomass or plant-based raw materials, presents a compelling solution that aligns with environmental regulations and consumer preferences for sustainable products. This opportunity not only supports circular economy initiatives but also allows companies to differentiate themselves in a competitive market by offering eco-friendly chemical solutions, especially in applications like green nylon and sustainable coatings.
Cyclohexanone Market Challenge
The Factor Responsible for Hindering the Growth of the Market is Raw Material Prices
One major challenge in the market is the volatility of raw material prices, particularly for cyclohexane and phenol, which are key feedstocks in its production. Fluctuations in crude oil prices, geopolitical tensions, and supply chain disruptions can significantly impact the availability and cost of these raw materials, leading to unstable production costs and profit margins. This unpredictability poses a risk for manufacturers in planning and pricing strategies, especially in highly competitive markets. Additionally, dependence on non-renewable feedstocks raises concerns about long-term sustainability, prompting the need for investment in alternative production technologies, which can be capital-intensive and slow to implement.
Regional Insights
How did the Asia Pacific Dominate the Cyclohexanone Market in 2025?
The Asia Pacific cyclohexanone market size was estimated at USD xx billion in 2025 and is projected to reach USD xx billion by 2035, growing at a CAGR of xx% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 54.00% in 2025. The dominance of the region can be attributed to the strong textile and automotive industries, which sustain demand. China and India continue expanding nylon and chemical manufacturing capacities. Integrated petrochemical investments accelerate regional growth. Rapid industrialization, infrastructure development and increasing investments in engineering plastics and synthetic fibers continue to strengthen market demand.
China
- The market is supported by its extensive nylon, chemical and textile industries.
- Rising demand for engineering plastics in electric vehicles, consumer electronics and industrial equipment is driving higher consumption of caprolactam and adipic acid.
- The country’s continued investments in petrochemical integration and advanced manufacturing are also improving domestic cyclohexanone production capacity.
India
- The country is witnessing increasing investments in textile manufacturing, automotive production and specialty chemicals.
- Government initiatives, along with expanding domestic demand for engineering plastics and synthetic fibers are boosting cyclohexanone consumption.
- Growth in paints, coatings, pharmaceuticals, and industrial solvents is a strong market expansion.
North America held a market share of 17.00% in 2025 and was expected to grow at the fastest CAGR of 6.5% over the forecast period. The growth of the region can be credited to mature chemical processing infrastructure, which supports stable cyclohexanone consumption. Automotive and industrial applications remain significant. Investments in specialty chemicals sustain market development. The region benefits from integrated petrochemical manufacturing, technological advancements, and investments in sustainable chemical production.
United States
- The country has a well-established chemical manufacturing industry and integrated production facilities.
- Rising demand from automotive, aerospace, electrical equipment, and industrial applications is supporting increased consumption of nylon intermediates.
- Investments in modernizing chemical production facilities and improving operational efficiency are strengthening the domestic market.
Canada
- The country is witnessing steady growth spurred by expanding industrial manufacturing, automotive production and construction activities.
- Increasing demand for higher-performance plastics, industrial coatings and specialty chemicals is contributing to cyclohexanone consumption.
- The country’s strong trade relationship with the U.S. supports a stable supply across downstream manufacturing industries.
Europe held a market share of 20.00% in 2025. The growth of the region can be credited to established chemical manufacturing and engineering plastics industries, which maintain steady demand. Sustainability initiatives encourage process modernization. High-value specialty chemicals support market stability. Manufacturers are increasingly focusing on process efficiency, emission reduction and sustainable chemical production to meet evolving requirements.
Germany
- The country has a strong automobile, engineering plastics and chemical industries.
- Demand for cyclohexanone is spurred by increasing demand for lightweight automotive components, industrial machinery and advanced polymer materials.
- The country’s emphasis on sustainable manufacturing is encouraging investments in more efficient chemical production technologies.
France
- The market is driven by the automobile, aerospace, exile and speciality chemicals industries.
- Increasing adoption of engineering plastics in transportation and industrial manufacturing, combined with confined investments in sustainable industrial production, has spurred cyclohexanone consumption.
Latin America held a market share of 5.00% in 2025. The growth of the region can be credited to expanding industrial manufacturing and construction activities, which increase demand. Regional nylon processing supports market growth. Chemical industry investments improve production capacity. Increasing investments in industrial modernization are creating opportunities for nylon-based products and related chemical intermediates.
Brazil
- The country has a diversified industrial base, a large automotive industry and an expanding chemical manufacturing sector.
- Rising demand for engineering plastics, synthetic fibers, paints and coatings is driving the cyclohexanone market.
Continued investments in industrial production and infrastructure are expected to sustain market growth.
Chile
- The demand has surged in mining, industrial maintenance and infrastructure development.
- Cyclohexanone-based solvents and nylon materials are increasingly used in industrial equipment, protective coatings and chemical processing applications.
- Growth in manufacturing and construction activities is expected to gradually increase market demand.
The Middle East and Africa held a market share of 4.00% in 2025. The growth of the region can be credited to petrochemical diversification projects that support downstream chemical production. Industrial development supports increasing consumption. Investments in manufacturing infrastructure create new opportunities. The region’s expanding petrochemical infrastructure supports future production and supply capabilities.
Saudi Arabia
- The country has a strong petrochemical industry and ongoing industrial diversification under Vision 2030.
- Investments in downstream chemical manufacturing, automotive components, infrastructure, and industrial materials are increasing demand.
- The country’s integrated refining and petrochemical complexes provide a strong foundation for future market growth.
South Africa
- The market is driven by increasing demand from automotive manufacturing, mining, paints and coatings, and industrial chemical sectors.
- Growing investments in infrastructure development and industrial modernization are supporting the use of nylon-based materials and speciality chemicals.
Segmental Insights
Application Insights
The caprolactam segment dominated the cyclohexanone market share 56% in 2025. Caprolactam is the largest and most important segment within the cyclohexanone market, as it is the primary raw material used in the production of nylon-6 fibers and resins. Cyclohexanone is a key intermediate in the manufacture of caprolactam, which is highly demanded in industries such as textiles, automotive, packaging, and engineering plastics due to its strength, durability, and versatility. The increasing demand for nylon-based products in apparel, carpets, and industrial applications drives the growth of this segment. Additionally, innovations in caprolactam production aimed at improving efficiency and reducing environmental impact further support its market expansion. Because nylon-6 is widely used in high-performance and lightweight materials, this segment is a major revenue generator for the market.
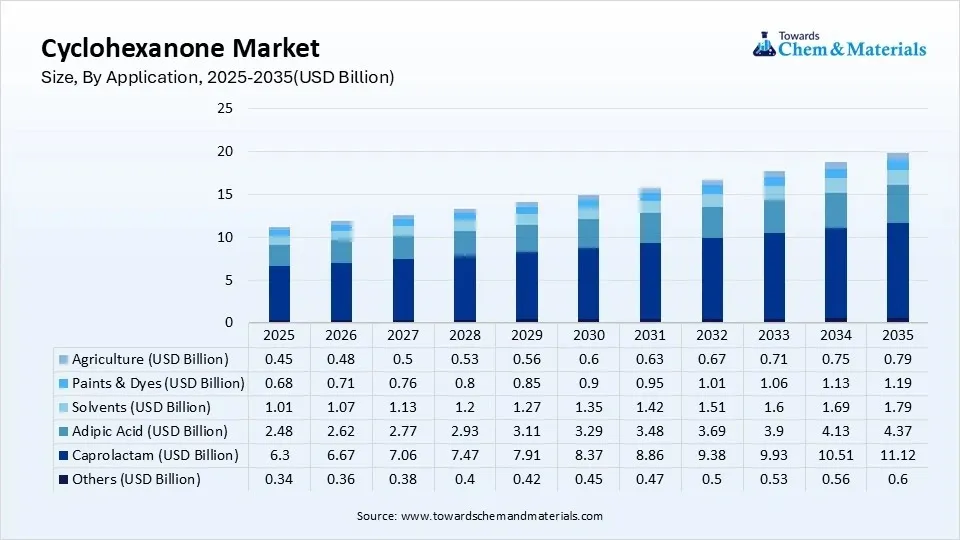
The solvents segment expects significant growth in the cyclohexanone market during the forecast period. The solvents segment represents an important application area for cyclohexanone, where it is valued for its excellent solvency properties in various industrial processes. Cyclohexanone is widely used as a solvent in paints, coatings, adhesives, and sealants due to its ability to dissolve a broad range of resins and polymers, ensuring smooth application and quick drying times. This segment benefits from growing demand in the construction, automotive, and electronics industries, where high-quality coatings and adhesives are essential for product performance and durability. Moreover, cyclohexanone’s relatively low toxicity compared to some other solvents makes it a preferred choice for safer manufacturing processes. Increasing environmental regulations and a push for greener solvents are also influencing the development of more sustainable solvent formulations using cyclohexanone.
Cyclohexanone Market Share, By Application,2025(%)
| By Application | Revenue Share, 2025 (%) |
| Caprolactam | 56% |
| Adipic Acid | 22% |
| Solvents | 9% |
| Paints & Dyes | 6% |
| Agriculture | 4% |
| Others | 3% |
Grade Insights
The technical grade segment dominated the cyclohexanone market share 91% in 2025. The technical grade segment of cyclohexanone refers to the grade used primarily in industrial applications where ultra-high purity is not required. This grade is commonly utilized as a solvent or intermediate in the production of various chemicals, including agricultural chemicals, pharmaceuticals, and specialty chemicals. Its cost-effectiveness and adequate purity make it suitable for use in manufacturing processes where small impurities do not affect the final product’s performance. The demand for technical grade cyclohexanone is driven by industries looking for economical and efficient solvents or intermediates, especially in sectors such as coatings, adhesives, and rubber processing. This segment plays a crucial role in supporting broad industrial applications beyond the nylon production chain.
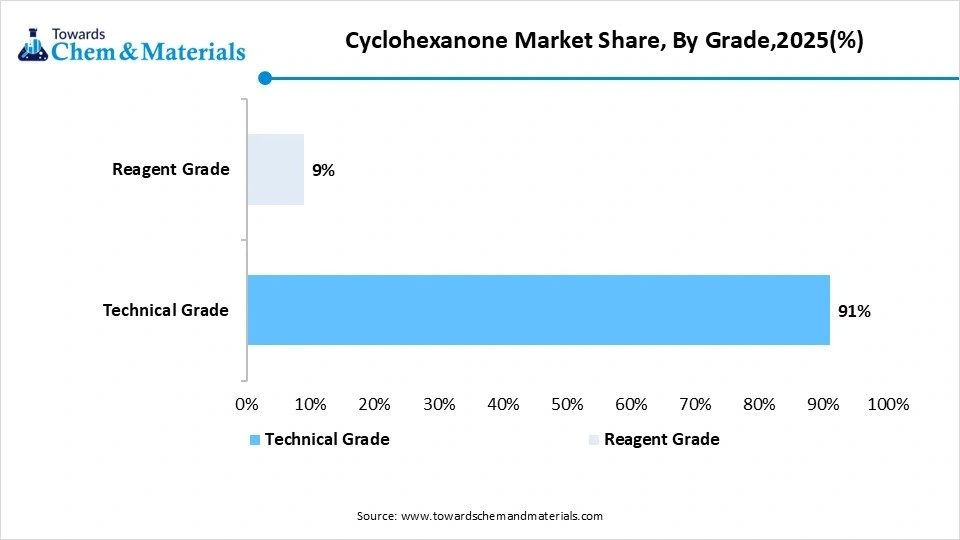
The reagent grade segment expects significant growth in the cyclohexanone market during the forecast period. The reagent grade cyclohexanone is characterized by its high purity and is primarily used in laboratory settings, pharmaceutical manufacturing, and specialized chemical syntheses where precise chemical reactions are essential. This grade ensures minimal impurities, which is critical for research and development, quality control, and the production of fine chemicals and pharmaceuticals. Its demand is driven by the need for consistent and reliable chemical performance in sensitive applications. Additionally, reagent-grade cyclohexanone is often used in the synthesis of high-value compounds and analytical procedures, making it a vital segment despite representing a smaller volume compared to industrial grades.
Cyclohexanone Market Share, By Application,2025(%)
| By Grade | Revenue Share, 2025 (%) |
| Technical Grade | 91% |
| Reagent Grade | 9% |
Recent Developments
- In October 2025, DOMO Chemicals continued strengthening its integrated polyamide value chain through sustainability initiatives and investments aimed at improving production efficiency and reducing the environmental footprint of nylon intermediates.(Source: www.domochemicals.com)
Top Companies List
- Gujarat State Fertilizers & Chemicals Limited (GSFC)
- Asahi Kasei Corporation
- BASF
- Domo Chemicals
- Ostchem
- Fibrant
- Shreeji Chemicals.
- JIGCHEM UNIVERSAL
- ARIHANT SOLVENTS AND CHEMICALS
- Qingdao Hisea Chem Co., Ltd.
- LUXI GROUP
- Chang Chun Group
- UBE Corporation
Segments Covered in the Report
By Application
- Caprolactam
- Nylon 6 Fiber Production
- Engineering Plastics
- Industrial Yarns
- Adipic Acid
- Nylon 6,6 Production
- Polyurethane Intermediates
- Plasticizers
- Solvents
- Paint Solvents
- Resin Solvents
- Cleaning Agents
- Paints & Dyes
- Industrial Coatings
- Decorative Paints
- Textile Dyes
- Agriculture
- Agrochemical Formulations
- Crop Protection Chemicals
- Others
- Pharmaceuticals
- Rubber Chemicals
- Adhesives
- Laboratory Chemicals
By Grade
- Technical Grade
- Industrial Grade
- Commercial Grade
- Reagent Grade
- Analytical Grade
- High Purity Grade
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.