
What is the Biofuel Enzymes Market Size and Share?
The global biofuel enzymes market size was valued at USD 786 million in 2025 and is projected to grow from USD 843.38 million in 2026 to USD 1,590.08 million by 2035, exhibiting a CAGR of 7.30% during the forecast period. Growth is anchored by blending mandates, ethanol capacity additions in Asia Pacific, and rising demand for yield-enhancing and carbon-intensity-reducing enzymes. North America holds about 39% of revenue, while Asia Pacific is the fastest-growing region.
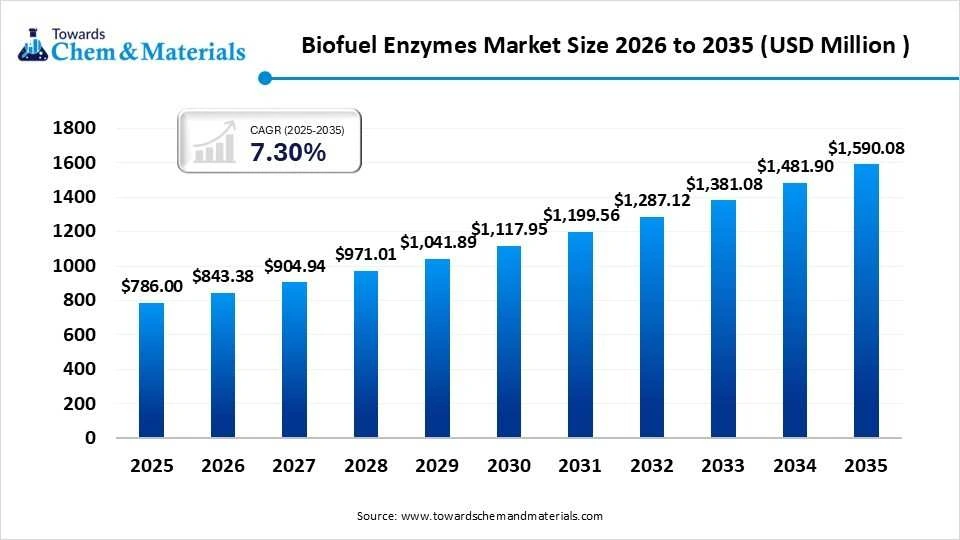
The report covers market size, segmentation, pricing, demand-supply, value chain, technology, regulation, competitive benchmarking, M&A, and profiles of 20 leading companies, with base, upside, and downside scenarios through 2035.
Starch-Ethanol Dosing Intensity and Cellulosic Optionality Define a Concentrated, Mandate-Anchored Enzyme Market
An incremental opportunity of roughly USD 1,590.08 million. Demand tracks fuel-ethanol output of more than 100 billion liters a year, which is underpinned by blending mandates in the Americas and Asia Pacific. North America is expected to hold the largest share, about 39% of global revenue, and Asia Pacific is the fastest-growing region at an estimated 7-8% CAGR. Amylases (alpha-amylase, glucoamylase and their blends) form the largest product pool at roughly 44% of revenue. Cellulases and hemicellulases are the fastest-growing segment.
Key Takeaways
- North America holds the largest share, about 39% of global revenue, followed by Asia Pacific at about 25%,
- Europe at about 17%, and Latin America at about 15%. Asia Pacific is the fastest-growing region.
- Blending mandates in the Americas and Asia anchor demand, making policy the largest swing factor.
- Enzyme cost is roughly USD 0.02-0.04 per gallon in starch ethanol, against USD 0.10 to above USD 0.50 per gallon for cellulosic cocktails.
- India and Southeast Asia depend on imports and tolling, while North America and Europe are supplied domestically, driving localization in India and Brazil.
- Key risks include vehicle electrification, feedstock price volatility, slow cellulosic commercialization, and policy uncertainty.
- White spaces include biogas and anaerobic digestion, sustainable aviation fuel pathways, non-grain feedstocks, co-product enzymes, and localized production in emerging markets.
The market is mature in corn and sugarcane ethanol and early-stage in cellulosic, biodiesel, and biogas applications. Supply is highly concentrated: the top two suppliers are estimated to hold more than 60% of revenue.
Key Coverage
- 2020-2025 historical revenue and 2026-2035 forecasts
- Volume in tons of enzyme product and dosing per ton of feedstock
- Revenue pools by enzyme class, feedstock, fuel type and region
- Incremental revenue by segment
- Concentration and maturity assessment by application
Segmentation Analysis: Amylases Anchor Revenue, While Cellulases and Hemicellulases Lead Growth
- By enzyme type, amylases segment dominated the market with the largest share of 44% in 2025 and is expected to grow at a CAGR of 5% during the forecast period.
- By enzyme type, the cellulases and hemicellulases segment held a 25% market share in 2025 and is expected to grow at the fastest CAGR of 8.5% over the forecast period.
- By application, the starch-based ethanol segment dominated the market with the largest share of 60% in 2025 and is expected to grow at a CAGR of 4.8% during the forecast period.
- By application, the cellulosic and advanced ethanol segment held a 13% market share in 2025 and is expected to grow at the fastest CAGR of 9.5% over the forecast period.
- By feedstock, the corn segment dominated the market with the largest share of 51% in 2025 and is expected to grow at a CAGR of 5.2% during the forecast period.
- By feedstock, the lignocellulosic residues segment held a 15% market share in 2025 and is expected to grow at the fastest CAGR of 9% over the forecast period.
The full report quantifies each dimension by revenue, volume, share, and growth contribution.
Market Dynamics: Yield Economics and Policy Support Offset Electrification and Feedstock Volatility
Drivers
The market is growing due to blending mandates across more than 60 countries and the increasing focus on improving biofuel production efficiency. Although enzymes account for a small share of operating costs, they can improve production yields by 1–3%. Falling cellulase costs and the growing value of corn-oil recovery and other co-products are further supporting market growth.
Restraints
The market faces challenges from the gradual decline in long-term gasoline demand due to vehicle electrification, fluctuating feedstock prices, and the slow commercialization of cellulosic biofuels. Uncertainty around government policies and blending mandates also makes long-term investment decisions more difficult for producers.
Opportunities
Emerging opportunities in sustainable aviation fuel (SAF), biogas production from agricultural waste, and the integration of enzyme-related traits into crops are creating new growth avenues. Enzyme costs in cellulosic biofuel pathways have reportedly declined by 60–80% over the past 15 years, shifting the industry's main challenges toward feedstock pretreatment, high capital investment, and project financing.
Challenges
The global biofuel enzymes market faces challenges from high capital investment, variable feedstock quality, and the technical complexity of cellulosic biofuel production. Despite falling enzyme costs, pretreatment expenses, limited commercial-scale adoption, and policy uncertainty continue to affect production economics and market growth.
Why Do Biofuel Enzyme Prices Hold Their Premium When Ethanol Is a Commodity, and Where Is Pricing Power Most Likely to Persist?
Pricing in biofuel enzymes is set by cost per gallon or liter of ethanol produced, not by price per kilogram of product. Enzyme cost in starch ethanol is estimated at roughly USD 0.02-0.04 per gallon, while cellulosic cocktails have historically ranged from about USD 0.10 to above USD 0.50 per gallon, depending on loading and pretreatment. At product level, standard liquid amylases are priced at roughly USD 3-12 per kg, against USD 8-25 per kg for advanced cellulase and hemicellulase formulations. Leading producers earn estimated gross margins of 45-60% in standard grades, and specialty cocktails command premiums of 20-40% over commodity grades. Fermentation substrate costs are passed through only partially, with a lag of two to four quarters.
Our analysis indicates that the premium is sustained by how value is measured rather than by what the product costs. Because enzymes are a small share of plant operating cost but can move ethanol yield by 1-3%, buyers evaluate them on yield and cost per gallon, not on price per kg. Price differences are explained by enzyme activity per unit of product, thermal and pH tolerance, dosing efficiency, co-product benefits such as higher corn-oil recovery, and contract structure, notably multi-year and performance-linked agreements. Our assessment is that the wide per-kg spread between standard and advanced products reflects performance and loading economics more than manufacturing cost.
In our view, the most significant implication is that pricing power is segmented. Margins in standard amylases are likely to face steady pressure as regional producers gain share in cost-sensitive markets, while performance-linked contracts and specialty cocktails offer the most defensible premiums. The partial pass-through lag of two to four quarters means producers carry short-term margin risk when substrate costs rise. We believe cellulosic pricing is the largest swing variable, since falling cost per gallon expands the addressable market but compresses unit pricing. From our assessment, this creates an opportunity for suppliers that can bundle yield, co-product recovery and carbon-intensity benefits into a single value proposition rather than compete on price per kg.
The full report quantifies price per kg and cost per gallon by enzyme type and application, regional price spreads, premium versus commodity pricing, margin benchmarks by grade, contract structures and cost pass-through, with a pricing outlook through 2035 under base, upside and downside scenarios.
The same intelligence can also be delivered as a structured pricing database tracking price per kg and cost per gallon by enzyme type, application, feedstock, region and year. It would allow filtering by grade (standard versus specialty), contract type and region, and benchmarking of price premiums and margin bands across segments. This complements the strategic report by letting teams model pricing scenarios and test product positioning against segment-level benchmarks.
Key Coverage
- Price per kg and cost per gallon by enzyme and application
- Regional price spreads
- Premium versus commodity pricing
- Margin benchmarks
- Contract structures and pass-through
- Price outlook through 2035
How are Regional Capacity Expansions Changing Supply and Demand in the Global Biofuel Enzymes Market?
Industrial enzyme production requires less capital than many traditional chemical manufacturing operations, but success still depends on having the right fermentation facilities, enzyme strains, and regulatory approvals. Globally, production facilities are estimated to operate at around 75–85% of their capacity, with leading manufacturers generally maintaining higher utilization rates. In India and Southeast Asia, local production is not sufficient to meet demand, making imports and contract manufacturing important sources of supply.
North America and Europe, on the other hand, have stronger domestic supply networks supported by established manufacturers. Meanwhile, Chinese producers are expanding their exports of mid-grade amylases, increasing competition in international markets. Setting up new fermentation capacity typically takes 18–30 months, meaning supply cannot adjust immediately when demand rises. The market analysis examines regional capacity, utilization, supply-demand gaps, and potential imbalances through 2035.
Where is Value Concentrated Across the Biofuel Enzymes Value Chain, and Which Capabilities Protect Supplier Margins?
The global biofuel enzymes value chain extends from fermentation feedstocks, including glucose and nitrogen sources, to strain development, fermentation, downstream processing, formulation, technical support, and distribution to ethanol producers. Raw materials and fermentation inputs account for an estimated 25–35% of manufacturing costs, while utilities and downstream processing contribute significantly to the remaining cost base. Profitability is concentrated in strain engineering and application support, which are estimated to capture 50–60% of industry profit pools.
Our analysis indicates that competitive advantage in biofuel enzymes depends not only on production efficiency but also on proprietary strain technology and the ability to improve enzyme performance under specific plant conditions. These capabilities help suppliers differentiate their products and build stronger customer relationships. In our view, manufacturers that combine effective strain development with application-level technical support are better positioned to protect margins than suppliers competing primarily on price.
The full report further examines cost distribution, margin concentration, and supply-chain bottlenecks across key stages of the value chain. This intelligence can also be structured into a company- and region-level dataset covering feedstock costs, manufacturing-cost shares, production capabilities, distribution models, technical-service availability, and estimated profit-pool allocation. These fields enable users to benchmark value-chain economics, compare regional supply structures, and identify opportunities to improve margins and strengthen market access.
The report quantifies cost contribution, margin pools, and logistics costs by stage.
Trade & Import-Export Analysis: A Few Production Hubs Supply Globally, While Importing Markets Localize
Trade is concentrated in a small number of exporting countries in Europe, North America, and China. Importing markets include India, Southeast Asia, Latin America, and parts of Africa. Tariffs, registration requirements, and biotechnology regulation shape sourcing. Localization of formulation and fermentation is a growing theme, particularly in India and Brazil. The full report quantifies trade corridors, dependency ratios and import-substitution opportunities.
Technology & Innovation: Thermostable, Multi-Enzyme and Protein-Engineered Platforms Expand Yield Frontiers
Mature technologies include conventional liquefaction and saccharification enzymes and standard cellulase cocktails. Emerging technologies include raw-starch hydrolysis (reducing steam cost), corn-oil recovery enzymes, protease systems for protein co-products, AI-guided protein engineering, and enzyme-expressing crop traits. Disruptive options include direct microbial conversion and consolidated bioprocessing. Industry estimates suggest that patent filings in biomass-degrading enzymes have grown at a high-single-digit annual rate over the past decade. The report profiles technology maturity, adoption rates, patent trends, and commercial deployments.
Regulatory & Sustainability Analysis: Carbon-Intensity Rules Shift Value Toward Efficiency-Enhancing Enzymes
The market is shaped by:
- Renewable-fuel volume mandates and blending targets in the Americas, India and Europe
- Revised EU renewable energy rules
- Low-carbon fuel standards and carbon-intensity-linked incentives
- Aviation-fuel mandates
Because enzymes lower energy consumption and raise yield, they directly reduce carbon-intensity scores, which can be worth several cents per gallon in credits. Enzyme manufacturers also face biosafety and genetically-modified-organism production regulation. The report quantifies mandate-linked demand, carbon-intensity benefits, and compliance impacts.
Customer & Application Analysis: Large Ethanol Producers Drive Qualification-Heavy, Performance-Linked Purchasing
Customers fall into large integrated ethanol producers, mid-sized independent plants, sugar-ethanol mills, biodiesel producers, and biogas operators. The top 10 ethanol producers account for a large share of global demand, giving buyers considerable bargaining power. Purchasing criteria are yield improvement, dosing efficiency, plant trials, and technical service. Switching costs are moderate, since trials take weeks, but performance guarantees and integrated yeast-enzyme programs raise stickiness. Unmet needs include non-grain feedstock performance, lower-cost cellulases and high-solids processing.
How is Market Concentration Shaping Competition and Growth Opportunities in the Global Biofuel Enzymes Market?
The global biofuel enzymes market is highly concentrated, with Novonesis estimated to account for approximately 45–50% of global revenue and IFF around 15–20%. The top five players collectively represent more than 80% of the market, leaving the remaining share to regional manufacturers and specialized suppliers. Leading players compete through proprietary enzyme strains, global technical support, integrated yeast-enzyme solutions, and sustainability credentials, while smaller competitors focus on pricing, local market access, and enzymes tailored to regional feedstocks.
Our analysis indicates that the market's concentration gives established suppliers an advantage in technology development, customer relationships, and large-scale service delivery. Competition is relatively intense in standard amylases, where product differentiation can be limited, but more moderate in cellulosic enzyme systems, where technical complexity creates greater opportunities for specialization. The formation of Novonesis in 2024 further strengthened the role of scale and integrated capabilities in the competitive landscape.
In our view, smaller suppliers are more likely to gain ground by addressing specific feedstock requirements, improving enzyme performance, and offering cost-effective solutions in underserved regions rather than competing directly with market leaders across all product categories. For established players, continued investment in strain engineering, application support, and integrated solutions will be important for protecting market share and sustaining margins.
The full report provides deeper competitive benchmarking across market share, product portfolios, technology capabilities, regional presence, customer segments, and strategic developments. The same intelligence can also be provided as a structured company-level competitive dataset, tracking estimated revenue share by year, product category, geography, enzyme technology, application focus, and strategic partnerships. This enables users to compare leading suppliers, monitor changes in market concentration, and identify potential opportunities for differentiation or expansion.
Tentative Leading Company Universe
| Sr.No | Company | HQ | Market Position | Core Strength | Major Segments |
| 1 | Novonesis | Denmark | Global leader | Strain IP, scale | Starch and cellulosic ethanol, biogas |
| 2 | IFF | U.S. | Global leader | Genencor heritage | Fuel ethanol, cellulosic |
| 3 | AB Enzymes | Germany | Specialist | Broad portfolio | Ethanol, biogas |
| 4 | DSM-Firmenich | Switzerland | Major | Enzyme expertise | Selected biofuel applications |
| 5 | BASF | Germany | Major | Chemical integration | Biofuel and biogas enzymes |
| 6 | Kerry | Ireland | Diversified | Applied enzymes | Selected applications |
| 7 | Lallemand | Canada | Yeast-enzyme integrator | Fermentation | Ethanol |
| 8 | Amano Enzyme | Japan | Specialist | Fermentation | Specialty enzymes |
| 9 | Advanced Enzyme Technologies | India | Regional | Cost position | Ethanol, India |
| 10 | Dyadic International | U.S. | Technology | Fungal platform | Cellulosic |
| 11 | Vland Biotech | China | Regional | Scale | Ethanol |
| 12 | Sunson Industry Group | China | Regional | Cost position | Amylases |
| 13 | Shandong Longda Bio-Products | China | Regional | Output scale | Amylases |
| 14 | Biocatalysts | UK | Specialist | Custom enzymes | Niche |
| 15 | Syngenta | Switzerland | Trait-based | Enzyme-expressing corn | Starch ethanol |
| 16 | Codexis | U.S. | Technology | Protein engineering | Emerging |
| 17 | Enzyme Development Corporation | U.S. | Specialist | Niche supply | Niche |
| 18 | Sacco System | Italy | Specialist | Fermentation cultures | Niche |
| 19 | Creative Enzymes | U.S. | Specialist | Catalog enzymes | Niche |
| 20 | Jiangsu Boli Bioproducts | China | Regional | Output scale | Amylases |
Market Share & Competitive Ranking
Estimated shares: Novonesis 45-50%, IFF 15-20%, and the next three players combined roughly 12-15%. Chinese producers together hold an estimated 8-10% and are gaining share in cost-sensitive markets. The full report provides ranked estimates, top-5 and top-10 concentration, and share gain and loss since 2020.
Competitive Benchmarking, Portfolio and Technology Positioning
Companies are compared based on revenue exposure, enzyme portfolio, R&D investment, geographic presence, production capacity, and sustainability efforts. Novonesis and IFF lead the market through their broad product ranges and strong technology capabilities, while AB Enzymes and DSM-Firmenich have established positions in specialized enzyme products. Chinese and Indian manufacturers are emerging as cost-competitive alternatives. In terms of portfolio positioning, Novonesis and IFF offer a wide range of solutions, while Dyadic and Codexis focus on technology-driven platforms, and Syngenta stands out through its work on crop traits. Technology comparisons also consider patents, new product launches, partnerships, and commercial adoption.
Application and Geographic Competitive Benchmarking
In starch ethanol, Novonesis and IFF are leading suppliers, while Lallemand has a strong position through its combined yeast and enzyme solutions. In cellulosic biofuels, Novonesis and IFF remain key players, with Dyadic competing through its technology platform. AB Enzymes and Novonesis are also notable in biogas applications. Geographically, global leaders have a strong presence in North America and Europe, while Advanced Enzyme Technologies is well positioned in India and Chinese producers are gaining ground across Asia. Opportunities remain in biogas, sustainable aviation fuel, and enzymes designed for non-grain feedstocks.
Manufacturing & Capacity, Customer & Channel Benchmarking
Leading manufacturers operate large fermentation facilities in countries such as Denmark, the United States, China, and Brazil. Meanwhile, regional producers in India and China are expanding their manufacturing capacity to serve growing local demand and strengthen their market position. Customer and channel benchmarking looks at how companies reach ethanol producers, including direct sales to large plants, distributor networks, on-site trial support, and integrated yeast-enzyme solutions.
Strategic Developments and M&A Landscape
Recent developments over the past two to three years include the formation of Novonesis through a merger, portfolio changes among diversified ingredient companies, capacity expansion in India and China, and partnerships focused on cellulosic biofuels and sustainable aviation fuel. Going forward, M&A activity is likely to focus on regional consolidation, acquisitions of protein-engineering technologies, and the integration of yeast and enzyme capabilities. The report tracks transactions by acquirer, target, year, geography, technology, strategic rationale, and deal value where disclosed.
Opportunity & White-Space Analysis
The global biofuel enzymes market offers promising growth opportunities in biogas, cellulosic ethanol, and sustainable aviation fuel. Biogas and anaerobic digestion enzymes already account for around 9% of market revenue and are growing faster than the overall market. Cellulosic and advanced ethanol enzymes could represent a USD 0.7–1.0 billion opportunity by 2035 under the upside scenario.
Other areas with growth potential include enzymes that improve corn-oil and protein co-product recovery, as well as solutions for processing feedstocks used in aviation fuels. Localized enzyme production in India and Southeast Asia also offers opportunities to reduce import dependence, improve supply reliability, and serve regional producers more efficiently.
Industry Structure (Porter’s Five Forces)
- Supplier power: Low-Medium. Inputs are commodity fermentation substrates.
- Buyer power: High. Large producers concentrate and run performance trials.
- New entrants: Low-Medium. Strain IP and approvals are barriers, but Chinese producers are entering.
- Substitutes: Low. Chemical hydrolysis is uncompetitive.
- Rivalry: Medium-High. Concentrated leaders compete on yield performance and service.
PESTLE Analysis
- Political: Government blending mandates and biofuel support policies encourage enzyme demand and promote biofuel production.
- Economic: Fluctuations in feedstock costs and fuel prices affect production expenses and the profitability of biofuel producers.
- Social: Rural employment, farmer income, and energy security support the adoption of biofuels.
- Technological: Advances in protein engineering and crop traits are improving enzyme efficiency and biofuel production.
- Legal: Carbon-intensity credits and regulatory requirements influence biofuel economics and create incentives for cleaner fuel production.
- Environmental: The potential to reduce carbon emissions supports demand for biofuel enzymes, while vehicle electrification may limit long-term growth in road-transport biofuels.
Market Attractiveness
Starch ethanol enzymes are attractive (large, stable, concentrated). Cellulosic enzymes are moderate (high potential, commercialization risk). Biogas enzymes are highly attractive (rapid growth, fragmented competition). Biodiesel enzymes are challenging (feedstock-driven volatility). By region, Asia Pacific is highly attractive, North America is attractive, and Europe is moderate.
Future Outlook: How Will Efficiency, Advanced Feedstocks, and Regional Localization Reshape Competitive Advantage?
Enzyme loading will increasingly drive the price against carbon-intensity benefits. Capacity growth will concentrate in Asia Pacific, pricing will stay stable to slightly decline in commodity grades with premiums in specialty cocktails, and the leaders’ share is expected to hold or modestly erode against regional challengers. Likely winners are the scale and technology leaders and well-positioned regional producers. Future profit pools lie in biogas, advanced feedstocks, and co-product enzymes.
Key Strategic Questions
- How large is the global biofuel enzymes market, and what revenue will it reach by 2035?
- Which enzyme classes and applications generate the highest growth contribution?
- How will mandates in the U.S., Brazil, India, and Europe change enzyme demand?
- How will electrification affect long-term ethanol-linked enzyme volumes?
- What are the price-per-gallon benchmarks across starch and cellulosic pathways?
- Where does supply exceed or fall short of demand by region?
- How concentrated is the market, and how are shares shifting?
- How do carbon-intensity incentives reshape enzyme value?
- How are M&A and partnerships changing competitive structure?
- Where are the biggest white spaces by feedstock, geography, and application?
- How will Chinese and Indian producers affect global pricing?
- What are the base, upside, and downside scenarios, and what triggers each?
List of Segments
By Enzyme Type
- Amylases (alpha-amylase, glucoamylase and blends)
- Cellulases and Hemicellulases
- Proteases
- Xylanases
- Phytases
- Pullulanases
- Beta-glucanases
- Lipases
By Application
- Starch-Based Ethanol
- Cellulosic and Advanced Ethanol
- Biodiesel and Renewable Diesel
- Biogas
- Others
By Feedstock
- Corn
- Sugarcane and Molasses
- Wheat and Other Grains
- Cassava
- Lignocellulosic Residues
- Oils and Fats
By Region
- North America
- Asia Pacific
- Europe
- Latin America
- Rest of the World
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.
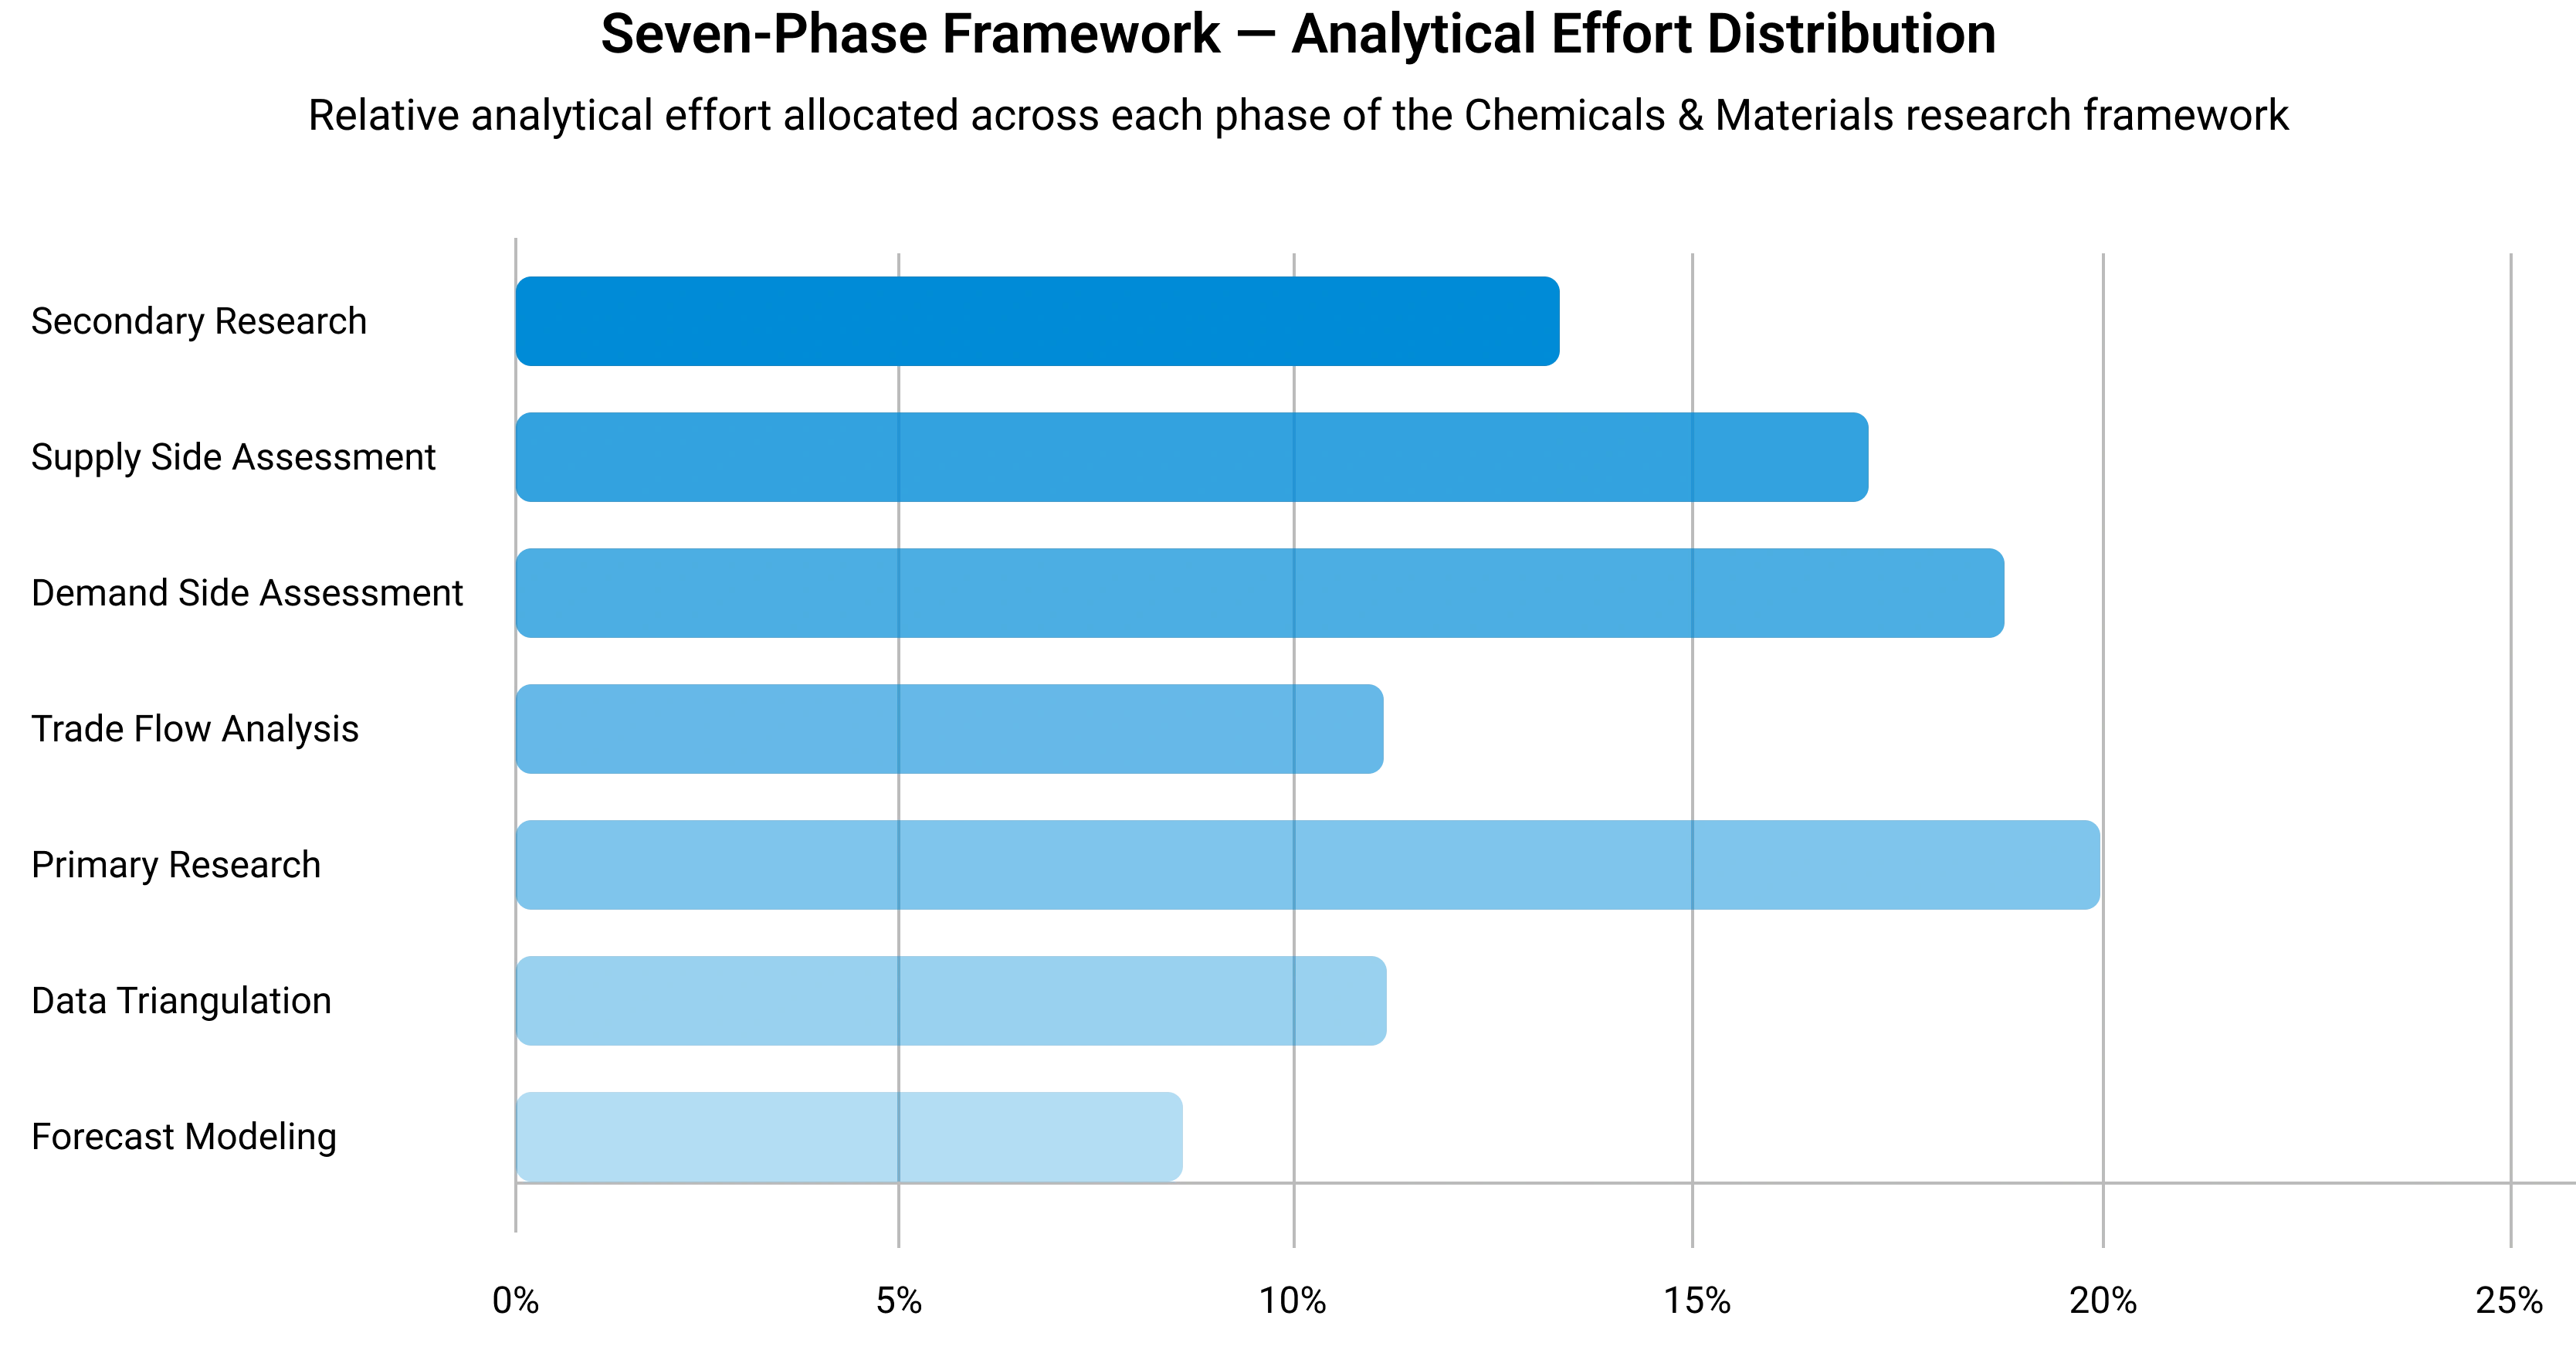
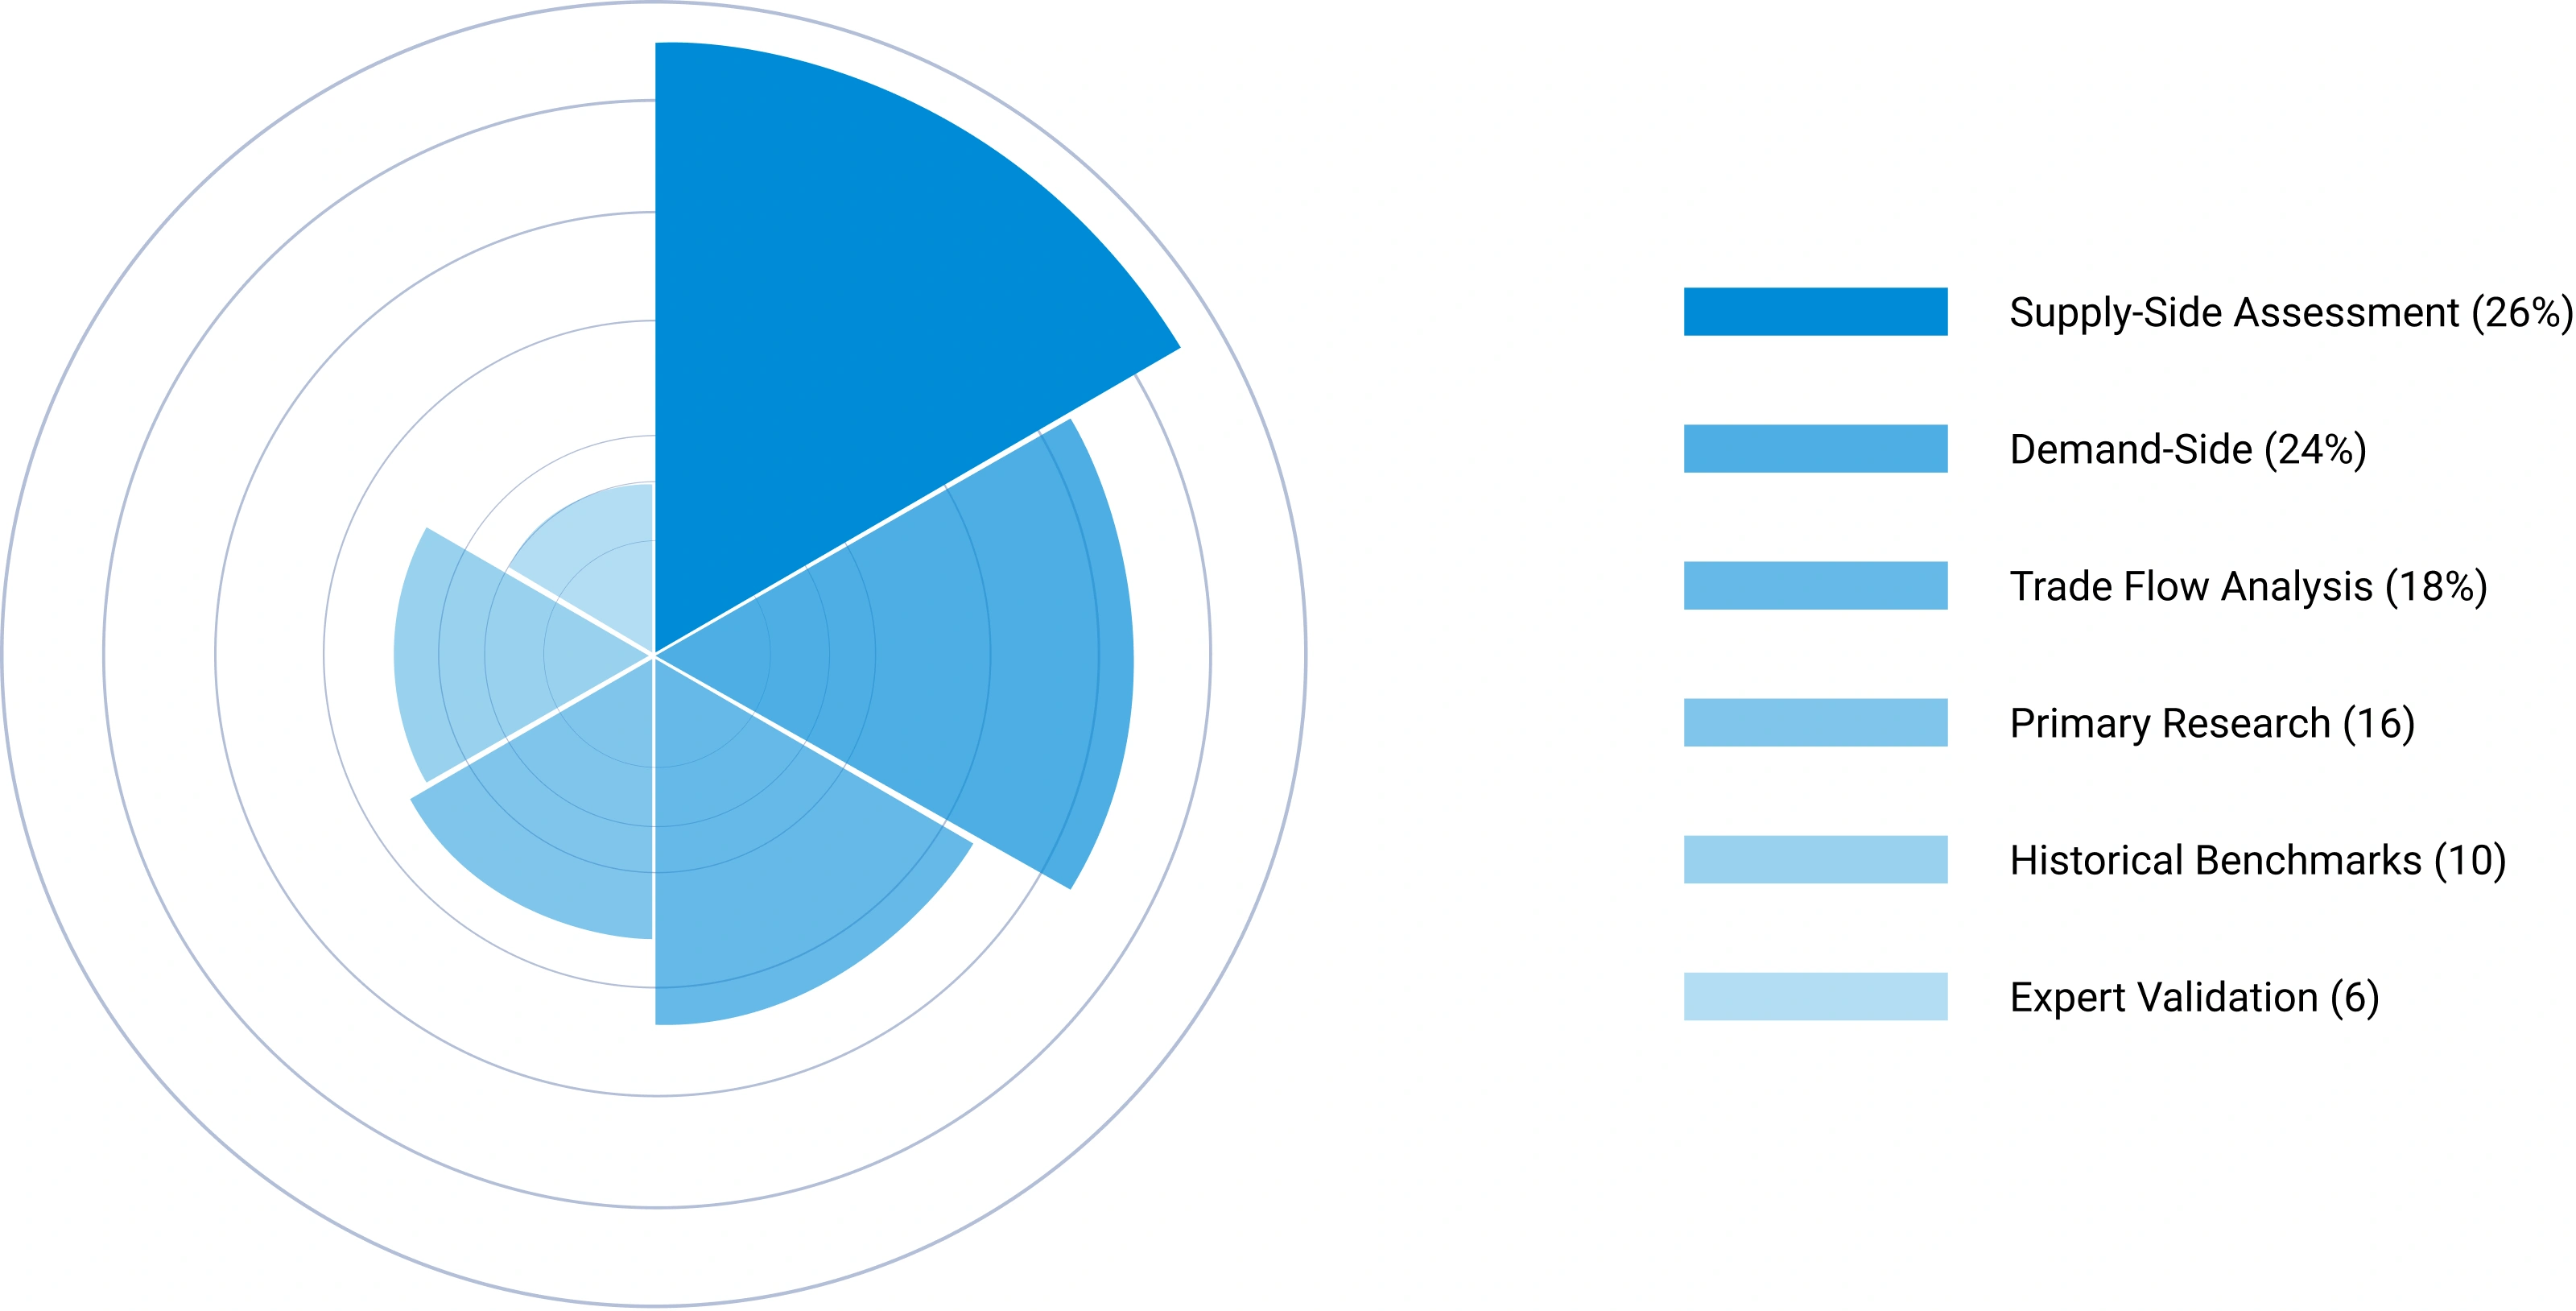
Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework
Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
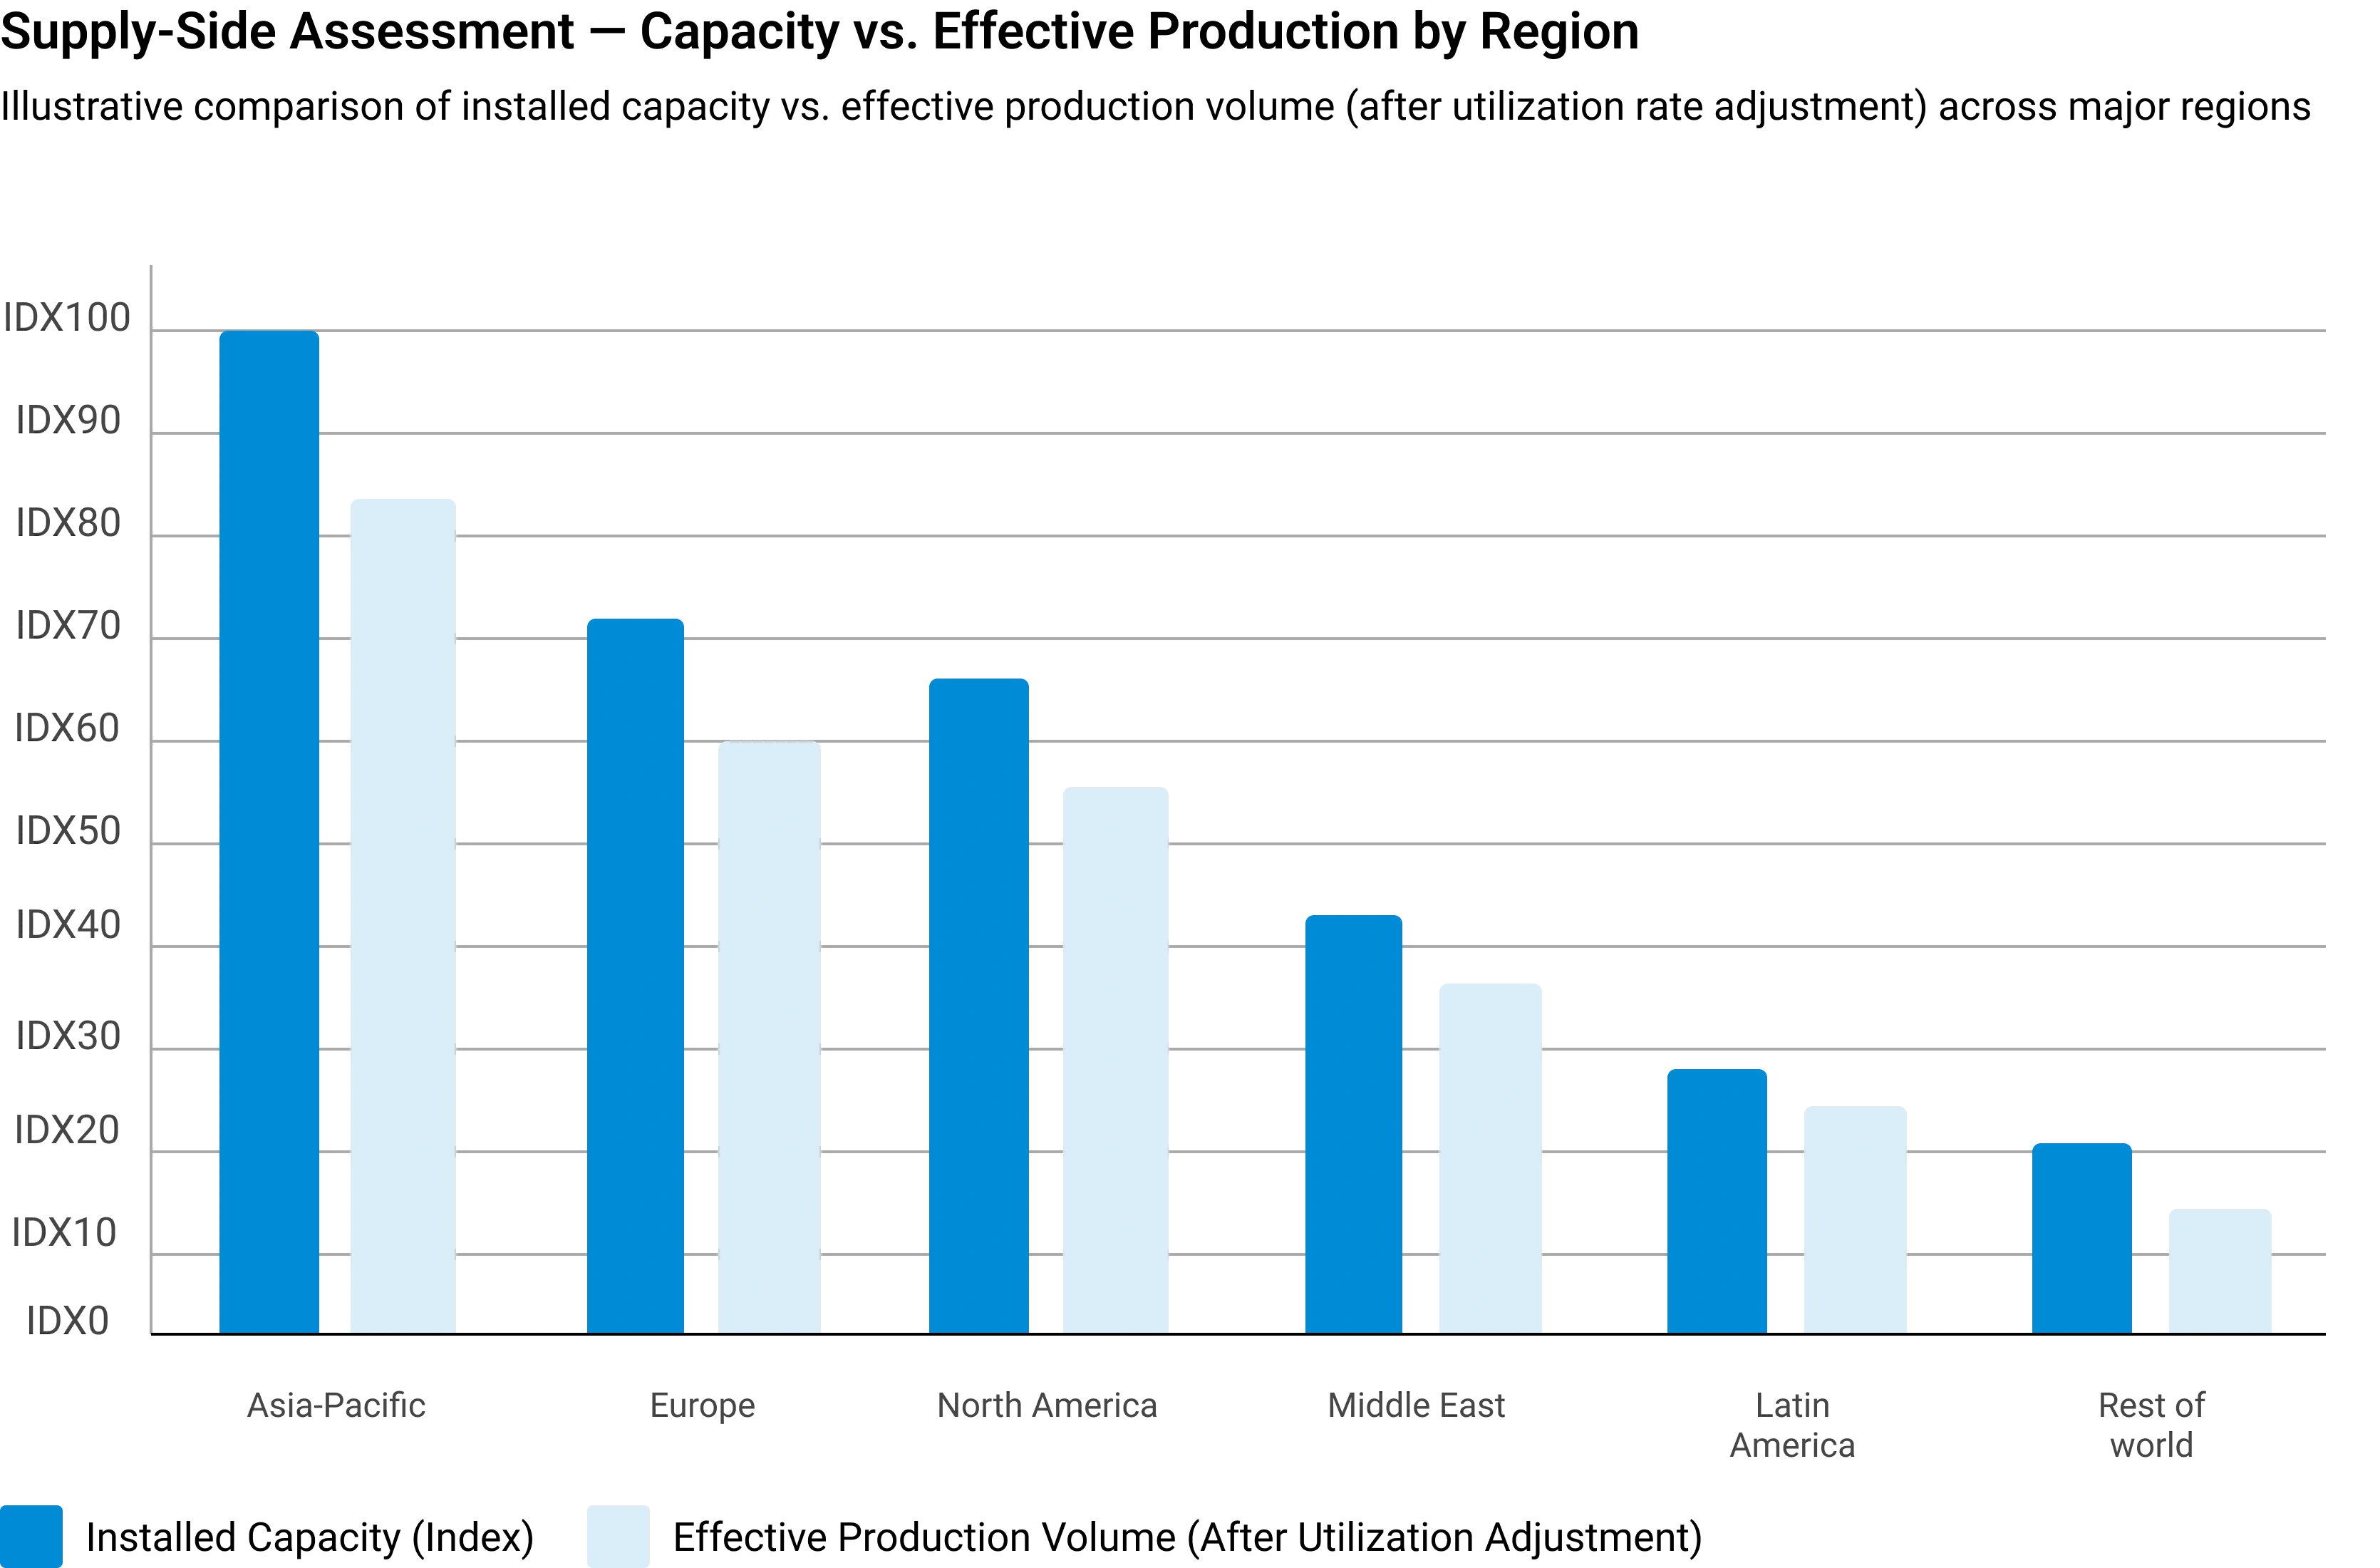
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions
Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
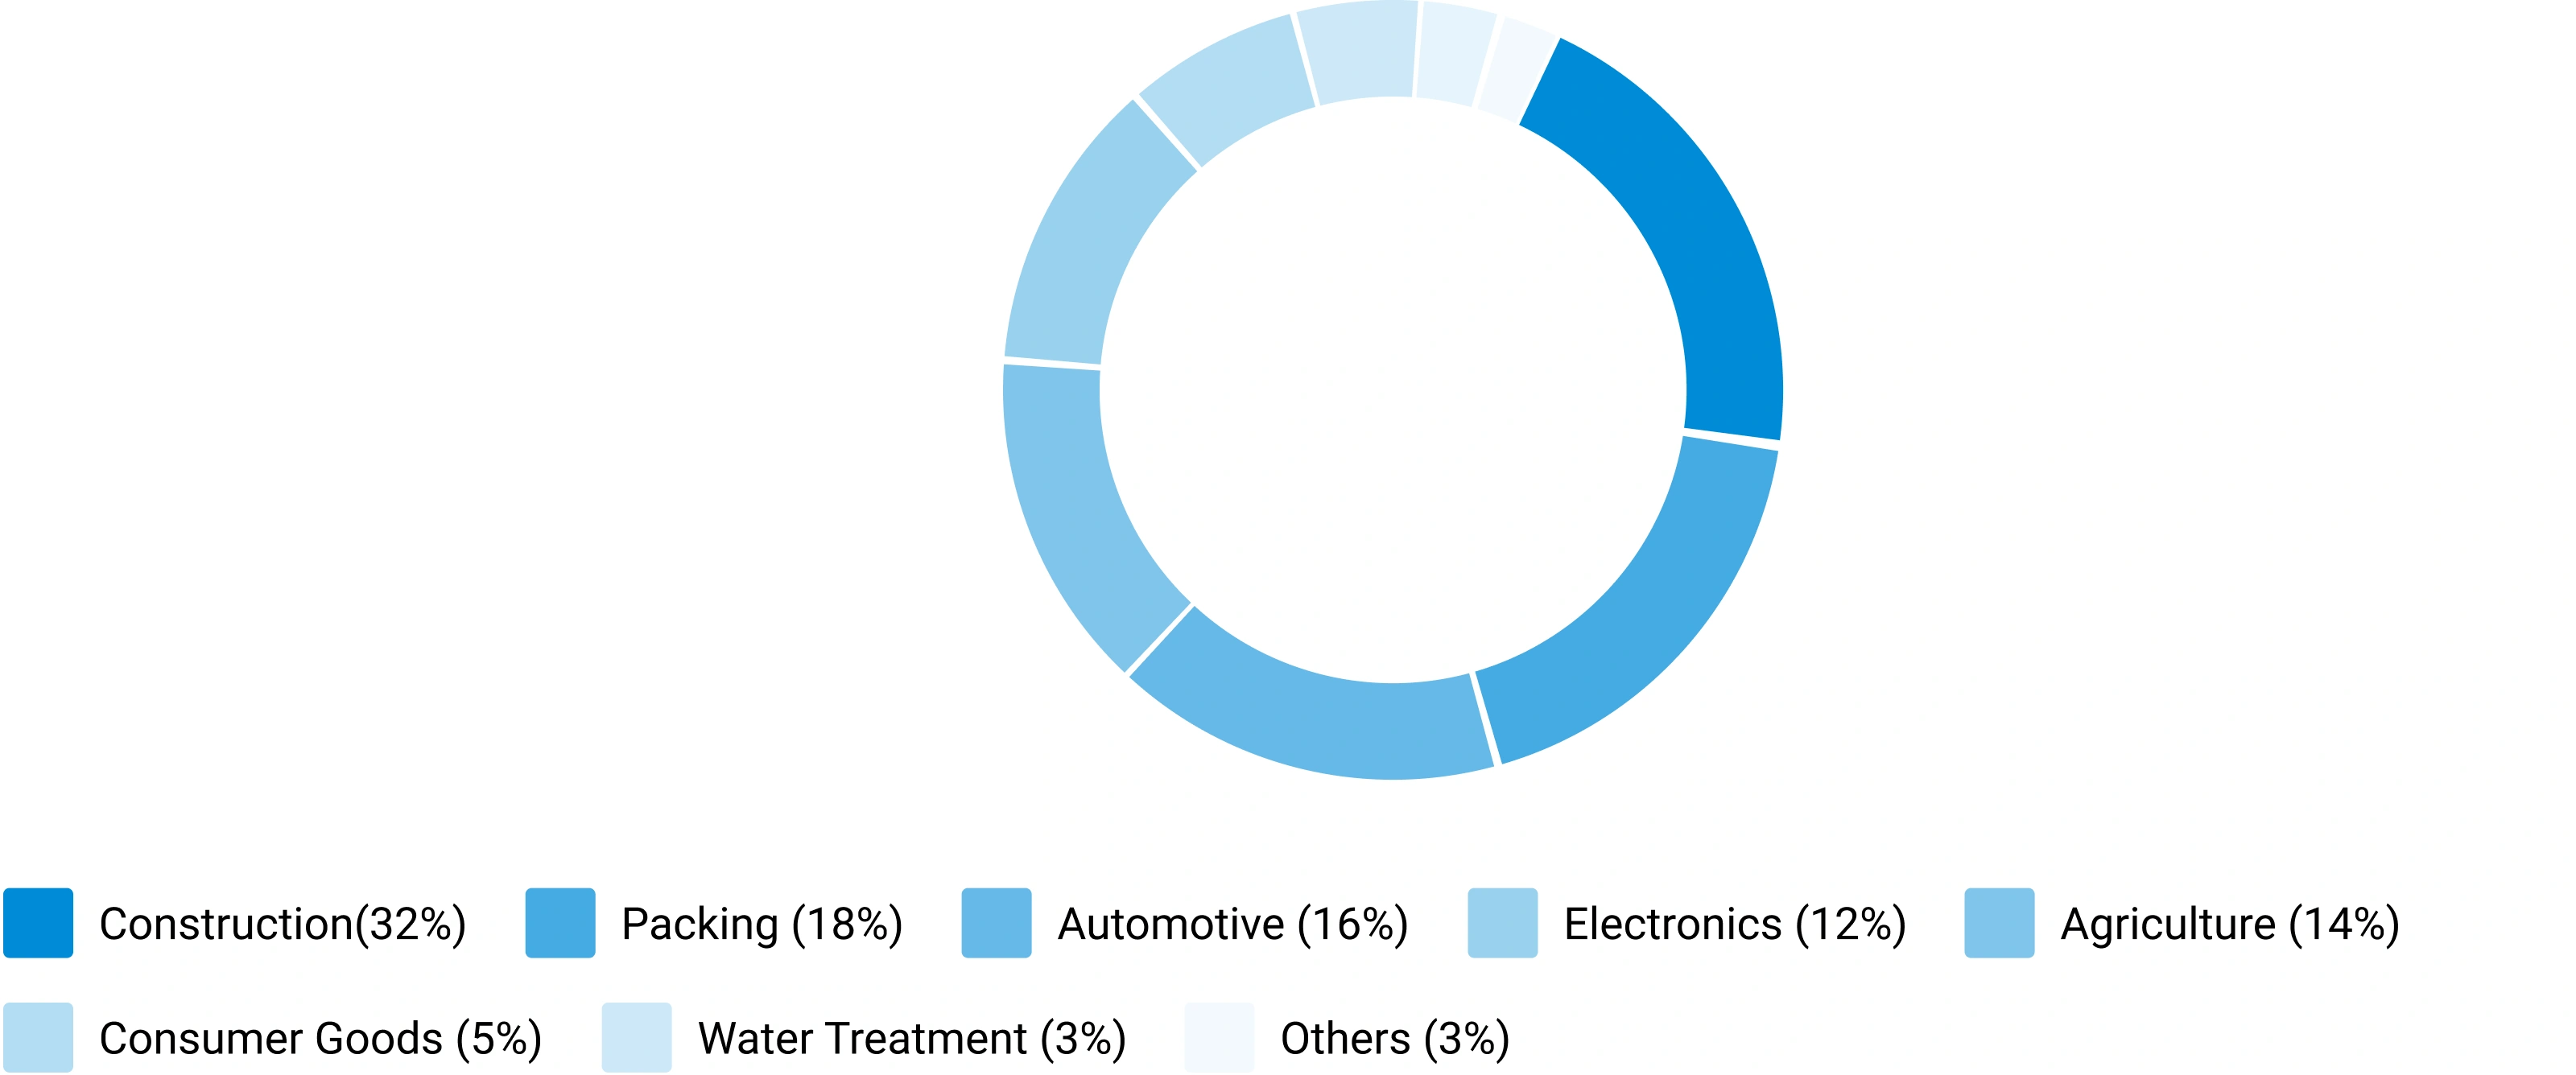
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries
Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
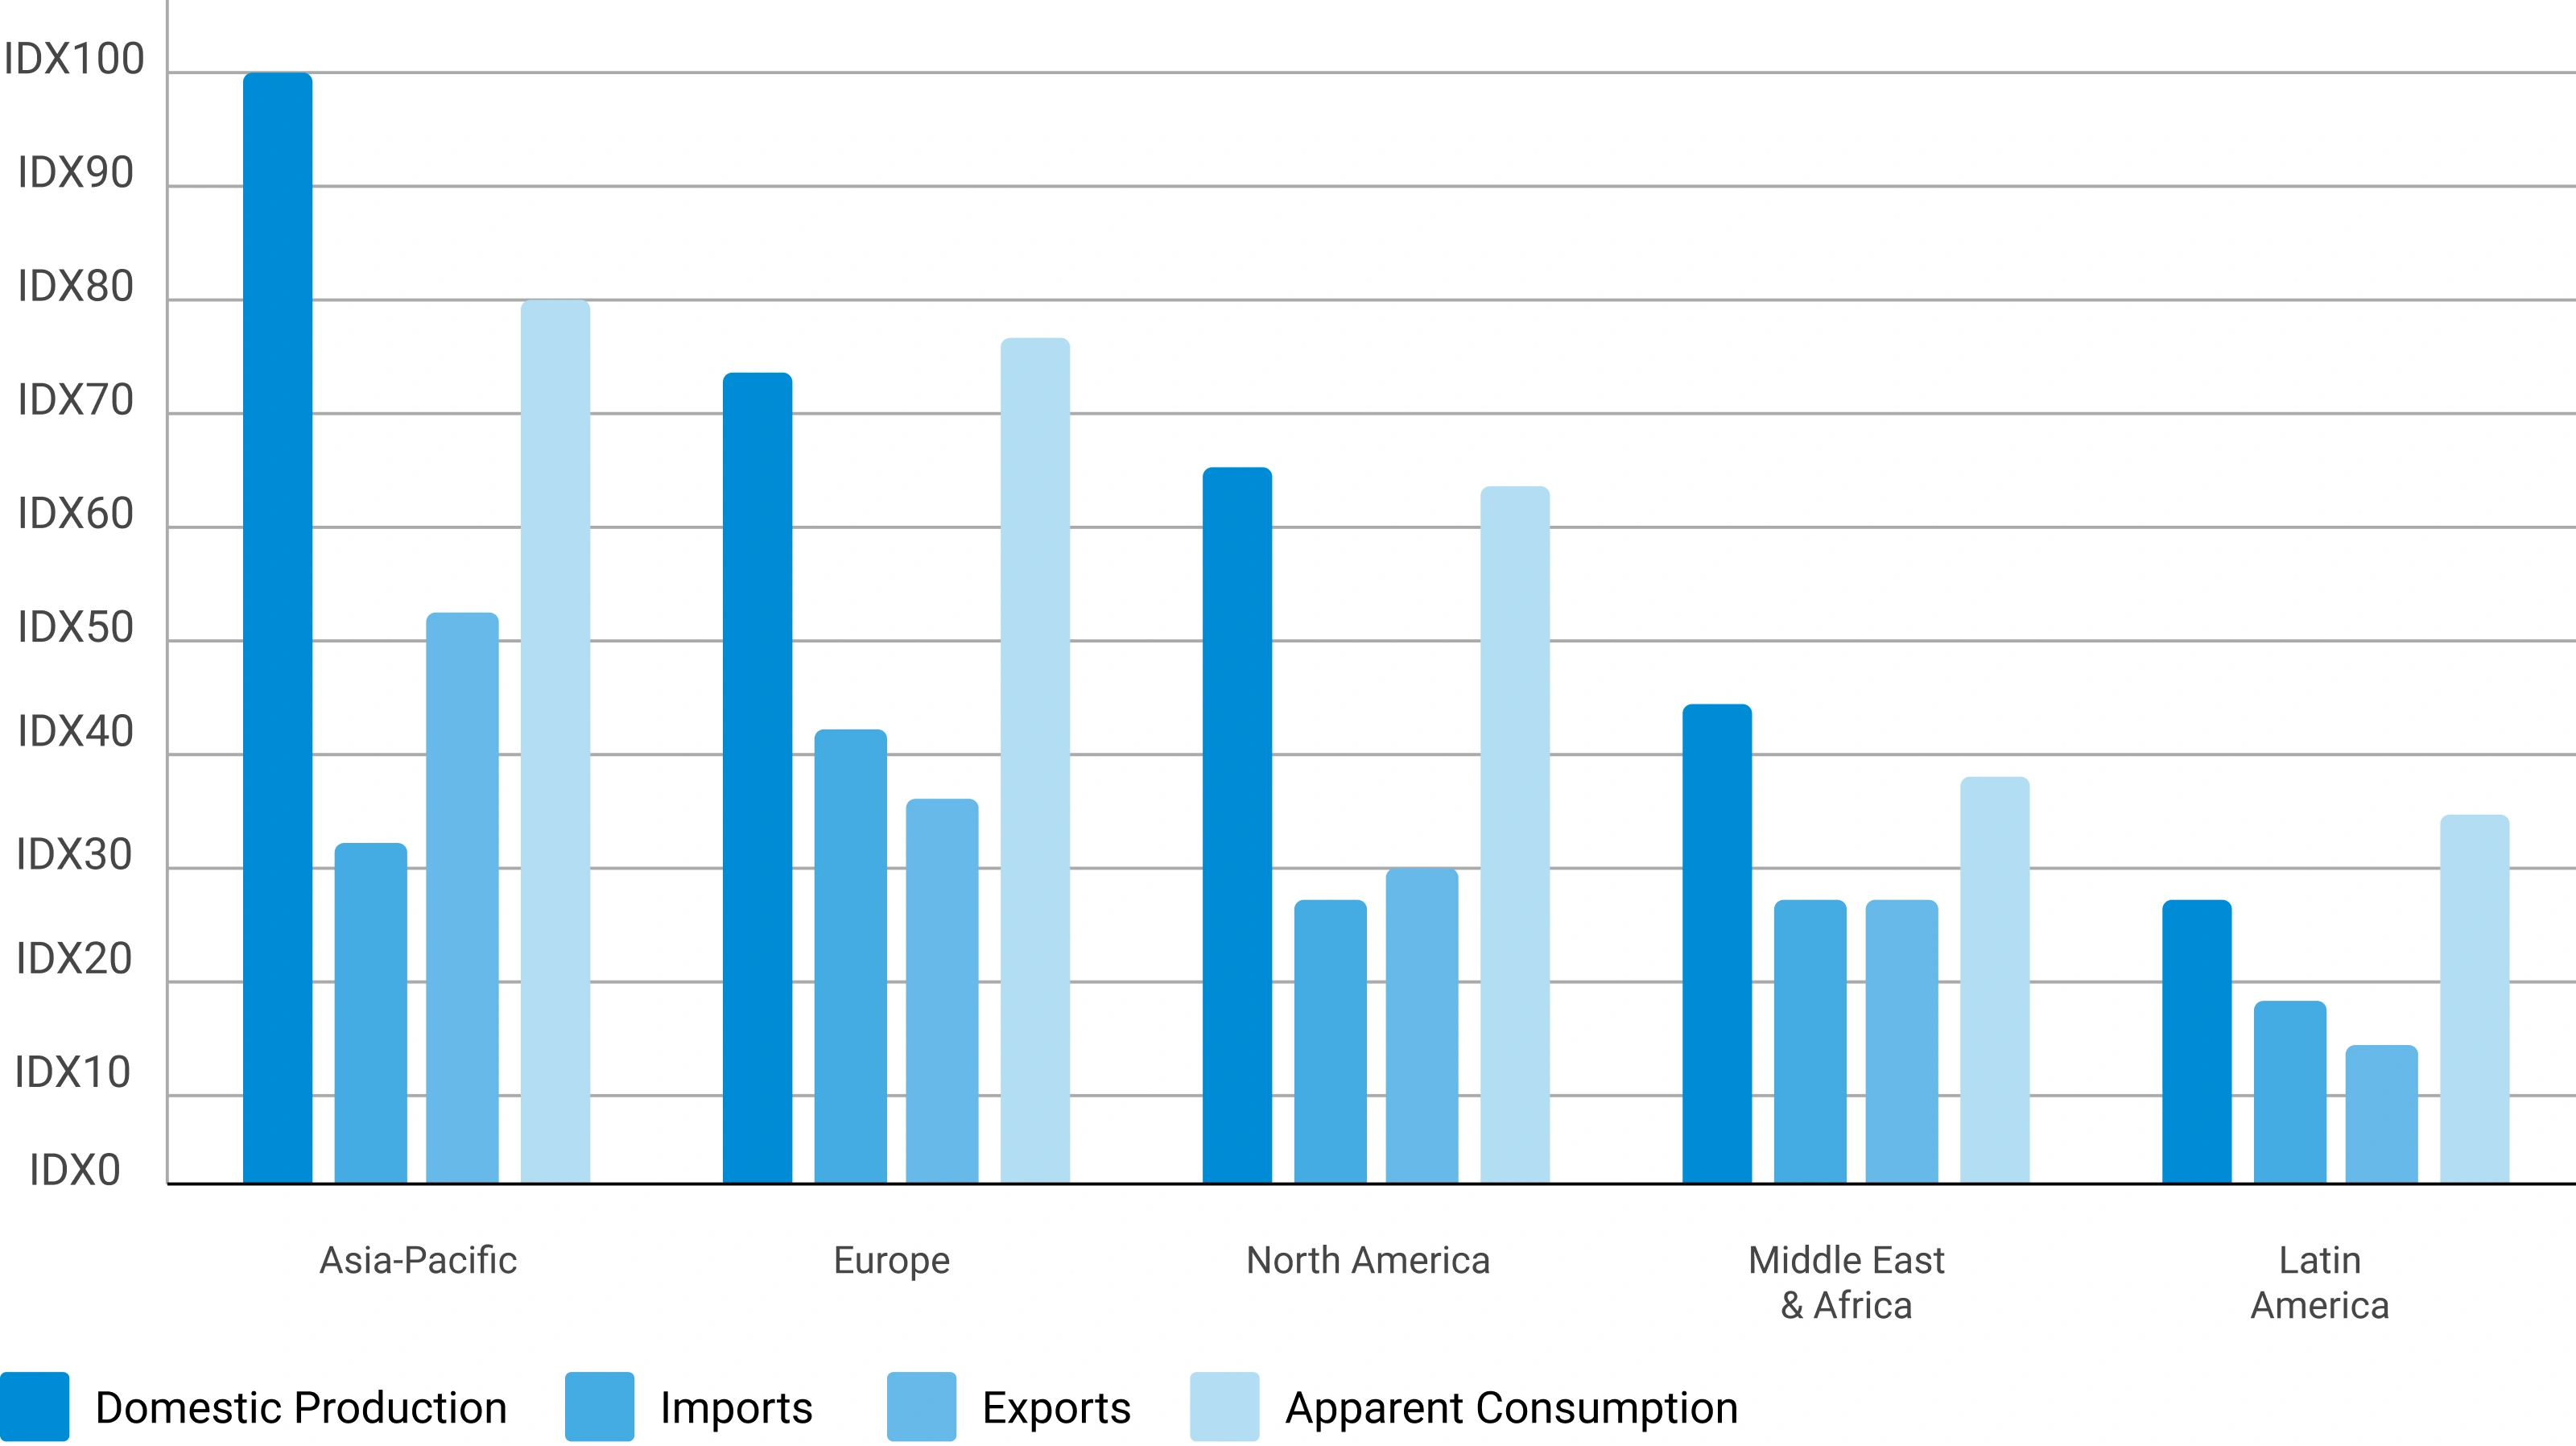
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency
Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.
Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.
Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.
Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
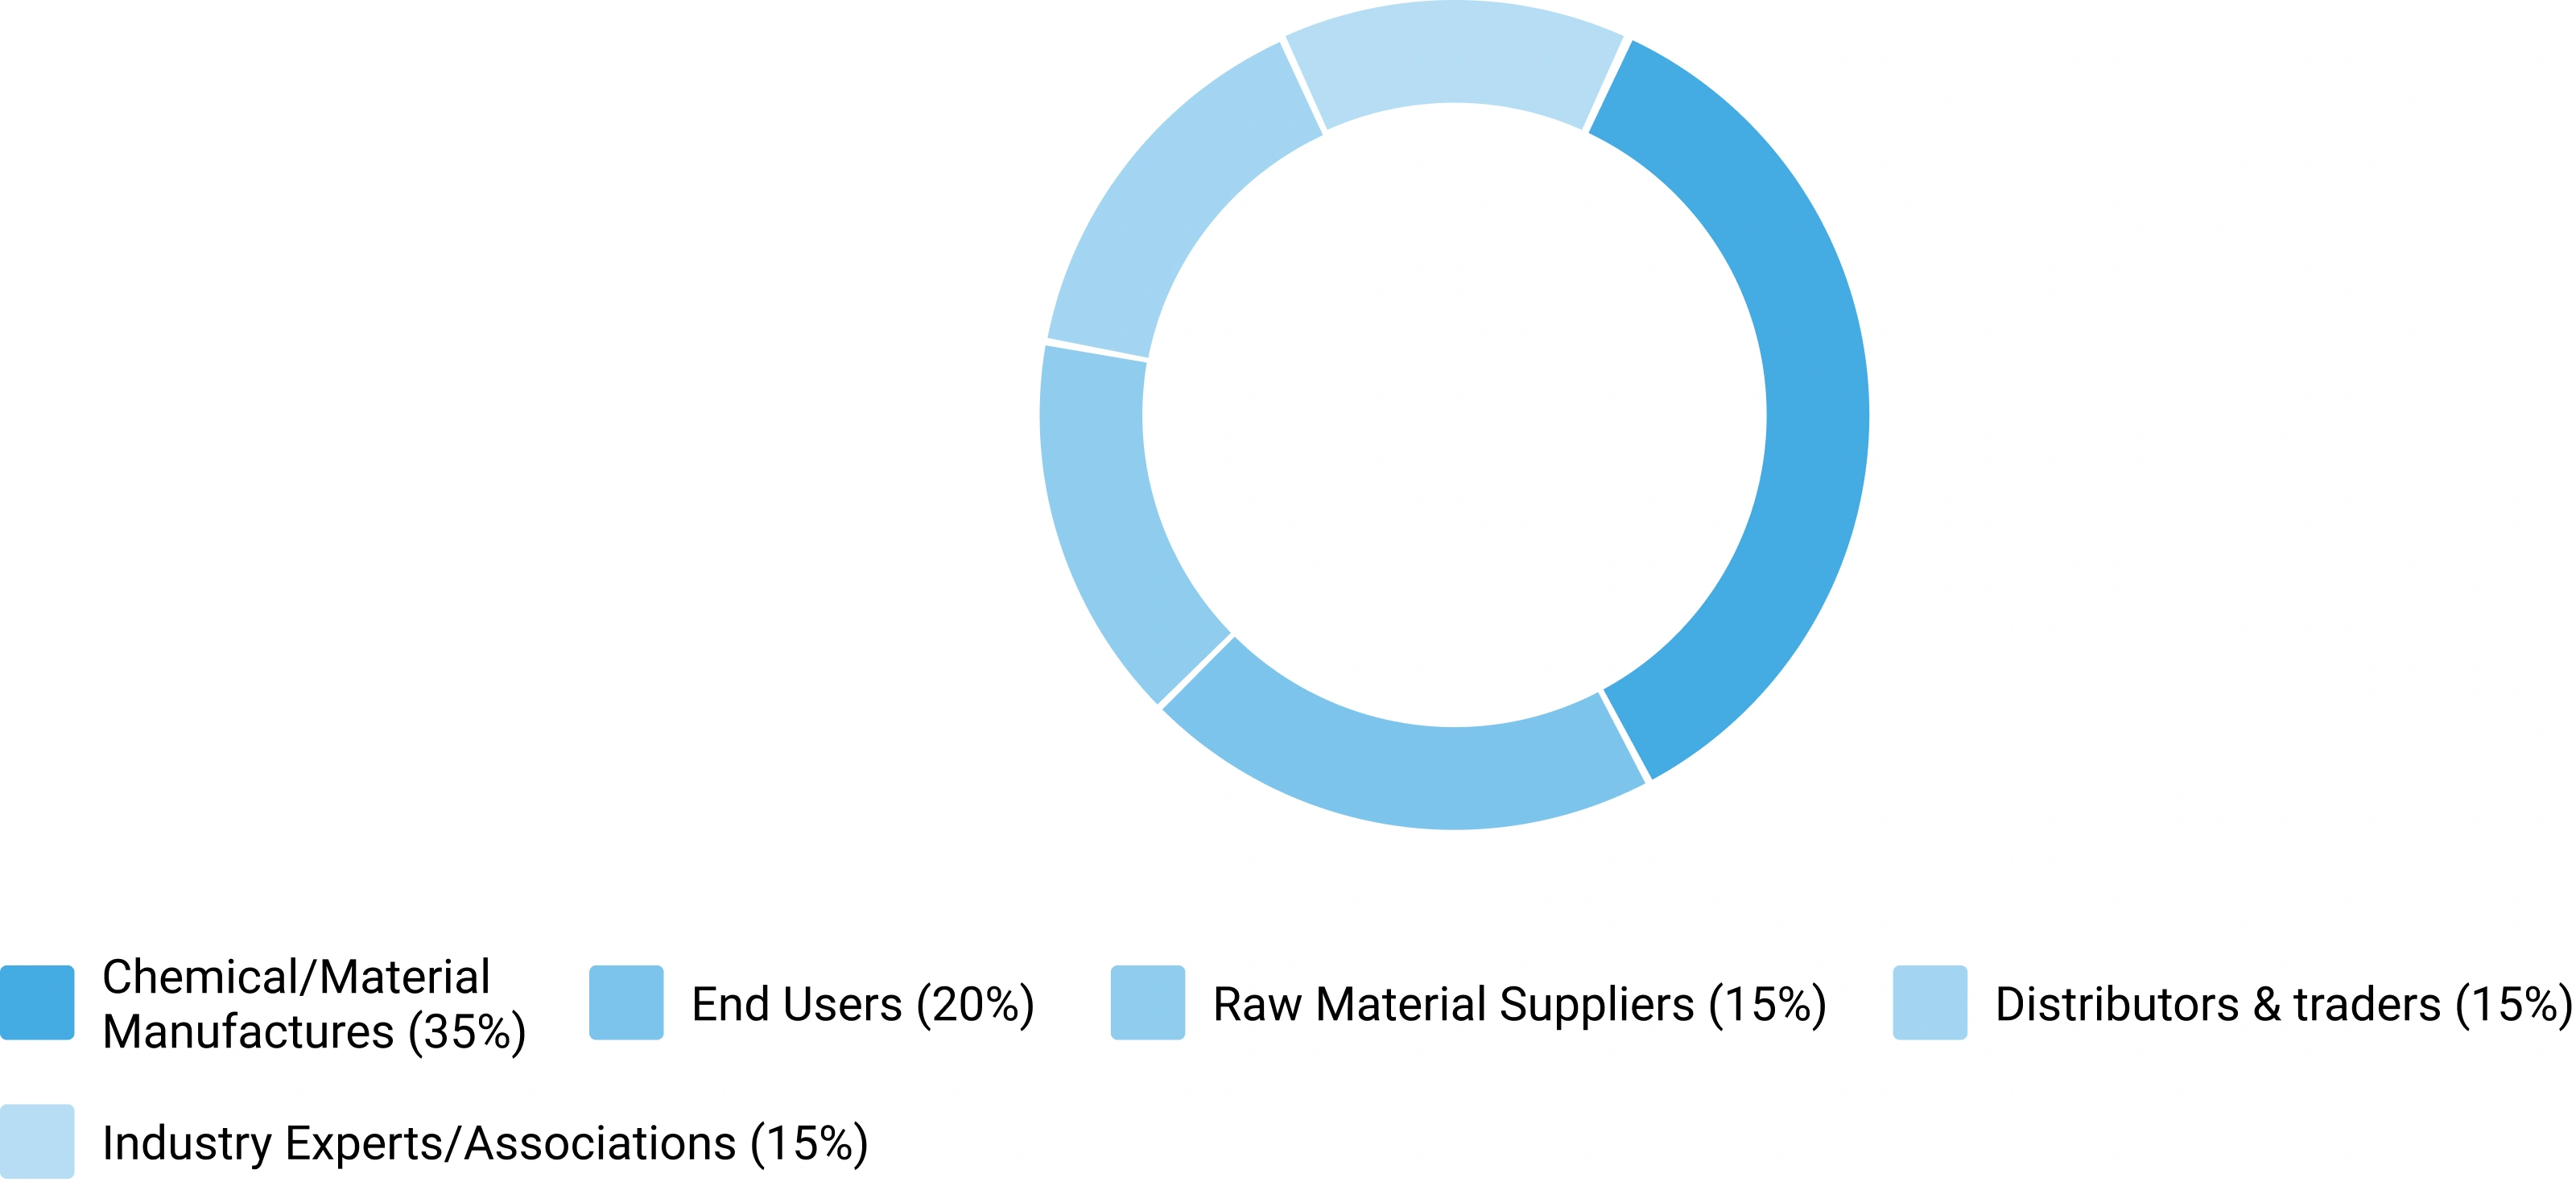
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)
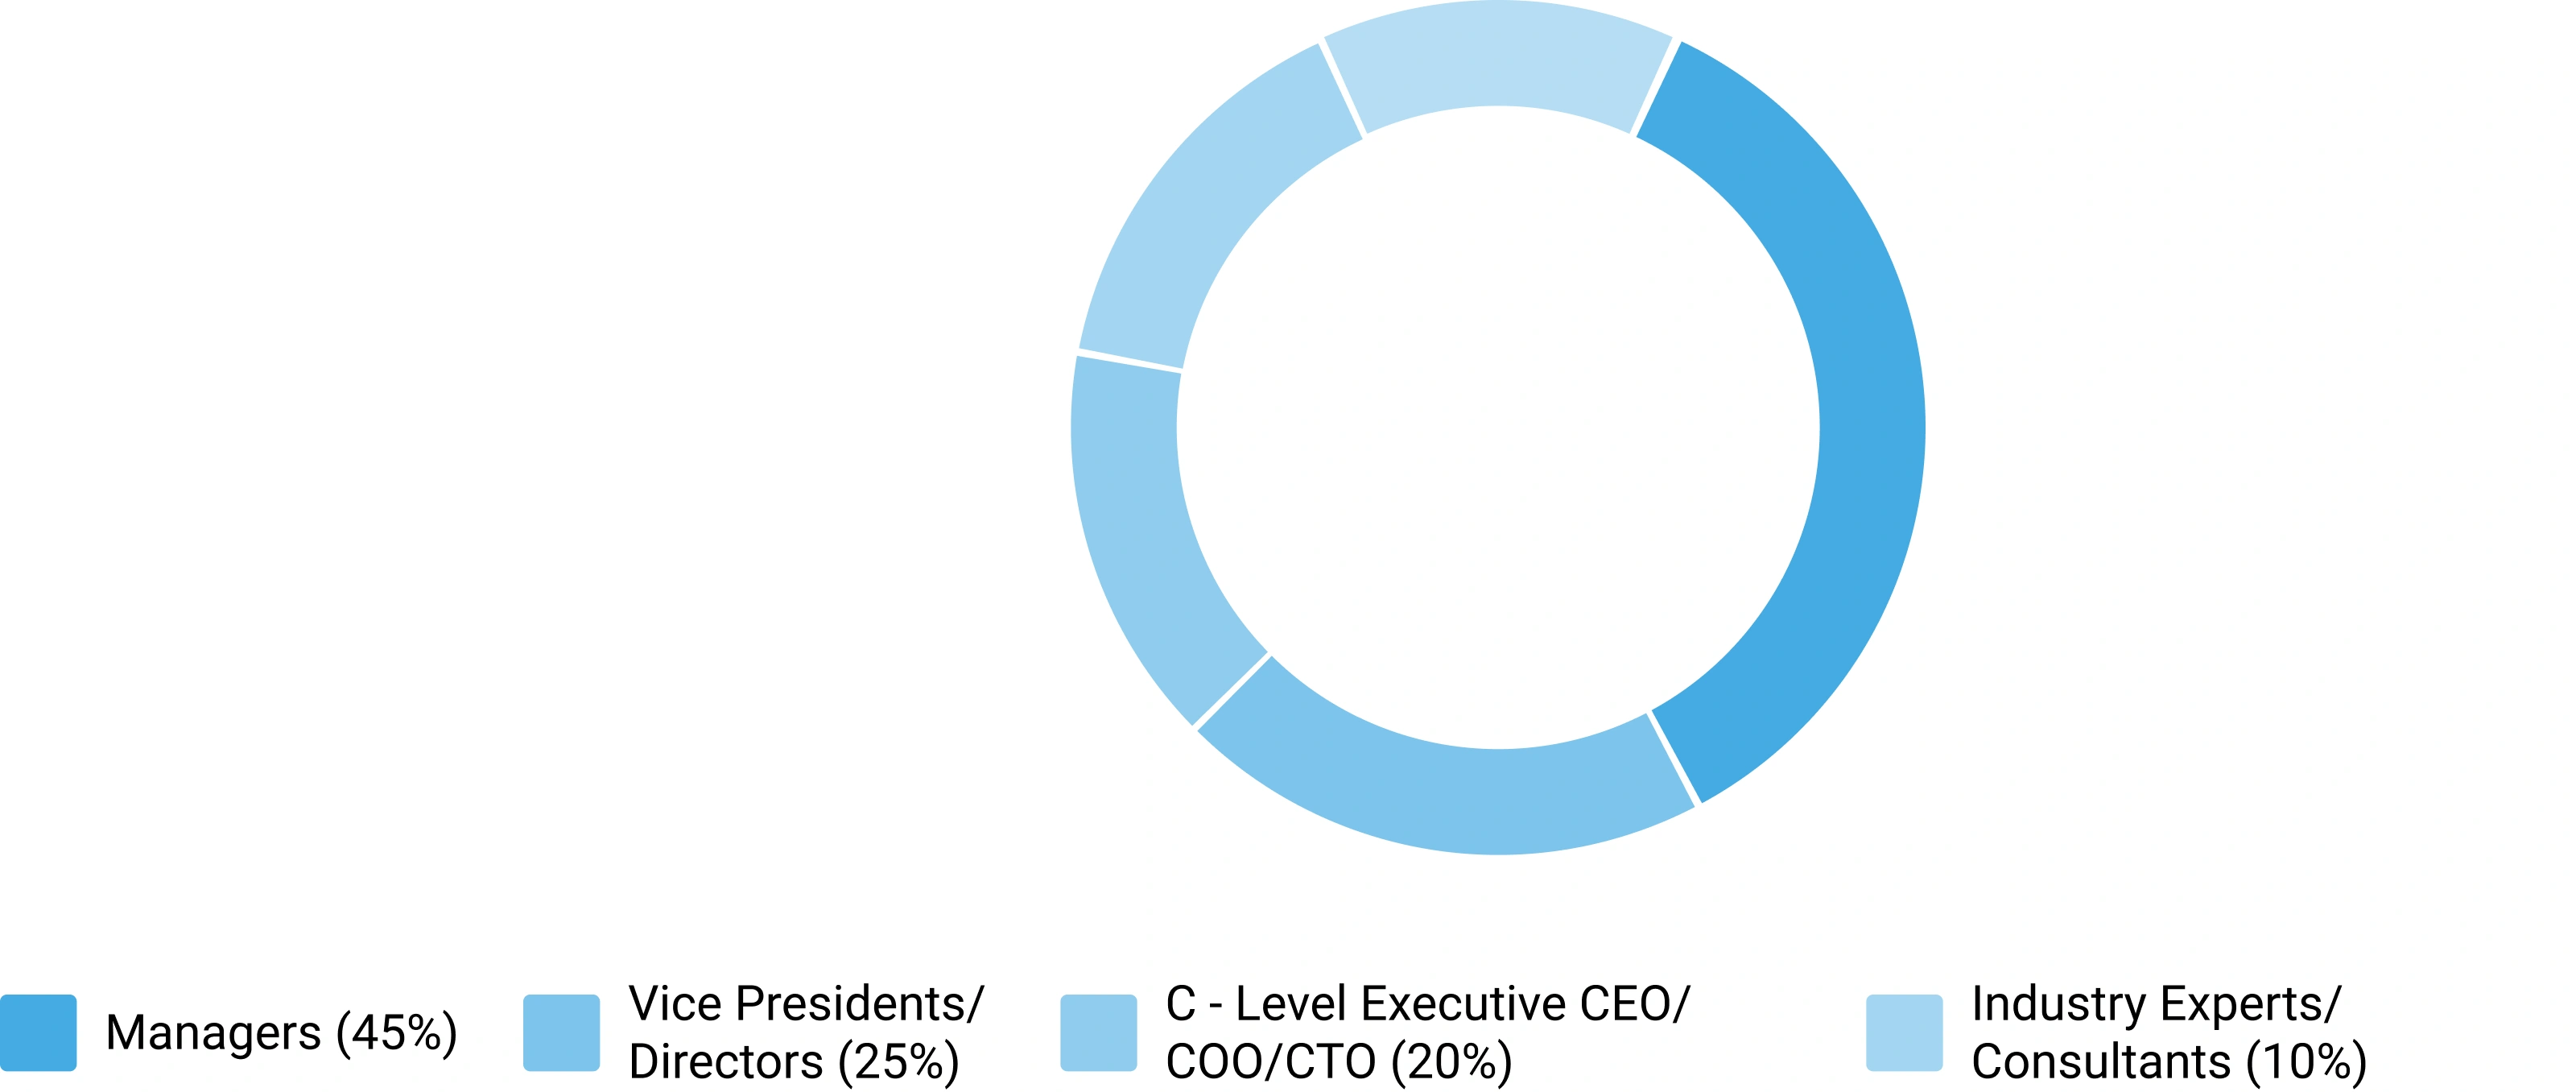
Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)
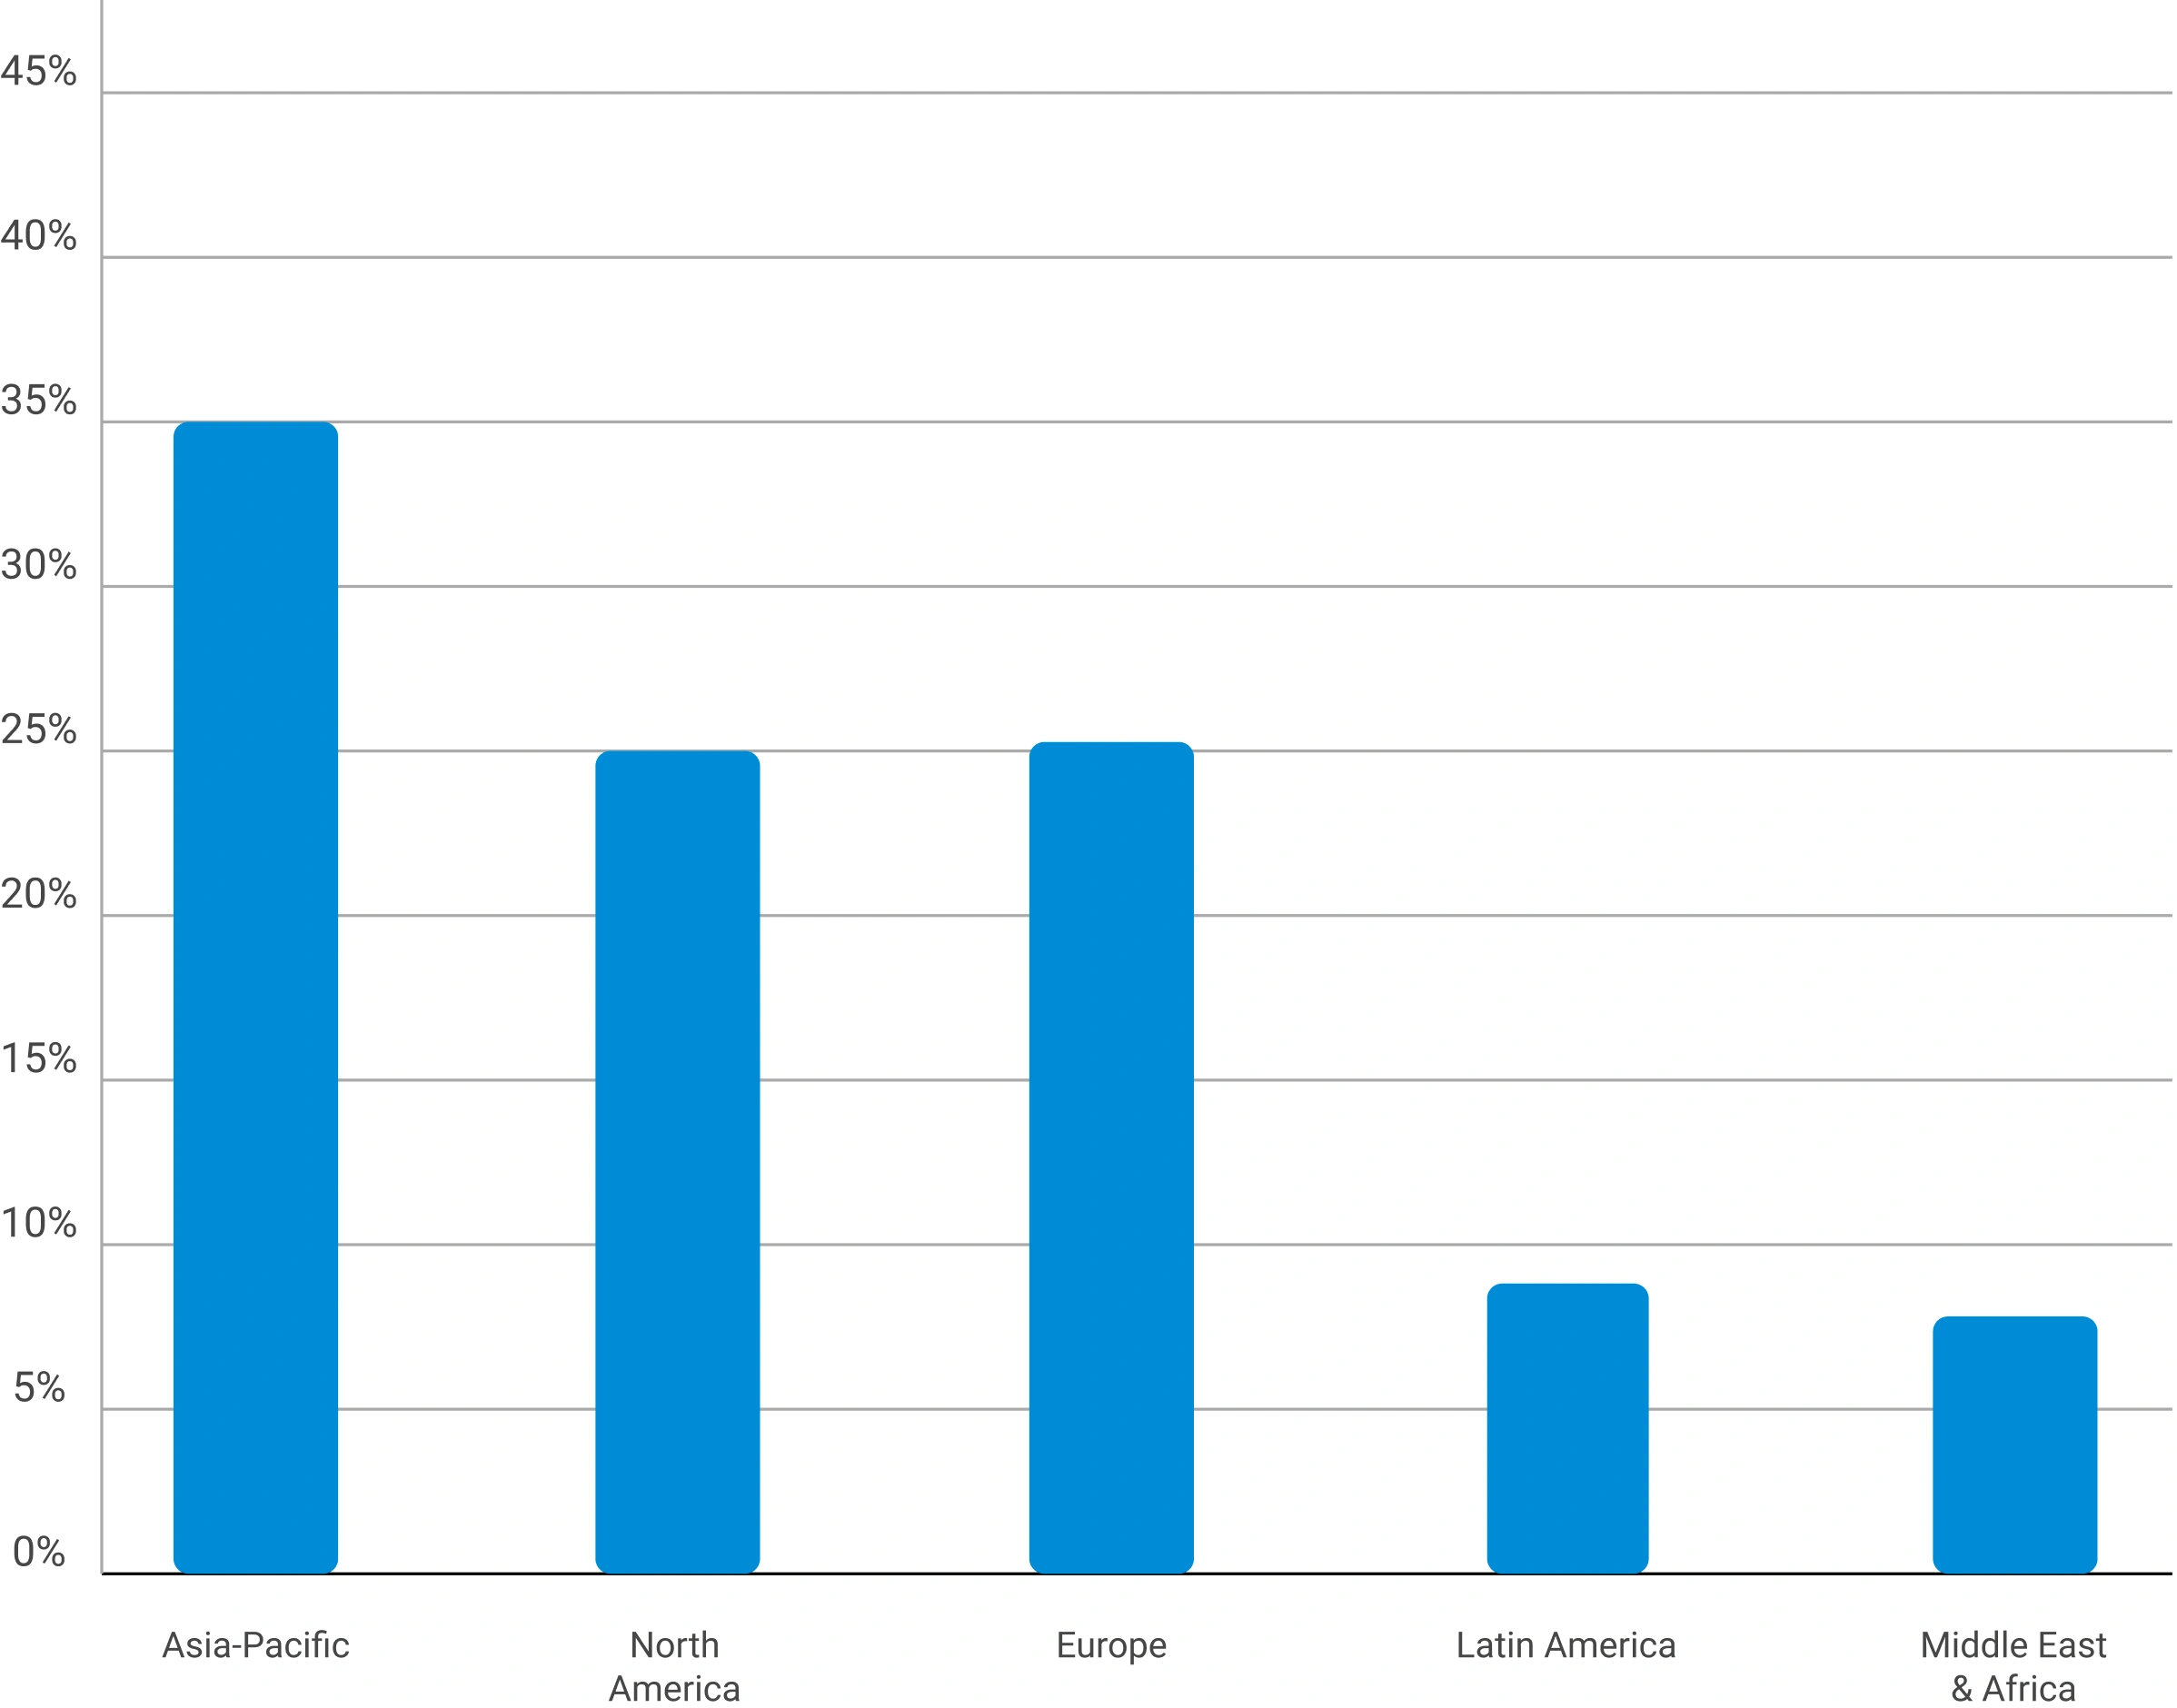
Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)
Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate
Phase 7 — Forecast Modeling: Projecting Future Market Evolution
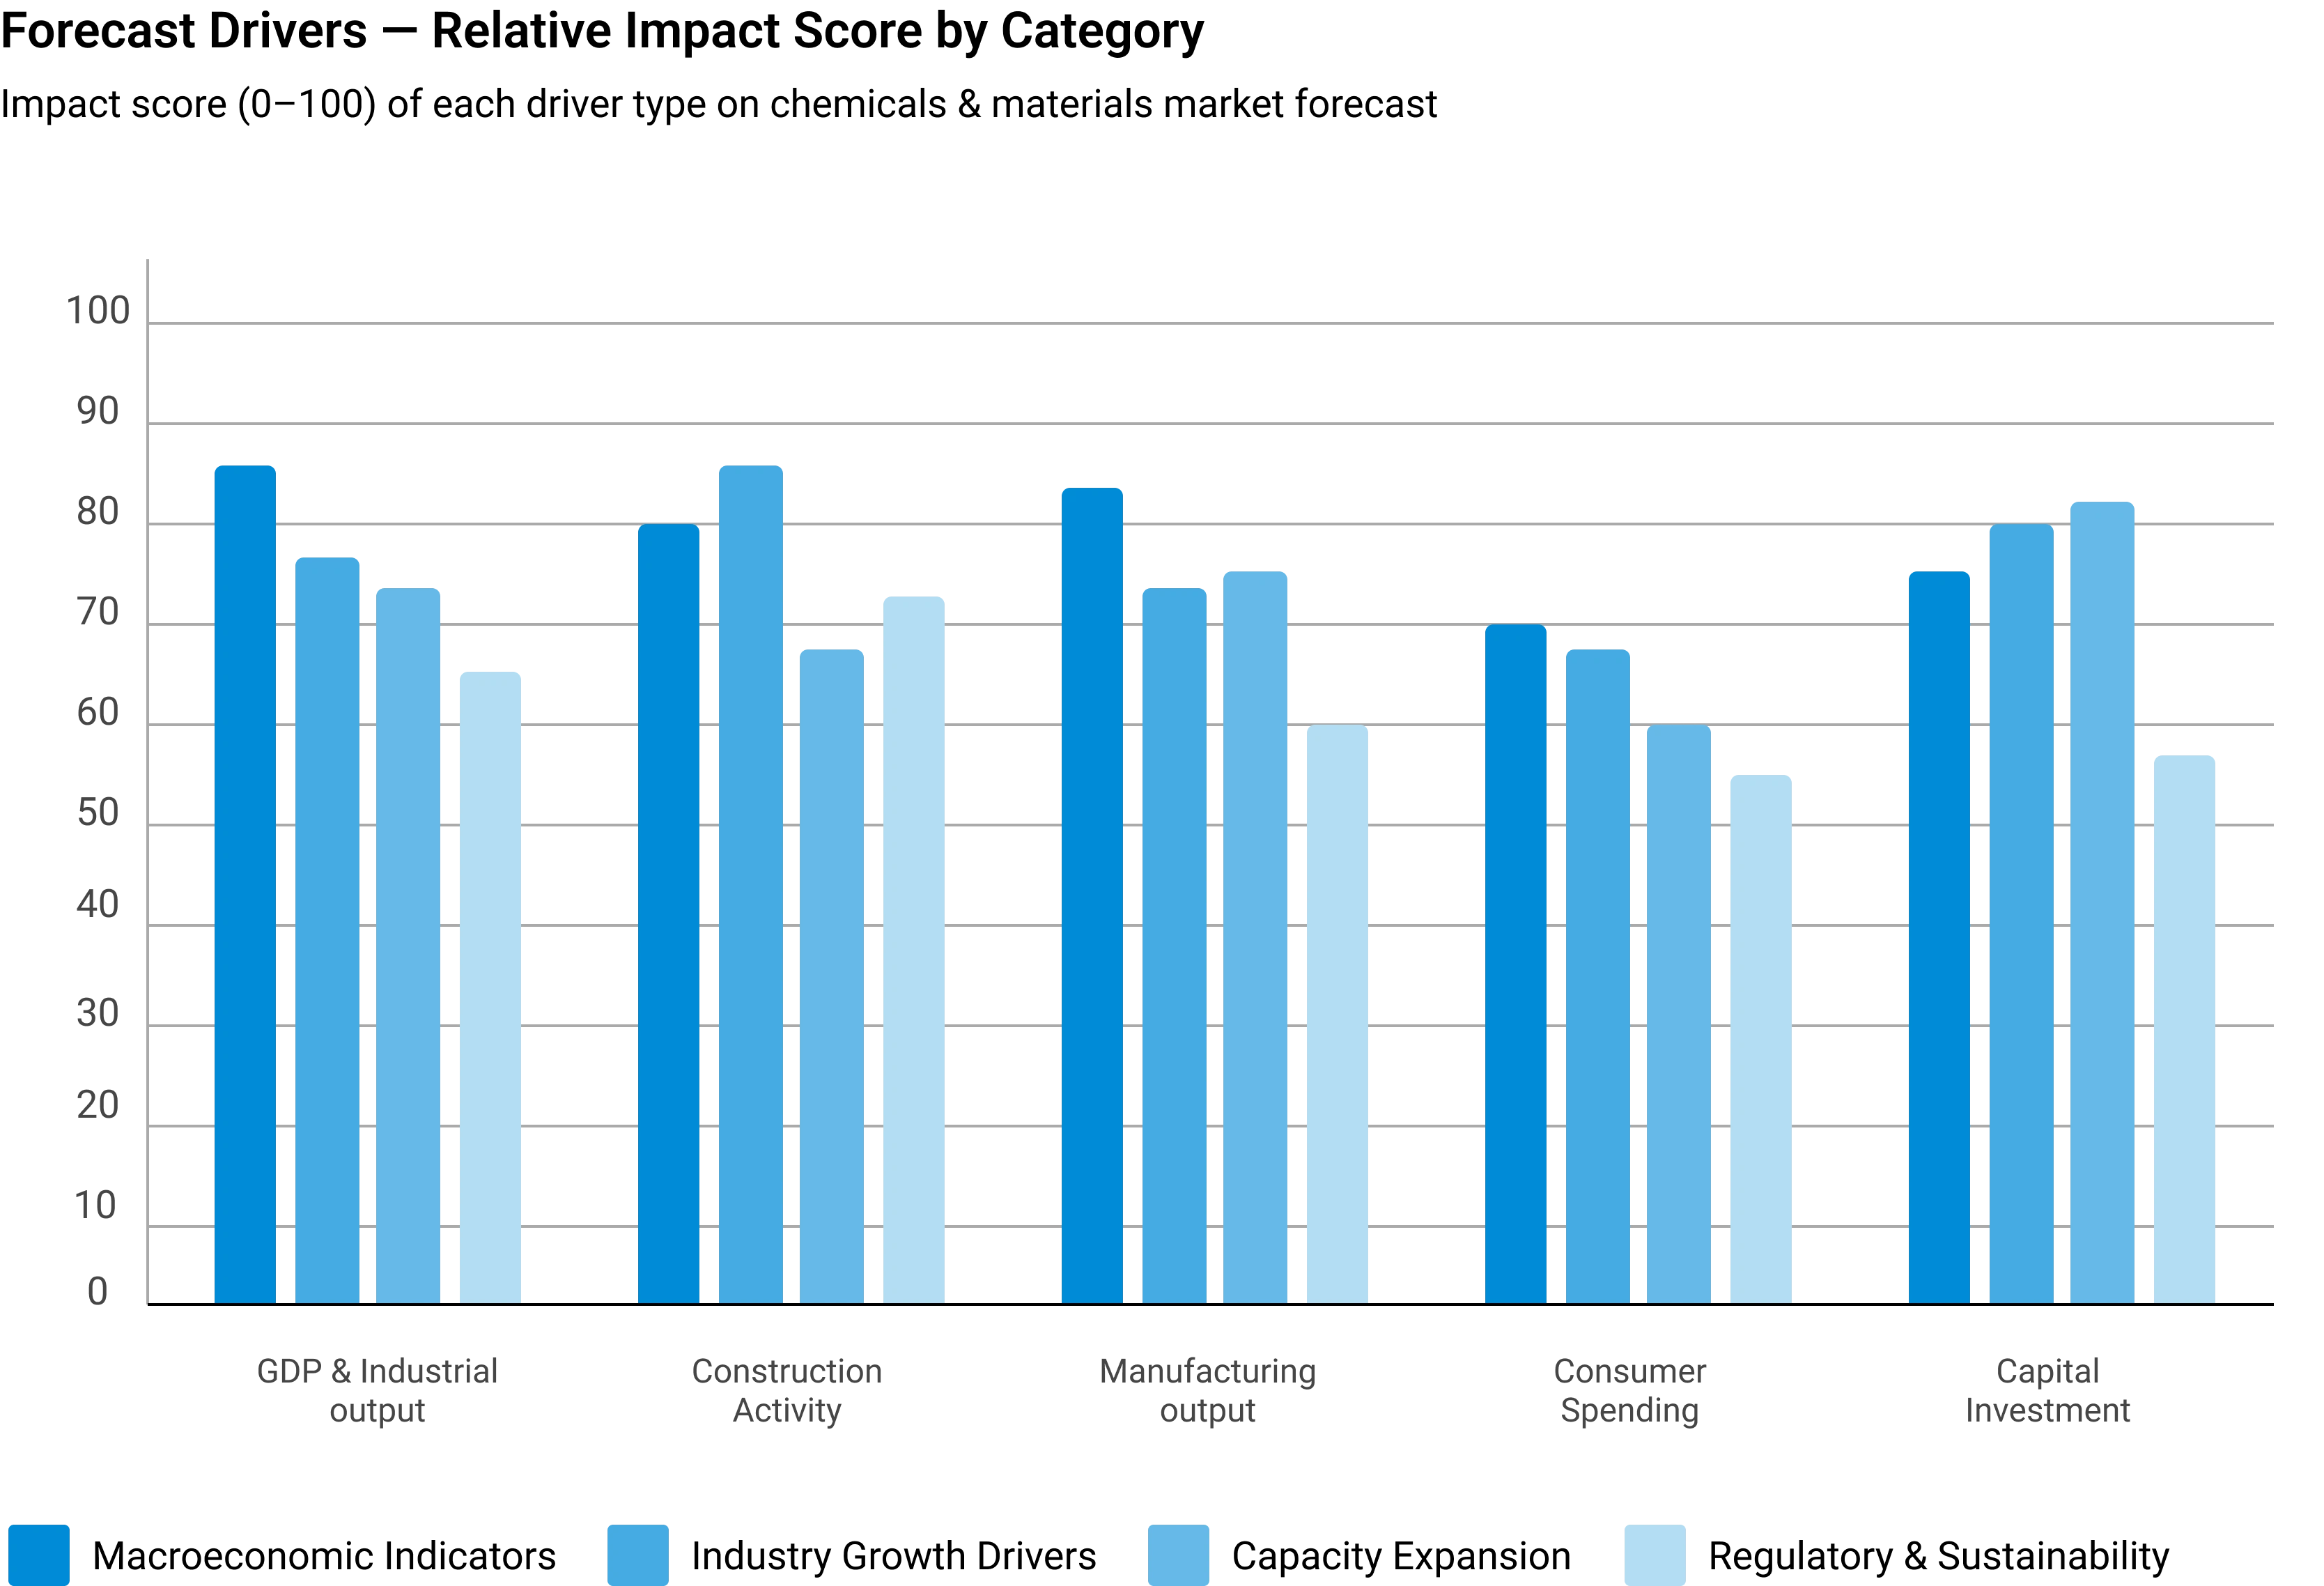
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
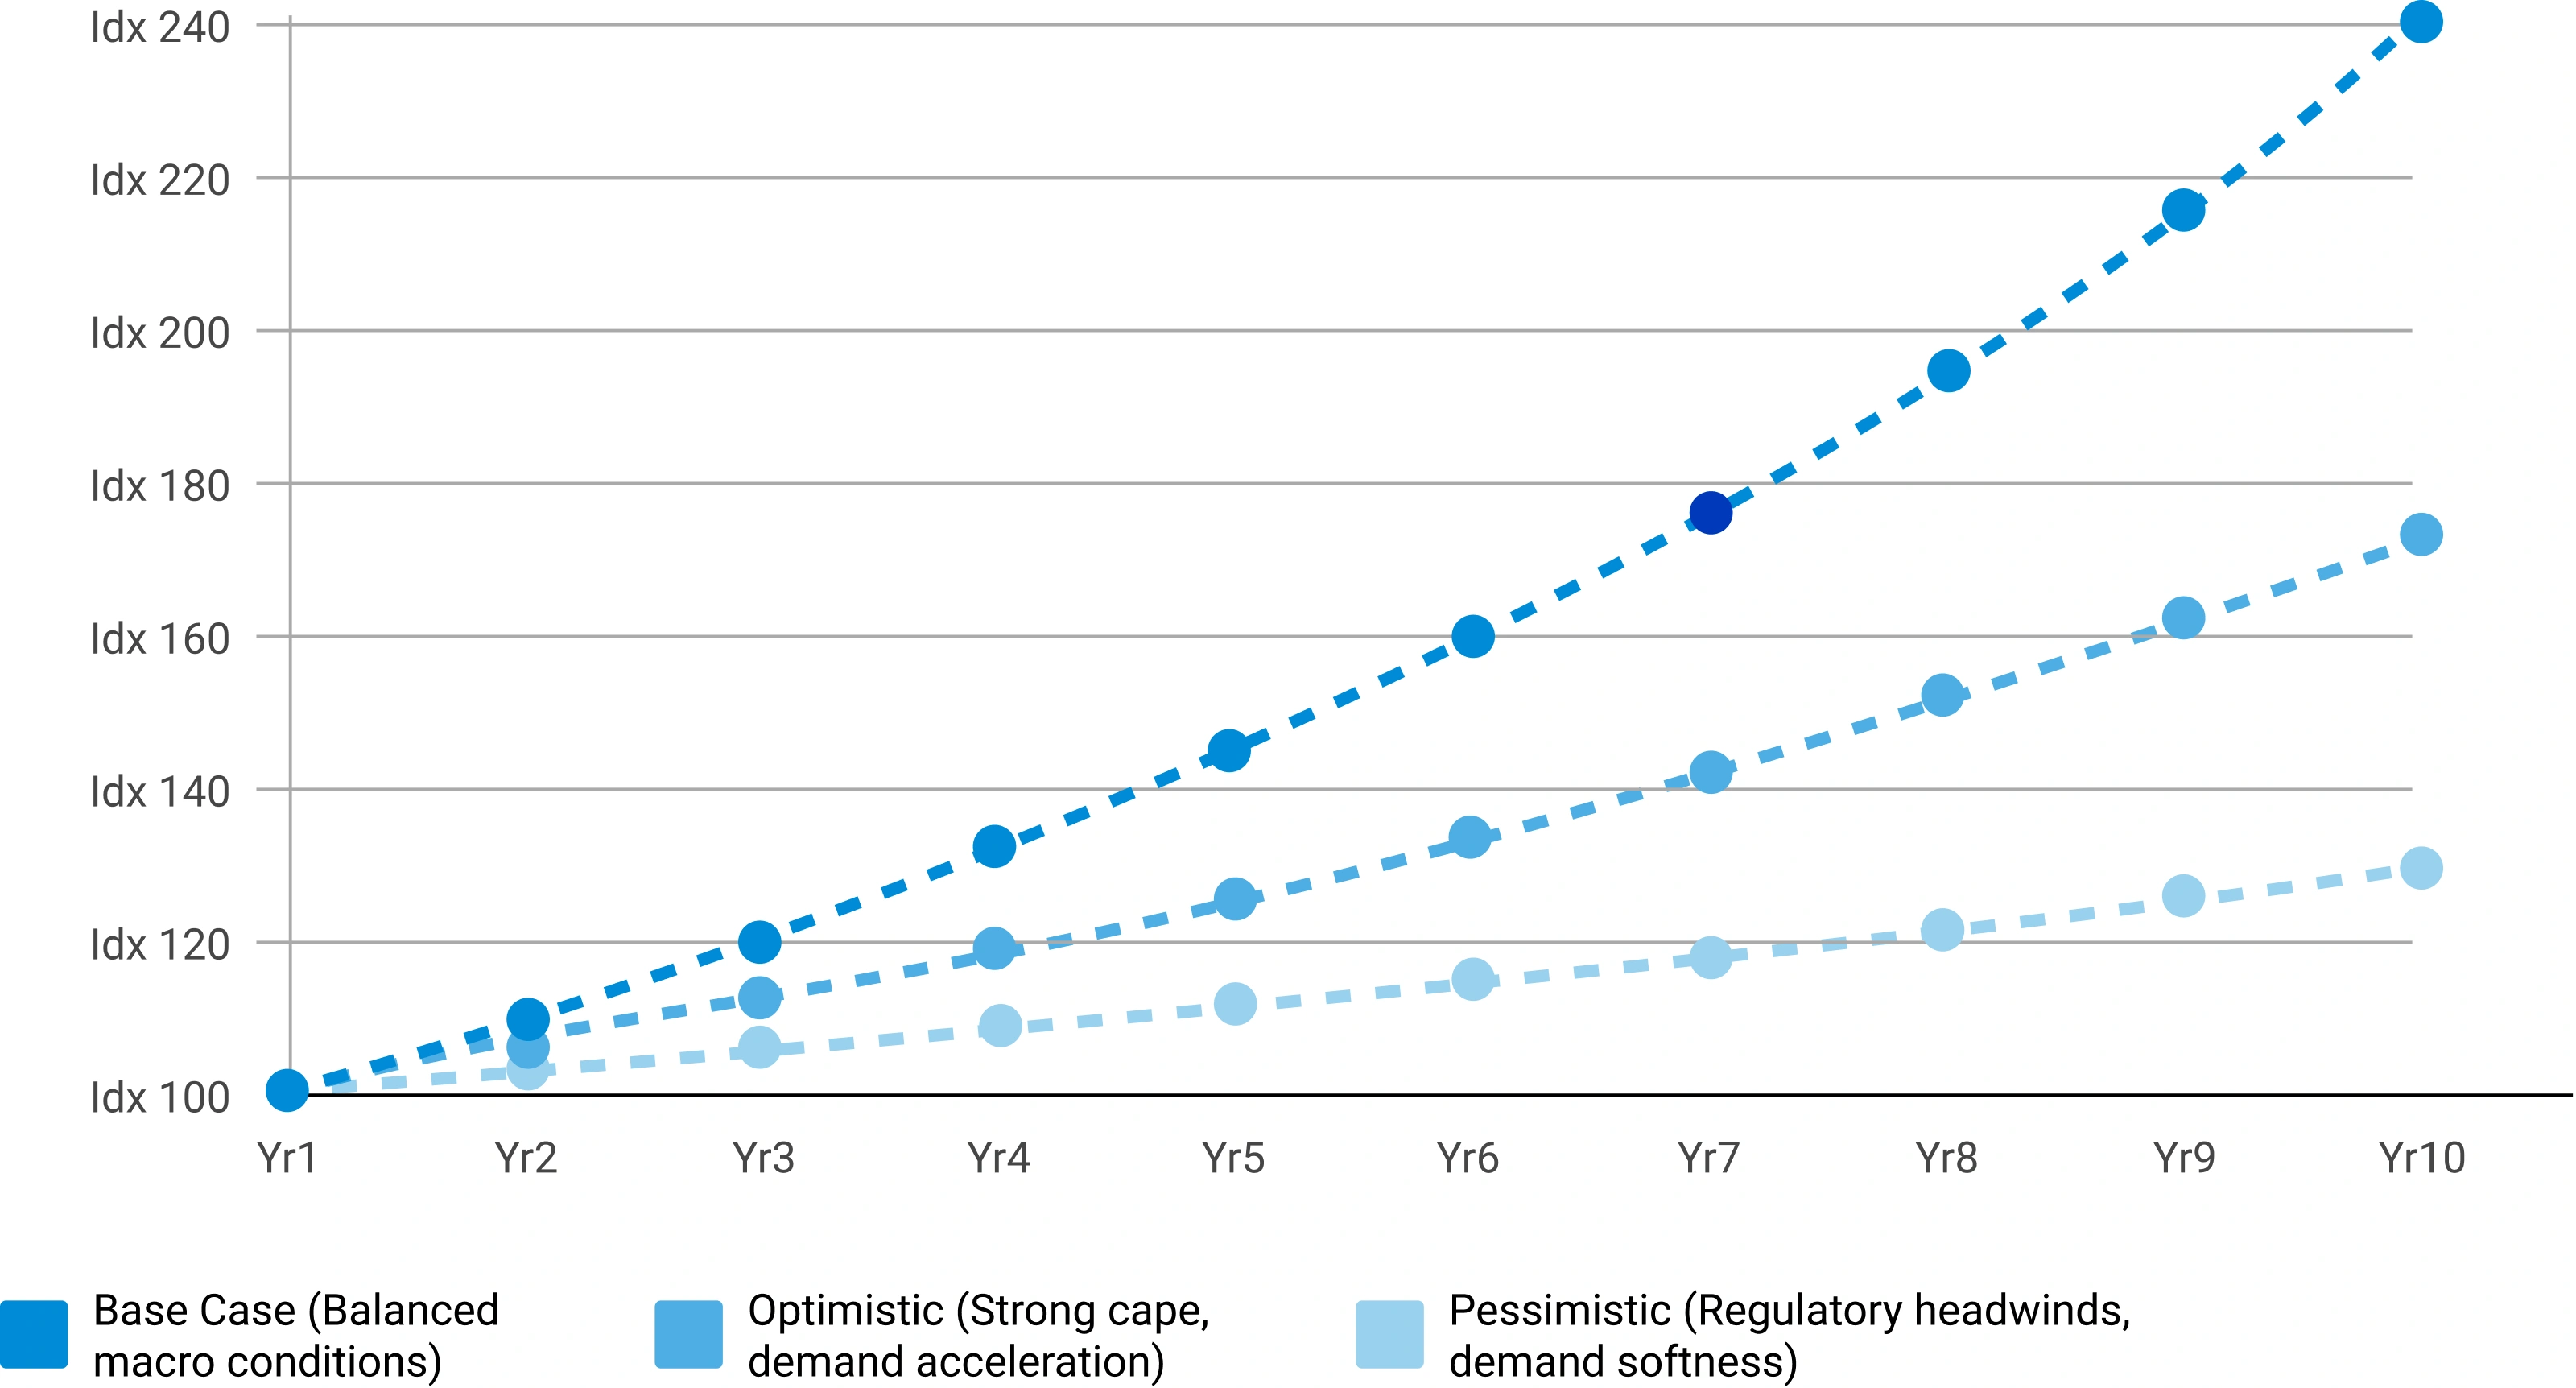
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon
Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast
Comments
Share your thoughts, ask a question, or provide feedback about this report.