Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The global bio-based polycarbonate market size was valued at USD 1.21billion in 2025, is estimated to reach USD 1.42 billion in 2026, and is projected to reach USD 5.79 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 16.95% over the forecast period from 2026 to 2035.Asia Pacific dominated the bio-based polycarbonate market with the largest revenue share of 42% in 2025 and is expected to grow at the fastest CAGR of 17.46% during the forecast period. The growth of the market is rapidly expanding due to strict environmental regulations, volatile fossil fuel prices, and growing consumer demand for sustainable products. Key companies such as Mitsui Chemicals & Mitsubishi Gas Chemical (MGC), Teijin & Mitsui Chemicals, play a major role as these collaborations help companies share the high costs of creating eco-friendly materials.
According to Towards Chemicals and Materials Analytics and Consulting, the global bio-based polycarbonate market volume was valued at 286.45 thousand tons in 2025 and is expected to surpass around 1,247.41 thousand tons by 2035, accelerating a compound annual growth rate (CAGR) of 15.85% over the forecast period from 2026 to 2035.

How is the Bio-Based Polycarbonate Market Playing a Vital Role in the Eco-Friendly Shift?
The bio-based polycarbonate market is a vital eco-friendly shift in the plastics industry. It replaces petroleum-based plastics with renewable plant materials like sugars and agricultural waste. This shift lowers greenhouse gases and reduces fossil fuel use, while keeping the high clarity and strength needed for cars and electronics. Traditional plastics are made from fossil fuels (like oil). Bio-based plastics use natural, renewable ingredients like plant sugars and vegetable oils. This lowers greenhouse gas emissions and pollution.
Regular polycarbonate is famous for being incredibly strong, light, and clear, like bulletproof glass or camera lenses. Bio-based versions match these exact traits. Governments across the globe enforce stricter regulations against traditional, polluting plastics. This pushes manufacturers to shift toward greener alternatives. Many countries now require companies to use recyclable or plant-based materials. This market lets businesses follow these rules without making weaker products. Leading companies like Covestro, Mitsubishi Chemical, and SABIC are investing heavily to make these materials cheaper and easier to get.
The market includes the manufacturing and sale of polycarbonate plastics extracted from renewable biomass feedstocks rather than conventional fossil fuels. Mainly, its an eco-friendly alternative to traditional petroleum-based polycarbonate, providing similar characteristics while decreasing dependence on non-renewable resources by lowering the overall carbon footprint. Bio-based polycarbonates are created from sources such as agricultural waste, sugars, and other biomass, which makes them a more preferred option. Government initiatives supporting green technologies are boosting market growth soon.
Governments across the globe are actively promoting the market through various initiatives, such as grants, funding for research and development, and tax incentives to support the adoption of sustainable materials and decrease dependence on fossil fuels. These measures impel companies to create and use bio-based alternatives to conventional plastics, especially in sectors such as healthcare, automotive, and electronics.
Policies such as Extended Producer Responsibility (EPR) regulations are increasingly being deployed to guide industries toward adopting circular economy principles. The initiatives encourage market players to take accountability for the end-of-life management of their products.
| Report Attributes | Details |
| Market Size in 2026 | USD 1.42 Billion |
| Market Size by 2035 | USD 5.79 Billion |
| Growth rate | CAGR 16.95% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Molecular Structure, By Product Form, By Application, Bio-Content Insight |
| Key Profiled Companies | Covestro AG, Teijin Limited, Mitsubishi Chemical Group, SABIC, Chimei Corporation, NatureWorks LLC, Avient Corporation, Trinseo, 3A Composites, Plazit Polygal, Novomer, BASF, Other Players |
Growing Demand in Electronics Products
Rising demand for polycarbonate in the electronics industry is the major driver creating lucrative opportunities in the market. In the electronics sector, they are rapidly being used in housing and components due to their durability and heat resistance properties. Furthermore, electronic devices generate more heat, and polycarbonates can bear these excess temperatures and heat without losing or deforming structural integrity. Also, their advanced optical clarity makes them convenient for applications necessitating light transmission or visibility.
The high production costs associated with bio-based polycarbonates are the major factor hindering the market growth. Bio-based polycarbonates are more costly to produce than conventional petroleum-derived polycarbonates. This is because of the complexities of deriving and refining bio-based raw materials along with the small-scale manufacturing facilities. Moreover, a lack of awareness and infrastructure development in emerging economies can hamper the market expansion further.
How did Asia Pacific Dominate the Bio-Based Polycarbonate Market in 2025?
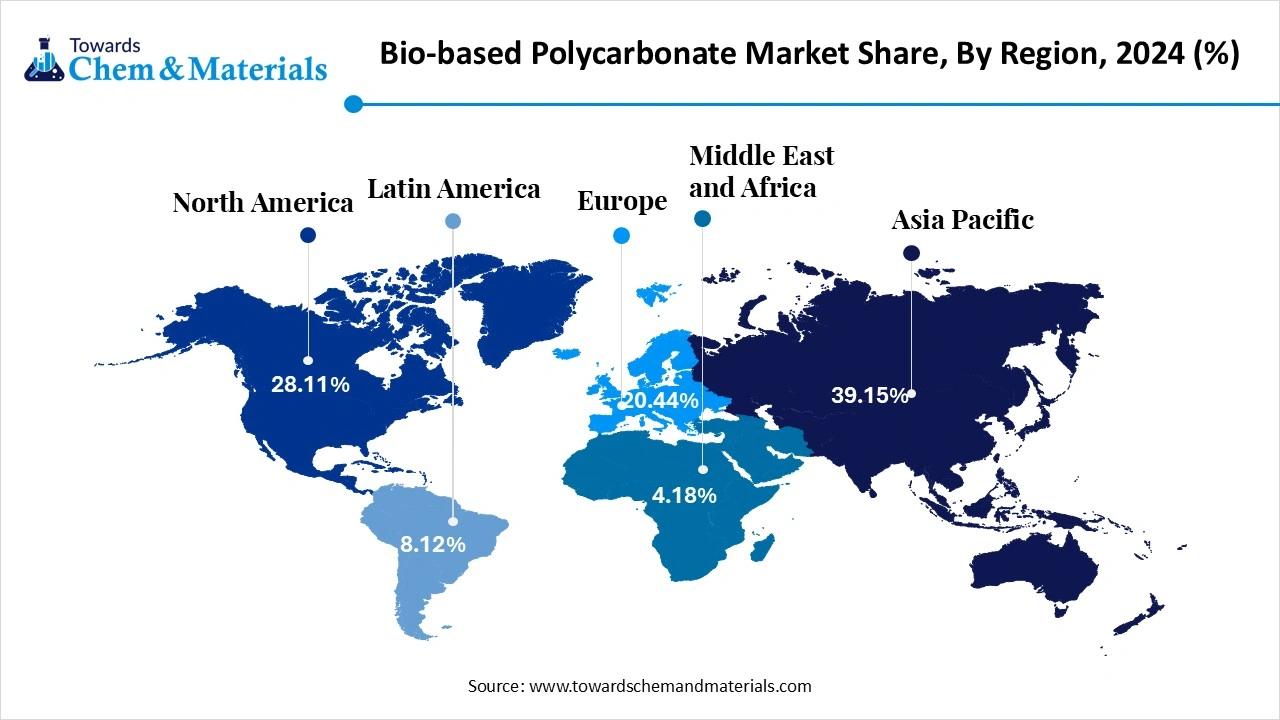
The Asia Pacific bio-based polycarbonate market size was estimated at USD 0.5 billion in 2025 and is projected to reach USD 2.5 billion by 2035, growing at a CAGR of 17.46% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 42% in 2025. The region achieved this lead through massive consumer electronics and automotive manufacturing, strict government sustainability rules, and large local production capacities. Countries like China, Japan, South Korea, and India are the worlds primary makers of smartphones, displays, and electric vehicles. These high-tech goods use large amounts of durable, lightweight plastic.

China
India
North America Bio-Based Polycarbonate Market Growth Factor
North America held a market share of 20% in 2025 and is expected to grow at the fastest CAGR of 18.80% over the forecast period, driven by strict government regulations, rising consumer demand for eco-friendly products, and corporate sustainability targets. Bio-based polycarbonate is a strong, clear plastic made from renewable plants (like corn or sugars) instead of fossil fuels. Many large brands and companies in the U.S. and Canada want to lower their carbon footprints. They are switching to bio-based plastics to meet strict internal eco-friendly targets. Governments are actively penalizing traditional petroleum-based plastics while supporting renewable materials.
United States
Canada
Europe Bio-Based Polycarbonate Market Growth Factor
Europe held a market share of 27% in 2025, driven by strict environmental regulations, the push for circular economies, and high consumer demand for eco-friendly products. Key applications span the automotive, electronics, packaging, and optical industries. Europe’s leading automakers use bio-based polycarbonate to make vehicles lighter. This increases fuel efficiency and lowers emissions without sacrificing safety or durability. The European Union (EU) pushes for carbon footprint reduction and circularity. Policies like the EU Digital Product Passports mandate the use of renewable materials and recycled-content quotas.
Germany
France
Latin America Bio-Based Polycarbonate Market Growth Factor
Latin America held a market share of 6% in 2025. Growth is driven by strict environmental regulations, the shift to sustainable automotive materials, consumer demand for eco-friendly electronics, and the need for energy-efficient building materials. Governments are banning single-use plastics and promoting circular economies, pushing brands toward renewable materials. Demand for energy-efficient glazing and roofing in Brazil and Argentina accounts for the largest share of regional consumption. Bio-based polycarbonates meet strict regional eco-standards for these materials.
Brazil
Argentina
Middle East & Africa Bio-Based Polycarbonate Market Growth Factor
The Middle East & Africa held a market share of 5% in 2025, growing due to rising green building construction, expanding automotive manufacturing, and government sustainability initiatives. Governments are investing heavily in green building projects. Bio-based plastics are used in roofs and windows because they are strong and lightweight. Strict government regulations in regions like the Gulf Cooperation Council (GCC) push for eco-friendly building standards and reduced dependence on finite fossil fuels.
Saudi Arabia
UAE
The aromatic bio-polycarbonate segment dominated the market in 2024. The dominance of the segment can be attributed to the growing demand for sustainable materials and strict environmental regulations. These polycarbonates give better performance than the conventional polycarbonate while minimizing dependence on fossil fuels. Aromatic bio-polycarbonates are extracted from sources such as CO2-based polymers, biomass, and plant-based isosorbide.

The aromatic-aliphatic copolymers segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be credited to the superior properties of these copolymers than the traditional ones. These copolymers integrate the heat resistance and strength of aromatic components with the biodegradability and flexibility of aliphatic components, which makes them convenient for an extensive range of applications.
The resins segment dominated the market in 2024. The dominance of the segment can be driven by ongoing technological advancements and surging environmental awareness across the globe. Bio-based polycarbonates have a lesser carbon footprint as compared to their traditional counterparts, which aligns he global efforts to minimize greenhouse gas emissions. There is also a growing focus on combining renewable feedstocks in bio-based PC production, driving segment growth shortly.

The blended compounds segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be linked to the growing demand for eco-friendly alternatives to conventional petroleum-based polycarbonates. These blends integrate bio-based polycarbonate with some other materials to improve specific properties such as thermal stability and impact resistance. Blended compounds are used in an extensive range of sectors.
The consumer electronic segment held the largest market share in 2024. The dominance of the segment is owing to the stringent regulations, growing environmental awareness, and the development of sustainable and high-performance materials. Also, governments across the globe are deploying stringent regulations on the use of sustainable materials and plastic waste. This obligation impels companies to adopt bio-based options such as polycarbonate.
The packaging segment is expected to grow at the fastest CAGR during the projected period. The growth of the segment is due to its exceptional durability, barrier properties, and optical clarity. The growing consumer inclinations towards sustainable packaging solutions and the need for minimizing plastic waste are substantial factors fuelling this trend. Bio-based polycarbonates can offer sturdy and clear packaging solutions.
The partially bio-based segment led the market in 2024. The dominance of the segment can be attributed to the innovations in bio-based polymer technology, growing environmental awareness along supportive government regulations. In addition, growing applications in electronics, automotive, and medical industries coupled with cost competitiveness are also impactive positive segment growth further.
The fully biobased segment is expected to grow at the fastest CAGR over the studied period. The growth of the segment can be linked to the ongoing strategic collaborations supporting commercialization, innovations in polymerization technologies, and better performance of bio-based options. Furthermore, advancements in biotechnology like enzyme engineering, fermentation technology, and genetic modification have optimized the cost-effective production of fully biobased materials and chemicals.
By Molecular Structure
By Product Form
By Application
By Bio-Content
By Region
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo