
Asia Pacific Water Treatment Chemicals Market Size and Forecast 2026 to 2035
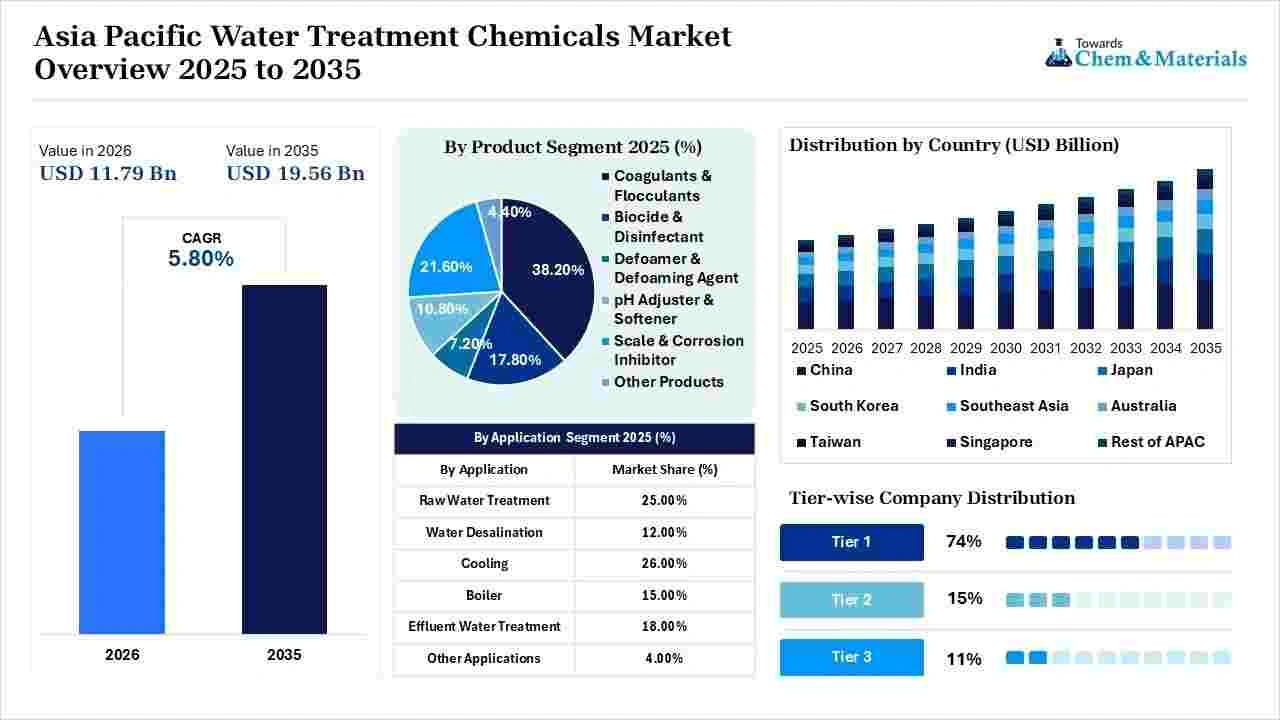
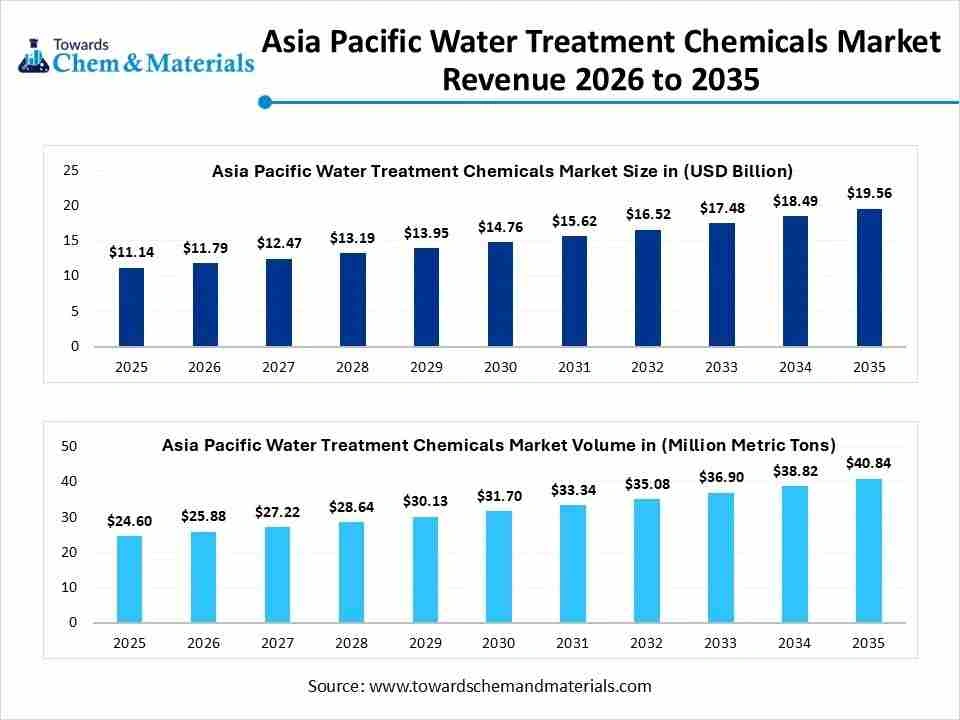
The Asia Pacific Water Treatment Chemicals market size was valued at USD 11.14 billion in 2025, is estimated to reach USD 11.79 billion in 2026, and is projected to reach USD 19.56 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.80% over the forecast period from 2026 to 2035.Rapid urbanisation, industrialisation, municipal infrastructure development, and more stringent requirements for discharges of wastewater result in growth. Smart dosing, IoT integration, water reuse, zero-liquid-discharge systems, artificial intelligence, and bio-based chemistry are changing the landscape of treatment operations throughout regional facilities. The regional market growth is further accelerated by specific treatment chemical and advanced water-management solution needs from power generation, manufacturing, electronics, mining, municipal wastewater, and cooling applications.
Market Highlights
- China dominated the Asia Pacific Water Treatment Chemicals market by holding a 31.2% share in 2025 and is expected to grow at a CAGR of 7.1% during the forecast period.
- India held 16% market share in 2025 and is expected to grow at the fastest rate with a CAGR of 7.7% during the forecast period.
- By product, the coagulants & flocculants segment dominated the market with the largest share of 38.2% in 2025 and is expected to grow at a CAGR of 5.9% during the forecast period.
- By product, the scale & corrosion inhibitor segment held 21.6% market share in 2025 and is expected to grow at the fastest CAGR of 6.8% over the forecast period.
- By application, the raw water treatment segment dominated the market with the largest share of 25% in 2025 and is expected to grow at a CAGR of 5.4% during the forecast period.
- By application, the cooling segment held 26% market share in 2025 and is expected to grow at the fastest CAGR of 6.9% over the forecast period.
- By source, the synthetic segment dominated the market with the largest share of 80% in 2025 and is expected to grow at a CAGR of 5.5% during the forecast period.
- By source, the bio-based segment held 20% market share in 2025 and is expected to grow at the fastest CAGR of 8.6% over the forecast period.
- By end-use, the power segment dominated the market with the largest share of 22% in 2025 and is expected to grow at a CAGR of 5.5% during the forecast period.
- By end-use, the municipal segment held 21% market share in 2025 and is expected to grow at the fastest CAGR of 6.6% over the forecast period.
According to Towards Chemicals and Materials Analytics and Consulting, the Asia Pacific Water & Wastewater Treatment Chemicals Market volume was valued at 24.60 million metric tons in 2025 and is expected to surpass around 40.84 million metric tons by 2035, accelerating a compound annual growth rate (CAGR) of 5.20% over the forecast period from 2026 to 2035.
Market Overview
Rapid growth of the Asia Pacific market is driven by the need for municipal and industrial treatment due to urbanization and industrialization. China, India, and Japan continue to be significant demand centers in the region, fed by manufacturing, power generation, mining, and wastewater infrastructure. Advanced treatment systems and chemical optimization are also being promoted by increasingly stringent government regulations on wastewater discharge. Purchasing decisions at industrial facilities today are more and more affected by smart monitoring, water reuse, and zero-liquid-discharge systems. The increased developments are expected to drive the widespread use of coagulants, flocculants, inhibitors, biocides, disinfectants, pH adjusters, and special applications in Asia Pacific.
Global Investment Movement for the Asia Pacific Water Treatment Chemicals Market
- Regulations for protecting the environment and Zero Liquid Discharge (ZLD) are prompting factories to improve chemical dosing systems.
- Compliance, efficient wastewater treatment, and reduced discharge are now the focus of these investments in industrial facilities across Asia Pacific.
- Demand for specialty treatment chemicals that are customized for specific processes is growing due to growth in power generation, textiles, manufacturing, and semiconductor production.
- Corrosion inhibitors, scale inhibitors, and formulations addressing complex industrial water needs are increasingly under focus in investments.
- Regional governments are in ongoing development of sewage treatment facilities, improving the consumption demand for coagulants and flocculants.
- Municipal investment consequently helps to maintain steady chemical demand, and increases the capacity of treatment in fast-growing population areas.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 11.79 Billion/ 25.88 Million Metric Tons |
| Expected Size in 2035 | USD 19.56 Billion/ 40.84 Million Metric Tons |
| Growth Rate | CAGR of 5.80% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Segment Covered | By Product, By Application, By Source, By End Use Industry |
| Key Companies Profiled | Ecolab (Nalco Water), Kemira, Kurita Water Industries, Solenis, Suez, Veolia, BASF, Dow, SNF Group, Solvay |
Recent Market Trends
- To reduce the use of chemicals, facilities are more commonly implementing automated monitoring and smart dosing systems. These systems can enable treatment adjustments in real time and still lower operating costs in ever-more complex industrial water management situations.
- Wastewater recycling and Zero Liquid Discharge (ZLD) are gaining greater importance in manufacturing facilities. The solutions address water scarcity and enable increased water re-use in industrial production systems across Asia Pacific.
- China, India and Vietnam still have stricter regulations on industrial effluent disposal. Stiffer requirements stimulate facilities to use more sophisticated chemicals and wastewater treatment systems.
- Manufacturers are more inclined to adopt sustainable formulations that provide effective treatment while minimising environmental impacts. In addition to traditional treatment solutions, bio-based polymers, biodegradable formulations and phosphate-free chemistries are becoming part of the spotlight.
Key Technological Shifts and AI in the Asia Pacific Water Treatment Chemicals Market
The water treatment chemicals market in Asia Pacific is gaining greater traction with the use of AI, IoT, automation, and real-time monitoring solutions. The technologies enable precise chemical dosing and enhance the visibility of the process throughout the entire treatment facility. Advanced antiscalants and corrosion inhibitors are also in greater demand for power, semiconductor, and data-center applications, thanks to the closed-loop recycling systems. Environmental requirements promote green chemistry, biodegradable polymers, and phosphate-free formulations. Analysing the pattern of pump failures, chemical levels, and membrane fouling as well as forecasting future failures, AI-based predictive maintenance helps to detect potential issues earlier.
Supply Chain Analysis of the Asia Pacific Water Treatment Chemicals Market
Feedstock Procurement
- The Feedstock procurement activity includes sourcing basic inorganics, polymers, and petroleum derivatives from local and international suppliers.
- A consistent supply of reliable feedstocks allows us to maintain consistent production, formulation quality, and continuity of water treatment chemicals.
- Dow buys raw materials in the base chemical and hydrocarbon categories from well-established supply chains in Asia Pacific.
- Other Key Players: BASF SE, Solvay, Nouryon
Production of Chemicals and Processing
- Chemical synthesis is a process of transforming raw feedstocks by a specific reaction into functional ingredients, such as coagulants, biocides, and polymers.
- Processing efficiency determines the chemical quality, performance, consistency, and suitability for municipal and industrial water treatment systems.
- Kemira: Aluminum-based coagulants and Specialty Polymers are synthesized at the Kemira major plant for the needs of the regions municipalities and pulp and paper production.
- Other Key Players: Dow, BASF SE, Solvay
Compound Formulation and Blending
- Formulation and blending involve mixing active ingredients with stabilizers, solvents, and dispersants to create specific treatment formulations.
- Formulations for specific water quality, scaling, corrosion, and industrial process needs enhance treatment performance.
- Ecolabs Nalco Water division supplies its industrial treatment applications with customized antiscalants and corrosion inhibitors.
- Other Key Players: Solenis, Kurita Water Industries Ltd., SNF
Sustainability Analysis
Promote Sustainable Chemistry and Circular Water Management
The selection of chemicals is now increasingly a concern for water-scarce treatment facilities and facilities under increasingly challenging environmental conditions in Asia Pacific. Coagulants, bio-based flocculants, biodegradable polymers, and phosphate-free formulations are being developed by manufacturers to be environmentally friendly. Chemical dosing optimization is increasingly paired with digital monitoring at the facilities to minimize sludge production and overall water footprints. ZLD strategies promote water reuse and recycling within industrial processes. Even so, there are still concerns about the aquatic toxicity and environmental effects of conventional synthetic polymers and phosphonate-based chemicals.
What are Water Treatment Chemicals?
Water treatment chemicals are chemicals utilized to treat municipal water, industrial wastewater, and safeguard infrastructure. They are used in the form of coagulants, flocculants, disinfectants, inhibitors, pH adjusters, softeners, and specialty formulations. They help facilitate treatment efficiency, water reuse, equipment protection, and environmental compliance in regional applications.
Uses of Asia Pacific Water Treatment Chemicals
- Contaminants settle efficiently when coagulants and flocculants are used to group particles together. This can help to keep the municipal and industrial water cleaner, and enhance the filtering ability of the water downstream.
- Chlorine, sodium hypochlorite, and hydrogen peroxide are disinfectants that kill harmful microorganisms. Their use helps to ensure clean water and sanitation in public water systems.
- All specialized inhibitors are used to prevent mineral deposits and corrosion in pipes, boilers, cooling towers, and reverse osmosis membranes. These chemicals not only promote equipment reliability in harsh industrial treatment situations, but they also enhance productivity.
- Acids and alkalis adjust the acidity of water and aid in treatment reactions. Maintaining optimum pH eliminates corrosion problems and enhances chemical treatment efficiency downstream at sites.
Pricing Analysis for the Asia Pacific Water Treatment Chemicals Market
The price is dependent on the complexity of the product, the cost of raw materials, formulation needs, competitive pressures, and pressures for environmental compliance. In general, commodity coagulants have low pricing levels, performance polymers are in the middle range, and specialty polymers are at the high end. Specialty formulations are higher priced due to their specialized functional requirements. Volatility of raw materials affects production costs, and a competitive regional market impacts commodity prices and drives value-added differentiation.
Asia Pacific Water Treatment Chemicals Market: Global Trade Analysis
Asia Pacific is still a key market for water treatment chemicals in the global market. There is significant intra-regional trade in commodity chemicals as well as significant demand in China, India, and Japan. The Chinese export bulk products, the Japanese and South Koreans export specialized formulations of products, and the ultrapure-water products treatment additives. Access to specialised polymers and chem-feedstocks is also enabled through imports.
Segmental Insights
Product Insights
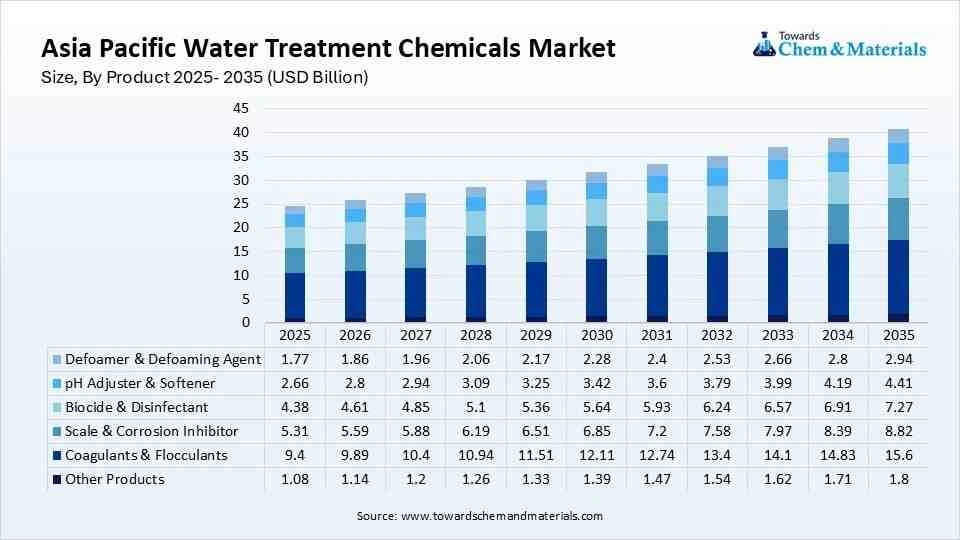
The coagulants & flocculants segment dominated the market with the largest share of 38.2% in 2025 and is expected to grow at a CAGR of 5.9% over the forecast period. The broad use of these throughout municipal drinking-water treatment, industrial wastewater clarification, and pretreatment will sustain demand. The importance of these increases is further enhanced in the rapidly urbanizing areas where treatment requirements are increasing.
- For instance, in January 2025, HAMANN AG introduced a proprietary flocculant "BlueFloc" for flotation sewage treatment plants. The solution helps customers lower operating costs while offering greater plant reliability and lower maintenance needs.(Source: www.yachting-pages.com)
The scale & corrosion inhibitor segment held the 21.6% market share in 2025 and is expected to grow at the fastest CAGR of 6.8% over the forecast period, due to rising emphasis on equipment protection and water re-use in industrial facilities. These chemicals prevent mineral deposits, corrosion, and operational deterioration in cooling towers, boilers, pipes, and reverse osmosis membranes. Adoption grows throughout Asia Pacific, as industrial growth and treatment demand grow.
Asia Pacific Water Treatment Chemicals Market Share, By Product, 2025(%)
| By Product | Market Share (%) |
| Coagulants & Flocculants | 38.20% |
| Biocide & Disinfectant | 17.80% |
| Defoamer & Defoaming Agent | 7.20% |
| pH Adjuster & Softener | 10.80% |
| Scale & Corrosion Inhibitor | 21.60% |
| Other Products | 4.40% |
Application Insights
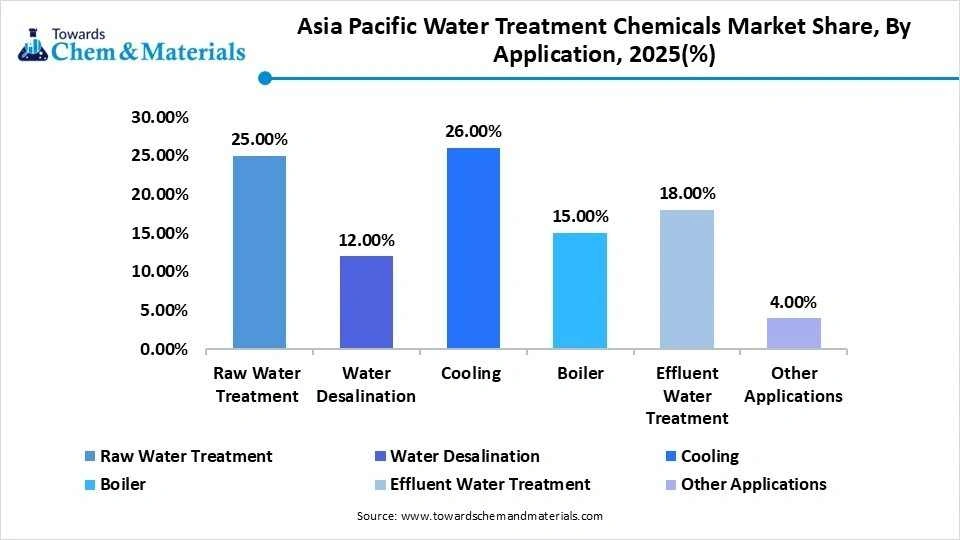
The raw water treatment segment dominated the market with the largest share of 25% in 2025 and is expected to grow at a CAGR of 5.4% over the forecast period, as most municipal and industrial facilities need to be effectively clarified before downstream treatment processes. Coagulants and flocculants help to remove suspended particles and enhance subsequent filtration efficiency. The urbanization rate, increasing urban infrastructure, and industrial water demand continue to fuel the demand for raw water treatment solutions in Asia Pacific.
- For instance, in June 2026, JCI Cebu and JCI Japan launched a project called “Bohe Maka Sannang,” providing safe drinking water to communities using Japanese filtration technology and ultraviolet sterilization. (Source: www.sunstar.com)
The cooling segment held a 26% market share in 2025 and is expected to grow at the fastest CAGR of 6.9% over the forecast period, as the manufacturing, power generation, and other industrial processes demand cooling-water solutions that are reliable. Treatment chemicals are effective in preventing scaling, corrosion, and biological growth in cooling systems. Growth in industrial activity and a focus on operational efficiency are helping to drive wider use of specialized cooling-water treatment chemicals at regional sites.
Asia Pacific Water Treatment Chemicals Market Share, By Application, 2025(%)
| By Application | Market Share (%) |
| Raw Water Treatment | 25.00% |
| Water Desalination | 12.00% |
| Cooling | 26.00% |
| Boiler | 15.00% |
| Effluent Water Treatment | 18.00% |
| Other Applications | 4.00% |
Source Insights
The synthetic segment dominated the market with the largest share of 80% in 2025 and is expected to grow at a CAGR of 5.5% over the forecast period, as synthetic polymers, biocides, corrosion inhibitors, and chemicals derived from petroleum products continue to be prevalent across industrial treatment processes. They can be used for a variety of functions, including clarification, disinfection, corrosion control, and deposit management. The long-term production capacities and wide application acceptance ensure high demand in Asia Pacific.
The bio-based segment held a 20% market share in 2025 and is expected to grow at the fastest CAGR of 8.6% over the forecast period. The bio-based component is growing with the increasing interest of manufacturers and treatment operators in finding sustainable alternatives in response to environmental concerns. Environmental impacts can be lowered by using bio-based polymers, natural coagulants, enzyme-based chemicals, and plant-based treatment agents. Regulatory requirements and sustainability goals are still driving adoption in regional water treatment applications.
Asia Pacific Water Treatment Chemicals Market Share, By Source, 2025(%)
| By Source | Market Share (%) |
| Synthetic | 80.00% |
| Bio-based | 20.00% |
End-Use Insights
The power segment dominated the market with the largest share of 22% in 2025 and is expected to grow at a CAGR of 5.5% over the forecast period. The power segment leads the way as thermal, hydropower, nuclear, and renewable power need to manage water across a variety of operating processes. Treatment chemicals are used as a part of cooling systems, boiler-feed water, steam generation, and condensate treatment. Increasing electrical energy demand and the development of electrical power systems are still driving continued demand for specialty water treatment chemicals.
- For instance, in August 2025, the water supply company in Fukuoka city began to operate an osmotic power plant for desalination. The plant has a growing degree of integration between its water treatment facilities and technically innovative power-generation systems. (Source: globalenergyprize.org)
The municipal segment held a 21% market share in 2025 and is expected to grow at the fastest CAGR of 6.6% over the forecast period. Cities need to invest in the development of improved drinking-water treatment, wastewater management, and water reuse infrastructure, which is driving rapid expansion of the municipal segment. Municipalities are also motivated to increase their treatment capacity due to more stringent environmental standards. As urbanisation and the need to manage water on a circular basis continue to rise, the use of treatment chemicals is expanding in regional municipal treatment facilities.
- For instance, in February 2026, SUEZ and PYREG installed Pyrolis® S2B, a system that transforms sewage sludge into biochar and facilitates sustainable carbon sequestration and circular economy practices and wastewater management. (Source: www.chemengonline.com)
Asia Pacific Water Treatment Chemicals Market Share, By End Use Industry, 2025(%)
| By End Use Industry | Market Share (%) |
| Power | 22.00% |
| Oil & Gas | 14.00% |
| Chemical Manufacturing | 13.00% |
| Mining & Mineral Processing | 10.00% |
| Municipal | 21.00% |
| Food & Beverage | 7.00% |
| Pulp & Paper | 5.00% |
| Other End Uses | 8.00% |
Regional Insights
How Did China Dominate the Asia Pacific Water Treatment Chemicals Market In 2025?
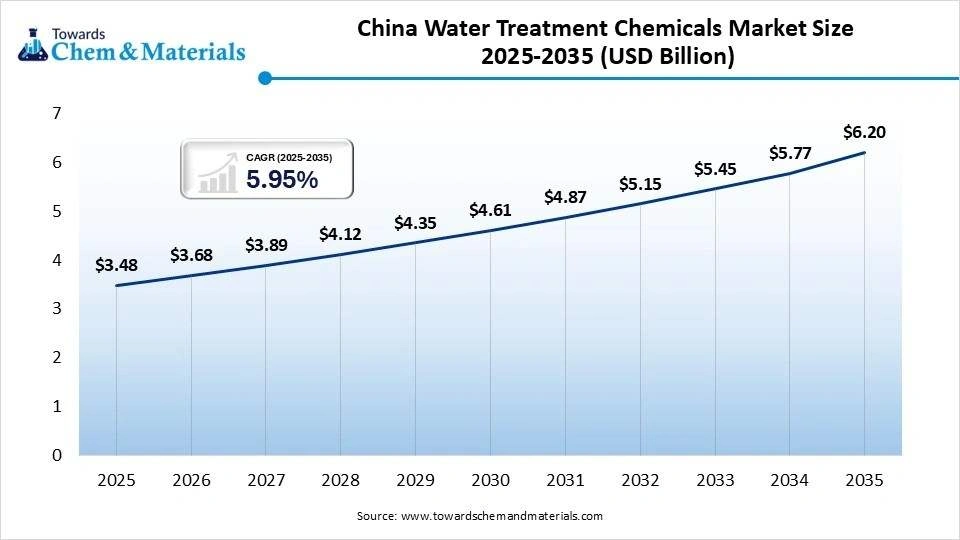
The China water treatment chemicals market size was estimated at USD 3.48 billion in 2025 and is projected to reach USD 6.20 billion by 2035, growing at a CAGR of 5.95% from 2026 to 2035. China dominated the market with the largest share of 31.2% in 2025, China continues to be the biggest country in the Asia Pacific water treatment chemicals market, spearheaded by strong industrialization and growth in municipal infrastructure. The significant treatment demands from manufacturing, power generation, wastewater treatment, and urban development persist. Stiffer environmental regulations are helping facilities enhance their wastewater and chemical treatment.
- For instance, in June 2026, a central sewage -treatment plan in Ulan Bator was constructed with Chinas help. The purpose of the facility is to enhance water quality and environmental conditions in the local area. (Source: www.globaltimes.cn )
India
India water treatment chemicals market size was estimated at USD 1.78 billion in 2025 and is projected to reach USD 3.23 billion by 2035, growing at a CAGR of 6.14% from 2026 to 2035. India held 16% market share in 2025 and is expected to grow at the fastest CAGR of 7.7% during the forecast period, due to the rising demand for treatment driven by industrialization, urbanization, and environmental needs, which is making India one of the fastest-growing country markets. Increasing consumption is enabled by manufacturing, municipal wastewater management, water recycling, and Zero Liquid Discharge applications. The development of membranes and other water-management technologies at home is also boosting Indias capabilities in advanced water-management applications.
- For instance, in April 20256, Vipul Organics Limited started commercialization of indigenously developed membranes under the trade name AdiMem Technologies. The company is producing reverse osmosis and ultrafiltration membranes in Gujarat.(Source: www.indianchemicalnews.com)
Japan
The Japan water treatment chemicals market size was estimated at USD 1.68 billion in 2025 and is projected to reach USD 3.05 billion by 2035, growing at a CAGR of 6.14% from 2026 to 2035.The Japan held 15.1% market share in 2025 and is expected to grow at a CAGR of 6.1% over the forecast period. Japan holds a significant role in the region through its state-of-the-art water treatment technologies and highly developed water applications in industry. Existing infrastructure in the country can meet the needs of municipal treatment facilities, industrial wastewater, desalination, and ultrapure water treatment. Specialised treatment technologies are also supplied by Japanese companies in regional markets.
South Korea
The South Korea water treatment chemicals market size was estimated at USD 1.10billion in 2025 and is projected to reach USD 1.95 billion by 2035, growing at a CAGR of 5.89% from 2026 to 2035. South Korea held 9.9% market share in 2025 and is expected to grow at a CAGR of 6.3% over the forecast period. The South Korean market is significant in the region and has developed high-level manufacturing and industrial production systems. Reliable water treatment and process water management are required for electronics and other high-value industries. There is a growing focus on water reuse, industrial wastewater treatment, and the importance of high-quality water, providing opportunities for specialized chemicals and advanced treatment technologies. Industrial development is thus ongoing to continue promoting market growth.
Australia
Australia held 6.3% market share in 2025 and is expected to grow at a CAGR of 5.9% over the forecast period. The rise in the focus on water conservation, recycling, and efficient filtration is a positive trend for the water treatment chemicals market in Australia. High-capacity filtration solutions are also in demand for horticulture and fresh-produce processing. Investment in new water treatment and reuse projects is ongoing, driven by sustainability goals and needs for resource efficiency.
- For instance, in May 2026, Wyma Solutions released the Micron Filter XL for the horticultural market. The solution facilitates water re-use, waste reduction, and optimizes wash-line performance in fresh produce processing applications.(Source: www.potatopro.com)
Competitive Analysis
The Asia Pacific Water Treatment Chemicals Market is competitive, as companies pursue multiple innovations, acquisitions, digitalization, and specialisation in treatment products. With increasingly sustainable formulations, custom-made chemicals, state-of-the-art monitoring systems, and application-specific technologies, leading participants are increasingly differentiating. Regional competition is growing, and service offerings are expanding in strategic growth areas of the industrial water treatment market in India. Additionally, companies are adopting digital solutions to combine with chemical treatment for operational efficiency, scaling and corrosion control, and Zero Liquid Discharge needs. Further evidence of the industrys shift towards more modern, sustainability-driven water management solutions with product launches and acquisitions.
- For instance, in April 2026, Gradiant recently announced the launch of CURE Chemicals in April 2026 to promote environmental sustainability and operational efficiency. The program leverages Gradiants innovation and commercialisation capacity in the key industries where advanced water and wastewater treatment solutions are needed. (Source: en.antaranews.com)
- In May 2026, Dorf-Ketal Chemicals India Limited has acquired the Water Treatment Business of Vasu Chemicals in May, 2026. The acquisition was a strategy by Dorf-Ketal to gain entry into Indias industrial water treatment market and support its application-driven specialty chemicals portfolio.(Source: dorfketal.com)
- In 2026, Ecolab Nalco Water delivered its digital water management solutions and tailored chemicals to heavy industries in India in 2026. Its solutions include real-time monitoring, chemical treatment, scaling/corrosion control, and Zero Liquid Discharge compliance. (Source: en-in.ecolab.com)
Recent Developments
- In July 2026, Kurita Industries formed Kurita Membrane India in partnership with Membrane Group India to supply cutting-edge water treatment solutions to the electronics and semiconductor sectors in India. (Source: smartwatermagazine.com)
Top Players in the Market & Their Offerings
| Company | Company Type/Position | Major Headquarters | Geographic Presence | Asia Pacific Water Treatment Chemicals Offerings | Key Strength |
| Kurita Water Industries Ltd. | Multinational | Tokyo, Japan | Global | Water treatment chemicals and reverse osmosis membrane treatment | Deep integration with electronics and heavy manufacturing water demands |
| Thermax Limited | Regional | Pune, India | Asia Pacific, Middle East | INDION ion exchange resins | Cost-competitive localized production |
Other Key Players
- Ecolab (Nalco Water)
- Kemira
- Kurita Water Industries
- Solenis
- Suez
- Veolia
- BASF
- Dow
- SNF Group
- Solvay
Segment Covered in the Report
By Product
- Coagulants & Flocculants
- Inorganic coagulants
- Alum
- Ferric chloride
- Ferric sulfate
- Polyaluminum chloride (PAC)
- Organic coagulants
- Polyamines
- PolyDADMAC
- Flocculants
- Anionic
- Cationic
- Non-ionic
- Inorganic coagulants
- Biocide & Disinfectant
- Chlorine-based
- Chlorine dioxide
- Hypochlorites
- Quaternary ammonium compounds
- Glutaraldehyde
- Isothiazolinones
- Defoamer & Defoaming Agent
- Silicone-based
- Mineral-oil-based
- Water-based
- EO/PO-based
- pH Adjuster & Softener
- Acids
- Alkalis
- Lime
- Sodium carbonate
- Ion-exchange softeners
- Scale & Corrosion Inhibitor
- Phosphonates
- Polycarboxylates
- Corrosion inhibitors
- Chelating agents
- Specialty deposit-control chemicals
- Other Products
- Oxygen scavengers
- Membrane-cleaning chemicals
- Activated-carbon chemicals
- Antifoaming auxiliaries
- Specialty treatment chemicals
By Application
- Raw Water Treatment
- Drinking-water clarification
- Industrial raw-water clarification
- Pre-treatment
- Water Desalination
- Reverse osmosis
- Multi-stage flash
- Electrodialysis
- Cooling
- Cooling towers
- Closed-loop cooling
- Once-through cooling
- Industrial cooling systems
- Boiler
- Boiler-feed water
- Steam generation
- Condensate treatment
- Effluent Water Treatment
- Industrial wastewater
- Municipal wastewater
- Tertiary treatment
- Water reuse
- Other Applications
- Process water
- High-purity water
- Sludge treatment
- Membrane systems
By Source
- Synthetic
- Petroleum-derived chemicals
- Synthetic polymers
- Synthetic biocides
- Synthetic corrosion inhibitors
- Bio-based
- Bio-based polymers
- Natural coagulants
- Enzyme-based treatment chemicals
- Plant-derived treatment agents
- Fermentation-derived chemicals
By End Use Industry
- Power
- Thermal power
- Hydropower
- Nuclear power
- Renewable power
- Oil & Gas
- Upstream
- Midstream
- Refining
- Petrochemicals
- Chemical Manufacturing
- Basic chemicals
- Specialty chemicals
- Industrial chemicals
- Mining & Mineral Processing
- Coal
- Iron ore
- Copper
- Gold
- Rare earths
- Municipal
- Drinking water
- Municipal wastewater
- Water reuse
- Food & Beverage
- Dairy
- Beverages
- Meat processing
- Food processing
- Pulp & Paper
- Pulping
- Bleaching
- Paper manufacturing
- Other End Uses
- Pharmaceuticals
- Textiles
- Electronics
- Automotive
- Hospitality
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.