
Stearic Acids Market Size, Competitive Landscape Analysis Report 2035
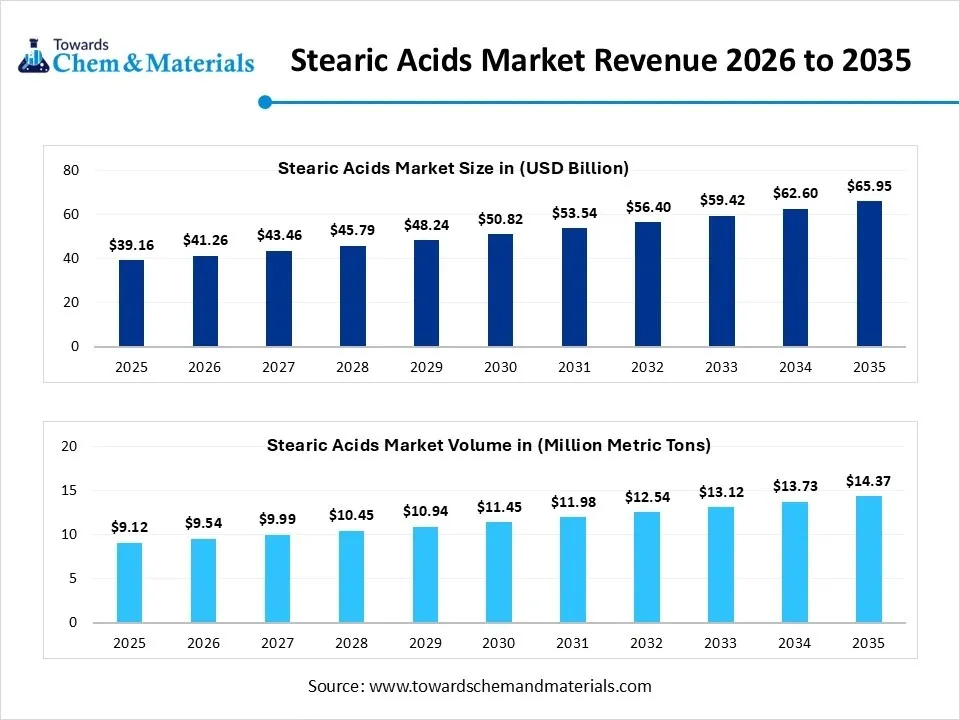
The stearic acids market size was valued at USD 39.16 billion in 2025, is estimated to reach USD 41.26 billion in 2026, and is projected to reach USD 65.95 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 5.35% over the forecast period from 2026 to 2035.Asia Pacific dominated the stearic acids market with the largest revenue share of 46.0% in 2025 and is expected to grow at the fastest CAGR of 5.47% during the forecast period. The market is witnessing steady growth, driven by rising demand for plant-based and high-purity fatty acids in personal care, rubber processing, plastics, pharmaceuticals, candles and industrial applications, supported by expanding oleochemical production and increasing preference for sustainable, bio-based raw materials.
Market Highlights
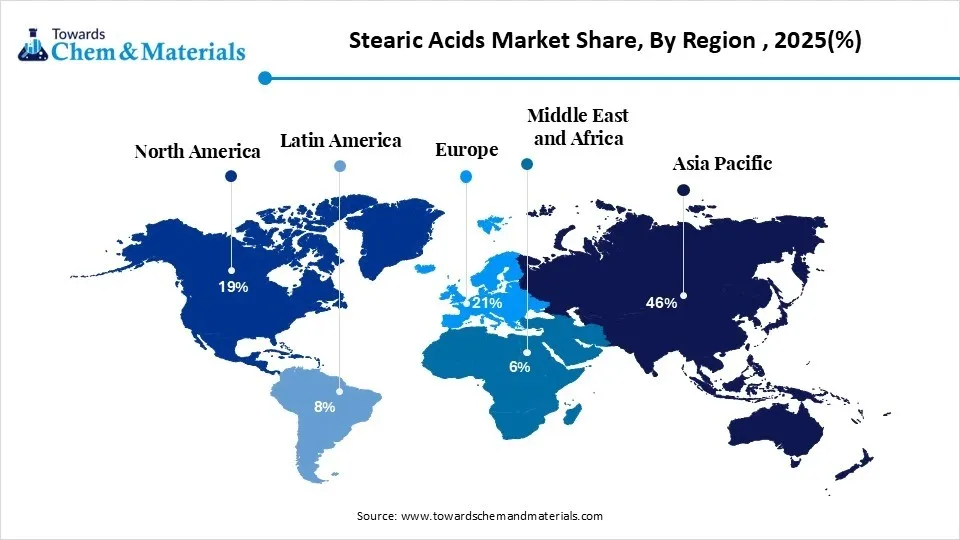
- By region, Asia Pacific dominated the market with the largest share of 46.0% in 2025. The dominance of the region can be attributed to the large oleochemical production capacity, which supports regional supply. Personal care and detergent industries expand rapidly. China, India, Indonesia, and Malaysia remain major producers and consumers.
- By region, North America held a market share of 19.00% in 2025 and was expected to grow at the fastest CAGR of 6.0% over the forecast period. The growth of the region can be credited to strong demand from personal care and rubber industries, which drive consumption. Industrial lubricants maintain stable growth. Sustainable product development encourages innovation.
- By application, the soaps & detergents segment dominated the market with the largest share of 31.0% in 2025. Household and industrial cleaning product demand remains strong. Surfactant production supports stearic acid consumption. Population growth sustains long-term market expansion.
- By application, the personal care segment held a market share of 17.00% in 2025 and is expected to grow at the fastest CAGR of 6.2% over the forecast period. Premium skincare and cosmetic formulations increasingly utilize stearic acid. Natural ingredient preference supports product development. Personal care spending rises globally.
According to Towards Chemicals and Materials Analytics and Consulting, the global stearic acids market volume was valued at 9.12 million metric tons in 2025 and is expected to surpass around 14.37 million metric tons by 2035, accelerating a compound annual growth rate (CAGR) of 4.65% over the forecast period from 2026 to 2035.
Market Overview
The stearic acids market is experiencing steady growth, supported by rising demand for bio-based oleochemicals and sustainable raw materials across personal care, pharmaceuticals, rubber processing, plastics, candles, food and industrial applications. Stearic acid is derived from vegetable oils such as palm and coconut oil. It is widely used as an emulsifier, lubricant, thickener, stabilizer and release agent because of its excellent functional properties and compatibility with a broad range of formulations. As manufacturers increasingly shift toward renewable feedstocks and environmentally responsible products, vegetable-based stearic acid continues to gain preference over petroleum-derived alternatives.
The personal care and cosmetics industry remain one of the largest consumers of stearic acid, where it is used in creams, lotions, soaps, facial cleansers and color cosmetics to improve texture and product stability. Additionally, demand from the rubber vulcanization and a processing aid in polymer manufacturing. Growth in pharmaceutical formulations, food processing and specialty chemicals is also supporting market expansion. To address evolving customer requirements, leading manufacturers are investing in certified sustainable palm oil sourcing, traceable supply chains and high-purity grades to strengthen their product portfolio while meeting stringent environmental and regulatory standards.
- For instance, in July 2025, Kao Corporation announced a major investment to modernize and expand its Green Street manufacturing site in the United Kingdom. The investment aimed at increasing production efficiency, strengthening sustainable manufacturing and supporting the growing demand for specialty chemical ingredients used in personal care and industrial applications. (Source: cosmeticsbusiness.com)
Which Factor is Driving the Growth of the Stearic Acids Industry?
The increasing demand for beauty and personal care products across the globe is spearheading industry growth in the. Current period. Several individuals have been seen buying products such as soaps, lotion, shampoo, and several creams in recent years. Moreover, the unique properties of steric acid, like smoothness and others, make steric acid an ideal choice for these industries. Also, a sudden increase in the youth population is heavily contributing to industrial growth potential, as is an increase in the personal care trend nowadays. In developing countries, steric acid has gained major market share, akin to increasing industrial needs. Furthermore, the implementation of sustainability initiatives has fueled the industrys growth in recent years.
Market Trends
- The sudden expansion in the rubber industry is significantly driving the market growth in the current period. As the demand for rubber softening and improvement of chemical mixing, several manufacturers have actively seen the usage of steric acid in recent years. Also, the adoption of vehicles has heavily contributed to the steric acid industry potential as the use of tires and seals grows at a rapid pace.
- The growing preference for vegan and plant-based products has driven the market growth over the past few years. Also, several companies are seen using plant oil and palm oil to make stearic acid. Moreover, several governments across the world are actively implementing sustainability policies, which are expected to create beneficial opportunities for the steric acid manufacturing community during the forecast period
- The heavy usage of plastic and the revolution of the packaging industry have led to the application of steric acid in the current period. From acting as a stabilizer and lubricant, steric acid has made a significant impact in these industries. The regions such as Asia Pacific, North America, and others have observed heavy usage of steric acid in recent years.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 41.26 Billion/ 9.54 Million Metric Tons |
| Market Size by 2035 | USD 65.95 Billion/ 14.37 Million Metric Tons |
| Growth Rate from 2025 to 2035 | CAGR 5.35% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025 - 2035 |
| High Impact Region | Asia Pacific |
| Segment Covered | By Type, By Region |
| Key Companies Profiled | Emery Oleochemicals, 3F Industries LTD, New Japan Chemical Co.Ltd.; Oleon NV, Wilmar International, BASF SE, Cayman Chemical, Pacific Oleochemicals, Sdn. Bhd., Kao Chemicals, Godrej Industries Limited, VVF (India) Limited, Bloomberg L.P., Twin Rivers Technologies, Inc. |
Supply Chain Analysis
Feedstock Sourcing and Vegetable Oil Production
- The stearic acid supply chain begins with the procurement of natural feedstocks, such as palm oil, palm kernel oil, coconut oil and animal fats. These raw materials are processed into fatty acids through hydrolysis and fractionation. The availability, quality and sustainability of feedstocks significantly influence production costs and supply stability.
- KLK OLEO: It is one of the world’s leading integrated oleochemical producers, manufacturing fatty acids, including stearic acid, from sustainably sourced palm-based feedstocks.
- Other Key Players: Wilmar International, Musim Mas. Kao Corporation.
Stearic Acid Manufacturing
- Natural oils and fats undergo hydrolysis, distillation, hydrogenation and fractional distillation to produce high-purity stearic acid. Manufacturers produce various grades tailored for cosmetics, pharmaceuticals, rubber, plastics, food and industrial applications.
- Kao Corporation: The company manufactures high-purity fatty acids, including stearic acid, for personal care, pharmaceuticals and industrial applications through advanced oleochemical processing technologies.
- Other Key Players: KLK OLEO, Emery Oleochemicals, IOI Oleochemical
Purification, Quality Control & Certification
- After production, stearic acid undergoes purification, distillation and rigorous quality testing to ensure compliance with industry-specific standards for purity, iodine value, acid value and melting point. Manufacturers also obtain certifications such as RSPO, ISO 9001, GMP, Kosher, and Halal.
- Emery Oleochemicals: The company supplies specialty natural-based fatty acids and maintains comprehensive quality management systems to ensure consistent product performance for global industrial and consumer markets.
- Other Key Players: Kao Corporation, KLK OLEO
Distribution & Industrial Supply
- Finished stearic acid is distributed through global chemical distributors, regional warehouses and direct supply agreements with manufacturers. Suppliers provide bulk shipments, customized packaging, technical support, formulation guidance and regulatory documentation to customers.
- Brenntag: The company distributes oleochemicals, including stearic acid, through its global logistics network, offering warehousing, technical expertise, product stewardship and supply chain solutions for industrial consumers.
- Other Key Players: Univar Solutions, IMCD N.V.
Market Opportunity
Pharma-Grade Stearic Acid Set to Capture Market Share
The ongoing expansion of the pharmaceutical sector is expected to create lucrative opportunities for stearic acids market during the forecast period. The pharmaceutical manufacturers are under the heavy usage of steric acid as a lubricant in the production of capsules and tablets. Moreover, as the need for medicines grows across the globe, the pharmaceutical grade steric acid is likely to gain major market share in the coming years. Also, high-purity steric acid can be preferred from this manufacturer for a future period, as per the observation. Also, technological advancement can play a major role in the manufacturing process during the projected period.
Clean Production Investments Rise Amid Raw Material Uncertainty
The constant price fluctuation of raw materials is expected to hamper the market growth of steric acid during the projected period. The cost of this raw material, like animal fat and palm oil, is observed as fluctuating due to factors like supply chain issues, weather, and trade modern trade policy. Moreover, the raw material, like animal fat, is being subjected to growth barriers, moving to rising ethical concerns, while the palm oil can also face some restrictions due to the ongoing environmental issues. However, manufacturers have increasingly observed making heavy investments in cleaner and environmentally friendly production in recent years.
Segmental Insights
By Application Insights
The soap and detergents segment held the largest share of the market in 2025, akin to stearic acid is a key ingredient in making soaps and cleaning products. It helps soaps become solid, gives them a smooth texture, and helps them clean better. It also helps soap lather well and stay firm, especially in bar soaps. Since people in both cities and villages use soap every day, the demand is very high. Stearic acid is also used in laundry powders and liquid detergents to improve quality. The low cost of stearic acid and its easy availability make it a preferred choice for soap makers. Moreover, the fast growth of the population and better hygiene awareness have boosted soap use across India and other countries. This strong and steady demand has made soaps and detergents the leading segment in the stearic acids market in recent years.
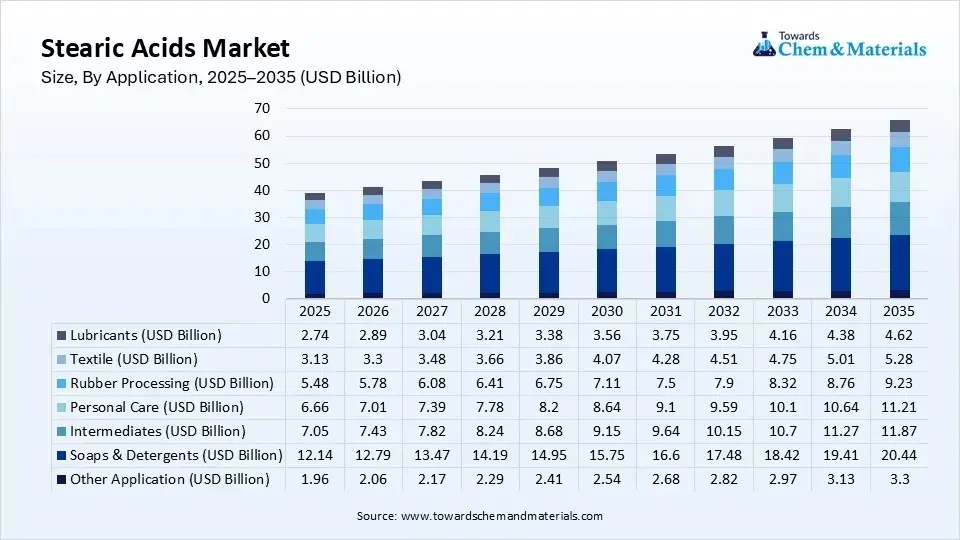
The personal care segment expects a notable rate during the forecast period, owing to more people using skincare and cosmetic products like creams, lotions, shampoos, and makeup. Stearic acid helps in making these products soft, thick, and smooth. It also helps mix oil and water, which is important in creams and lotions. As more people focus on beauty, grooming, and personal hygiene, especially in growing cities, the demand for these products is increasing fast. Younger generations are also spending more on skincare and wellness items. Stearic acid is gentle on the skin, which makes it suitable for daily-use products. With rising incomes, busy lifestyles, and more awareness of personal care, this segment will likely grow quickly. As a result, manufacturers will use more stearic acid to meet the growing demand, and the personal care segment will become the leading use area in the coming years.
Stearic Acids Market Share, By Application, 2025(%)
| By Application | Market Share (%) |
| Soaps & Detergents | 31% |
| Intermediates | 18% |
| Personal Care | 17% |
| Rubber Processing | 14% |
| Textile | 8% |
| Lubricants | 7% |
| Other Application | 5% |
Regional Analysis
How did the Asia Pacific Dominate the Stearic Acids Market in 2025?
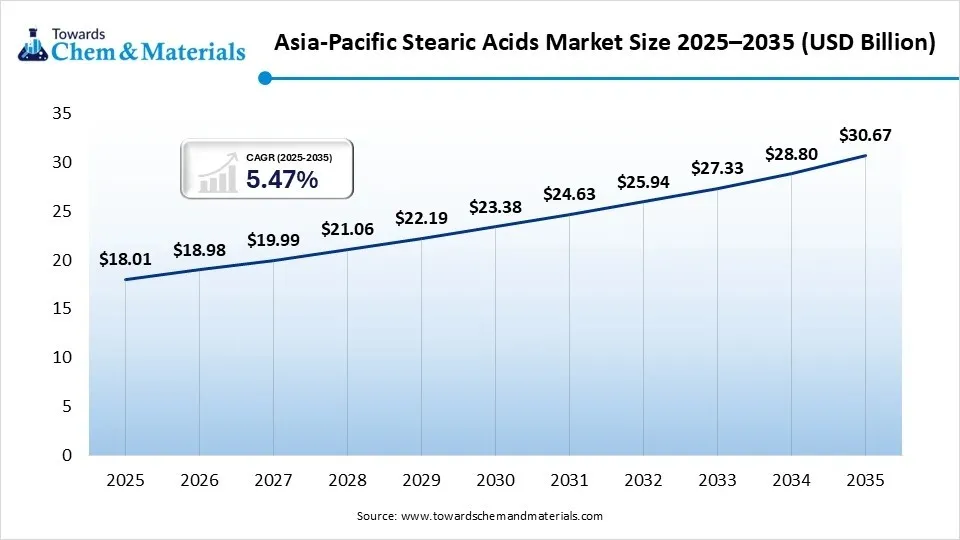
The Asia Pacific stearic acids market size was estimated at USD 18.01 billion in 2025 and is projected to reach USD 30.67 billion by 2035, growing at a CAGR of 5.47% from 2026 to 2035.Asia Pacific dominated the market with the largest share of 46.0% in 2025. The dominance of the region can be attributed to the large oleochemical production capacity, which supports regional supply. Personal care and detergent industries expand rapidly. China, India, Indonesia, and Malaysia remain major producers and consumers. Rising demand for bio-based ingredients, coupled with increasing investments in sustainable palm oil certification and downstream manufacturing, continues to strengthen the regional market.
China
- The country’s market is driven by its extensive rubber, plastics, cosmetics and industrial manufacturing sectors.
- Demand is increasing due to expanding production of tires, polymer compounds, personal care products and household chemicals.
- The country’s growing focus on sustainable chemical manufacturing and bio-based materials is encouraging greater adoption of vegetable-derived stearic acid.
India
- The market is supported by rapid growth in the personal care, pharmaceuticals, rubber processing and plastics industries.
- Government initiatives, rising domestic manufacturing and increasing consumer demand for cosmetics and hygiene products are boosting stearic acid consumption.
- Growth in the FMCG sector and expanding oleochemical production are supporting market development.
North America held a market share of 19.00% in 2025 and was expected to grow at the fastest CAGR of 6.0% over the forecast period. The growth of the region can be credited to strong demand from personal care and rubber industries, which drive consumption. Industrial lubricants maintain stable growth. Sustainable product development encourages innovation. Manufacturers are increasingly replacing petroleum-based additives with renewable oleochemicals to meet consumer preferences and sustainability goals.
United States
- The country has strong cosmetics, pharmaceutical, plastics and rubber manufacturing industries.
- Growing consumer preference for plant-based personal care products and clean-label formulations is driving higher demand for vegetable-derived stearic acid.
- The country’s focus on sustainable sourcing and green chemistry is encouraging manufacturers to adopt certified oleochemical ingredients.
Canada
- The market is supported by increasing demand for natural cosmetics, food ingredients and pharmaceutical excipients.
- The country’s emphasis on sustainable manufacturing and environmentally friendly consumer products is contributing to greater adoption of bio-based stearic acid.
Europe held a market share of 21.00% in 2025. The growth of the region can be credited to mature personal care and chemical industries sustaining demand. Bio-based ingredient adoption supports market stability. Industrial manufacturing remains a key consumer. European manufacturers are prioritizing certified sustainable palm oil and traceable supply chains to comply with evolving regulatory requirements and consumer expectations.
Germany
- The country has advanced chemical, automotive, plastics and cosmetics industries.
- Stearic acid is widely used in rubber processing, engineering plastics, lubricants and personal care formulations.
- Growing investments in sustainable chemical production and bio-based materials continue to support market expansion.
France
- The France market is driven by its globally recognized cosmetics and luxury personal care industry.
- Increasing demand for naturally derived cosmetic ingredients, combined with growing adoption of sustainable formulations and clean-label products, is boosting stearic acid consumption.
Latin America held a market share of 8.00% in 2025. The growth of the region can be credited to expanding detergent manufacturing, which supports stearic acid demand. Personal care consumption increases steadily. Industrial development boosts downstream applications. The region benefits from abundant agricultural resources that support vegetable oil production, creating opportunities for oleochemical manufacturing.
Brazil
- The country has a large cosmetics industry, an expanding food processing sector and a well-developed agricultural economy.
- Increasing production of soaps, detergents, personal care products and rubber goods continues to drive demand for stearic acid.
- Investments in bio-based chemicals and renewable feedstocks are strengthening the country’s market position.
Chile
- The market growth is supported by increasing demand for personal care products, industrial lubricants, food processing and pharmaceutical manufacturing.
- Continued expansion of consumer goods and industrial production is creating new opportunities for stearic acid applications.
The Middle East and Africa held a market share of 6.00% in 2025. The growth of the region can be credited to the growing consumer goods manufacturing, which increases demand. Investments in chemical processing support market expansion. Construction and industrial activities sustain lubricant consumption. The region is benefiting from growing awareness of sustainable and bio-based ingredients.
Saudi Arabia
- The ongoing industrial diversification under Vision 2030, expanding petrochemical and downstream manufacturing sectors and increasing production of personal care and household products are driving the market.
- Rising investments in specialty chemicals and industrial manufacturing are supporting higher consumption of stearic acid.
South Africa
- The market is driven by increasing demand from the cosmetics, pharmaceuticals, rubber, plastics and food processing industries.
- Growing consumer preference for natural ingredients, coupled with investments in local manufacturing and industrial development, is contributing to increased adoption of stearic acid.
Recent Developments
- In April 2025, The Dove and Chamberian Coffee introduced their latest product line of plant milk cleaners. This cleaner includes skin-loving ingredients such as lauric acid, nutrient-rich plant milk, and stearic acid as per the companys claim. Also, for this product development, these companies made a strategic collaboration. (Source: beautypackaging )
- In November 2023, Croda unveiled ingredients for the High SPF and UVA Protection sunscreen. Moreover, this ingredient includes polyglyceryl-4 Laurate, steric acid, and other main ingredients, which allows for high SPF with skin clarity as per the companys claim.(Source: cosmeticsandtoiletries )
Top Companies list
- Emery Oleochemicals
- 3F Industries LTD
- New Japan Chemical Co.Ltd.;
- Oleon NV
- Wilmar International
- BASF SE
- Cayman Chemical
- Pacific Oleochemicals, Sdn. Bhd.
- Kao Chemicals
- Godrej Industries Limited
- VVF (India) Limited
- Bloomberg L.P.
- Twin Rivers Technologies, Inc.
Segment Covered
By Application
- Soaps & Detergents
- Laundry Detergents
- Bar Soaps
- Liquid Soaps
- Household Cleaners
- Intermediates
- Metallic Stearates
- Fatty Acid Esters
- Plastic Additives
- Chemical Synthesis Intermediates
- Personal Care
- Skin Care Products
- Hair Care Products
- Cosmetics
- Toiletries
- Rubber Processing
- Tire Manufacturing
- Industrial Rubber Products
- Footwear
- Automotive Rubber Components
- Textile
- Textile Finishing
- Fiber Processing
- Lubricating Agents
- Lubricants
- Industrial Lubricants
- Metalworking Fluids
- Greases
- Other Application
- Candles
- Pharmaceuticals
- Food Additives
- Plastic Processing
- Paper Industry
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Latin America
- Brazil
- Middle East and Africa (MEA)
- KSA
- UAE
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.