
Green Steel Market Size Analysis Report 2035
The green steel market size was estimated at USD 78.11 billion in 2025 and is projected to grow from USD 94.63 billion in 2026 to approximately USD 532.04 billion by 2035, at a CAGR of 21.15% from 2026 to 2035. Asia Pacific dominated the steel market market with the largest revenue share of 44% in 2025 and is expected to grow at the fastest CAGR of 21.29% during the forecast period.
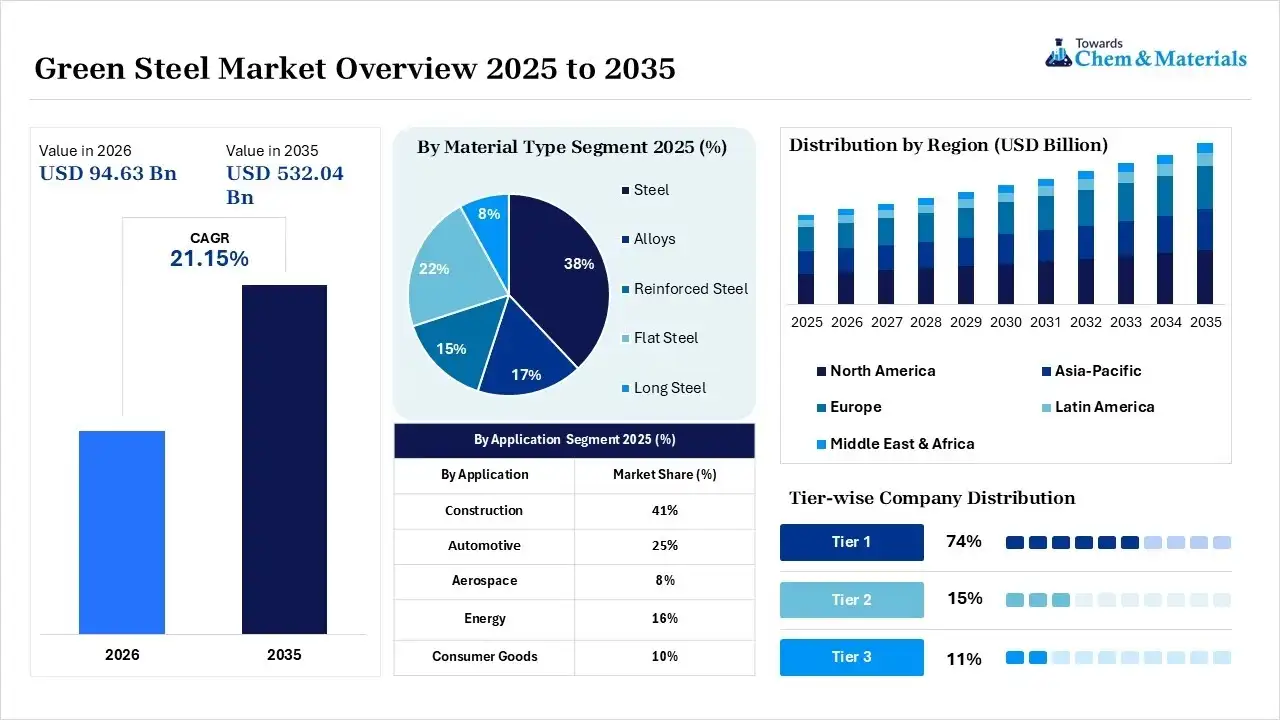
The growing adoption across industries and regulatory pressure by governments worldwide to use green energy and clean energy for the manufacturing of components in various industries drives the growth of the use of green steel. The use of dominant technologies like hydrogen DRI-EAF and renewable-powered EAF with 100% renewable electricity and steel scrap leads to greater adoption. The major automotive industry and manufacturers and corporate commitments are signing supply agreements to lower supply chain emissions, which will support market growth in the coming years.
Market Highlights
- By region, Asia Pacific dominated the green steel market with a share of 44% in 2025 and is expected to grow at a CAGR of 22.80% over the forecast period.
- By region, North America held 16% market share in the green steel market in 2025 and is expected to experience the fastest growth with a CAGR of 24.70% in the forecast period.
- By application, the construction segment dominated the market with a 41% share in 2025 and is expected to grow at a CAGR of 20.90% over the forecast period.
- By application, the automotive segment held 25% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.60% in the forecast period.
- By end use, the building materials segment dominated the market with a 39% share in 2025 and is expected to grow at a CAGR of 20.80% over the forecast period.
- By end use, the transportation segment held 24% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.10% in the forecast period.
- By production method, the electric arc furnace segment dominated the market with a 36% share in 2025 and is expected to grow at a CAGR of 20.70% over the forecast period.
- By production method, the hydrogen reduction segment held 23% market share in 2025 and is expected to have the fastest growth with a CAGR of 28.50% in the forecast period.
- By material type, the steel segment dominated the market with a 38% share in 2025 and is expected to grow at a CAGR of 20.60% over the forecast period.
- By material type, the flat steel segment held 22% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.30% in the forecast period.
- By technology, the smart manufacturing segment dominated the market with a 27% share in 2025 and is expected to grow at a CAGR of 23.60% over the forecast period.
- By technology, the digital twin technology segment held 14% market share in 2025 and is expected to have the fastest growth with a CAGR of 25.40% in the forecast period.
According to Towards Chemicals and Materials Analytics and Consulting, the global green steel market volume was valued at 49.66 million metric tons in 2025 and is expected to surpass around 548.49 million metric tons by 2035, accelerating a compound annual growth rate (CAGR) of 27.15% over the forecast period from 2026 to 2035.

Market Overview
Green Steel Market: Clean Energy and Clean Hydrogen
The green steel market is growing due to surging demand for low-emission manufacturing, as green steel manufacturers are using renewable energy and electric furnaces, which do not emit carbon; instead use electricity or release water vapor instead of carbon, which increases use and demand from the industry. The high usage in automotive and construction sectors due to the leading expansion of hydrogen direct reduced iron with electric arc furnaces drives demand. The strict regulatory and policy-driven adoption in regions aligning with volume capacity and localized output drives growth. The presence of global producers like ArcelorMittal, SSAB, Tata Steel, Nucor
Corporation, and China Baowu Steel Group is a leading investor in low-carbon emission product manufacturing.The rapidly scaling industries like building and construction, automotive and transportation sector due to its application due to strict Scope 3 emission targets. The growth is propelled by EU carbon neutrality targets and rapidly scaling industrial output in countries like China and India. The major steel producers, energy companies, and automotive joint ventures and cross-sector supply chain partnerships like JSW Steel & UNSW SMaRT Center, Volkswagen Group & Vulcan Green Steel / Thyssenkrupp, and HYBRIT Initiative play a major role in the growth of the market.
- For instance, earlier, Volkswagen partnered with Vulcan Green Steel (part of Jindal Steel Group) and Thyssenkrupp Steel to source low-carbon and bluemint steel for automotive manufacturing and electromobility.(Source:www.volkswagen-group.com)
- For instance, in September 2025, Mukand Sumi Special Steel Limited expanded its production plant with the construction of a greenfield integrated steelmaking facility in Karnataka with a joint partnership between Bajaj Group and Japan’s Sumitomo Corporation.(Source: www.newindianexpress.com)
What is Green Steel?
The market refers to the industry that produces steel using eco-friendly practices that substantially minimize or eliminate carbon emissions and other environmental impacts.
This transformation involves replacing high-emissions and conventional processes with cleaner technologies such as electric furnaces powered by hydrogen-based reduction and renewable energy. The market is growing due to stringent environmental regulations and a rise in demand from the end-user industry, along with the growing demand for low-carbon materials.
What is Green Steel?
Green steel is steel that is made with little or no fossil fuel, which helps preserve natural resources and also aligns with cutting down carbon pollution, which is caused by traditional factories. The industries with green steel manufacturing do not use coal as a burning agent; instead, it relies on clean methods like the use of green hydrogen or electric arc furnaces. It matters because it lowers emissions close to zero and also as it is used under official guidelines and measured as greenness based on emission intensity. It is made by using green hydrogen, which leaves water vapor instead of carbon dioxide as a by-product, electric arc furnaces, which melt scrap metals, and renewable power, which runs on clean electricity sources.
What are the Key Uses of the Green Steel Market?
- Automotive and Transportation: the growing use of green steel due to demand for lightweight electric vehicle components like battery enclosures, which helps lower supply chain emissions, driving growth.
- Building and Construction: the growing infrastructure development projects and demand for green building frameworks with low-carbon certification standards are key applications and uses of green steel.
- Energy and Utilities: the use of green steel in the manufacturing of wind turbines and solar panel mounting structures and power transmission infrastructure.
- Industrial Machinery and Equipment: the addition by manufacturers to produce sustainable and heavy equipment with reduced carbon footprint drives the growth of the market.
Green Steel Premium Pricing Valuation
Green steel products are slightly premium akin to the high manufacturing costs, which are the result of the use of high and advanced technologies to produce low-carbon-emission steel through green hydrogen production and renewable energy utilization, such as scrap steel, which adds to the recycling cost of the product. This shift in the use of green steel aligns with sustainable initiatives and regulatory pressure for the use of lower-carbon-emission products. However, the pricing in the coming years is set to lower with heavy investments and policies of the government for green infrastructure development projects in and across the regions. The development of high-end green hydrogen capacities to lower carbon emissions in various countries will contribute to lowering the cost of green steel in the coming years.
Green Steel Market Carbon Tariff Evaluation
Traditional steel, which is made from blast furnaces, emits a high level of carbon. The increasing global influence and adoption of green manufacturing technologies by companies across the market to improve environmental conditions through sustainable procurement policies and standards promotes their use. The Carbon Border Adjustment Mechanism helps reshape the global green steel market by penalizing high-emission traditional production and also closing the cost gap for green and clean alternatives. This shift drives the financial viability of hydrogen-based direct reduced iron. Regional policies by the government are introduced, such as tax deduction of low carbon steel to help offset operating expenses.
Global Investment Flow for Green Steel Market 2026
The Global Energy Monitor report reveals that the global steel industry is doubling down on coal infrastructure, allowing new coal-based capacity to heavily outpace plant retirements. Despite highly publicized green steel initiatives, 319 million tonnes per annum of traditional blast furnace capacity is currently announced or under construction globally, marking a 5% increase year-over-year.(Source: globalenergymonitor.org)
- In January 2026, Tata Steel signed a formal Letter of Intent and Memorandum of Understanding with the Government of Jharkhand at the World Economic Forum in Davos to deploy ₹11,100 crore ($1.22 billion) in advanced green steel technologies. The investments mark a major milestone in transitioning Indias heavy industry away from traditional fossil-reliant blast furnaces.(Source: gmk.center)
- In April 2026, the Swedish green steel startup Stegra (formerly H2 Green Steel) secured a massive €1.4 billion ($1.7 billion) equity investment from an investor consortium led by the prominent Wallenberg family. This major capital injection provides a critical financial lifeline to complete the construction of its flagship, hydrogen-based greenfield steel plant in northern Sweden.(Source: infra.economictimes.indiatimes.com)
Market Growth Trends:
- The growing demand from automotive sectors like Volvo, Mercedes-Benz, BMW, and General Motors, which increasingly adopt green steel, aligns with sustainable initiatives, and adoption through direct investments and supply agreements between the companies is a major growth trend in the market.
- The rising demand and supply of hydrogen-based production and hydrogen direct reduced iron and EAF combination is a leading and primary steel manufacturing method which uses green hydrogen as a reducing agent instead of carbon, which drives growth.
- The growing shift towards electric Arc Furnace technology moving away from traditional blast furnaces, which uses recycled scrap steel and renewable power, supporting elimination of greenhouse gas emissions, supporting growth.
Key Shift Caused by AI Integration: Green Steel Manufacturing
The shift in green steel manufacturing through AI integration transforms from traditional carbon-intensive towards hydrogen- or electric-based manufacturing, also through AI- or data-driven manufacturing, which lowers carbon intensity and operational waste. The integration of machine learning helps in optimizing energy and process like complex operation such as balancing EAF and hydrogen-based reduction units. Other key shifts are automated compliance and documentation, predictive maintenance, and reduced downtime.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 94.63 Billion/ 63.14 Million Metric Tons |
| Expected Size in 2035 | USD 532.04 Billion/ 548.49 Million Metric Tons |
| Growth Rate | CAGR of 21.15% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Application, By End Use, By Production Method, By Material Type, By Technology, By Region |
| Key Companies Profiled | China Baowu Steel Group (China), Tata Steel (India), Nucor Corporation (U.S.), Nippon Steel Corporation (Japan), Voestalpine AG (Austria), Salzgitter AG (Germany), Emirates Steel Arkan (UAE), JFE Steel Corporation (Japan), JSW Steel (India), Outokumpu Oyj (Finland), Boston Metal (U.S.), Liberty Steel Group (UK/Global), Swiss Steel Group (Switzerland), Jindal Steel & Power (India), Tenaris (Luxembourg) |
Supply Chain Analysis of Green Steel Market
Green Steel Production & Processing
- Green steel is produced using low-carbon technologies such as hydrogen-based direct reduced iron, electric arc furnaces powered by renewable electricity, and recycled steel feedstocks to significantly reduce greenhouse gas emissions during steel manufacturing.
- SSAB is a leading producer of fossil-free steel, utilizing hydrogen-based ironmaking and renewable energy to manufacture low-carbon steel for the automotive, construction, heavy equipment, and energy industries.
- Key Players: SSAB, H2 Green Steel, ArcelorMittal, thyssenkrupp Steel.
Quality Testing & Certification
- Green steel must comply with standards for mechanical properties, chemical composition, carbon emissions, product traceability, and environmental sustainability before commercial use.
- ArcelorMittal is advancing green steel production through hydrogen-based DRI, electric arc furnace technologies, and increased recycled steel utilization while aligning its products with international sustainability and quality standards.
- Key Authorities & Standards: International Organization for Standardization, ResponsibleSteel, World Steel Association, European Union.
Distribution to End-Use Industries
- Green steel is supplied to automotive manufacturers, construction companies, renewable energy developers, machinery manufacturers, appliance producers, and infrastructure projects seeking low-carbon steel materials.
- H2 Green Steel manufactures near-zero-emission steel using renewable electricity and green hydrogen, supplying sustainable steel products to automotive, industrial, and construction customers seeking to reduce the carbon footprint of their supply chains.
- Key Suppliers: SSAB, H2 Green Steel, thyssenkrupp Steel.
Sustainability Analysis of Green Steel
Green steel is produced using less or no fossil fuels like coal; instead, green hydrogen is used to produce green steel, which aims at reducing carbon emissions, aligning with the sustainability profile and regulatory pressure. The environmental benefits provided, such as carbon reduction and resource circularity without losing the materials original properties through recycling, drive the growth. Compliance needs like the EUs Carbon Border Adjustment Mechanism (CBAM) make low-carbon steel vital for maintaining export competitiveness.
Market Dynamics
Drivers: Corporate Net-Zero Commitments
The growth of the market is driven by stringent government climate regulations, which increasingly use and adopt cleaner methods for aligning with sustainability initiatives and demand. The major industries and manufacturers include Volvo, Mercedes-Benz, and BMW, committed to net-zero carbon use and emissions; the manufacturers are aggressively buying green steel to cut their supply chain or Scope 3 emissions and market sustainable products. The government is updating infrastructure mandates and policies, with technological innovation in steel production commercially, which drives growth.
Challenges: High Production and Capital Costs
The key challenges that hinder growth are the high production and capital costs due to expensive inputs, escalating energy bills, and massive CapEx, which restricts the market from growth. The supply chain and infrastructure bottlenecks include scarcity of clean output due to a shortage of green hydrogen and renewable electricity supply and raw materials adjustments. Another major and key challenge is the market and economic pressures, like early demand and cheap high-carbon competition, which hinder growth.
Opportunities : Technological Advancements
The key growth opportunities in the green steel market are centered around hydrogen-based production tech, surging demand from low-carbon automotive and construction sectors, and supportive regulatory frameworks. The technological advanced like hydrogen-based direct reduced iron and electric arc furnaces help reduce the carbon footprint and also help shift from traditional methods towards more sustainable manufacturing.
Green Steel Regulatory Landscape
| Country / Region | Regulatory Body | Key Regulations | Focus Areas | Notable Notes |
| United States | Environmental Protection Agency; Department of Energy | Clean Air Act; Inflation Reduction Act; Clean Energy Incentives | Low-carbon steel production, energy efficiency | The U.S. supports green steel production through investments in hydrogen, electric arc furnaces, and carbon reduction technologies. |
| European Union | European Commission; European Chemicals Agency | EU Emissions Trading System; Carbon Border Adjustment Mechanism | Decarbonization, low-emission steelmaking | Europe promotes green steel through stringent carbon regulations, renewable energy integration, and hydrogen-based steel production. |
| China | Ministry of Industry and Information Technology; Ministry of Ecology and Environment | Carbon Peak Action Plan; Environmental Protection Law | Energy efficiency, emission reduction | China is modernizing its steel industry by adopting electric arc furnaces and low-carbon steelmaking technologies. |
| India | Ministry of Steel; Bureau of Energy Efficiency | National Green Hydrogen Mission; Perform, Achieve and Trade Scheme | Hydrogen-based steelmaking, energy efficiency | India is promoting green steel production through renewable energy integration and low-carbon manufacturing initiatives. |
| Japan | Ministry of Economy, Trade and Industry | Green Growth Strategy; Energy Conservation Act | Hydrogen reduction, carbon-neutral steel | Japan focuses on advanced steelmaking technologies to reduce emissions and improve energy efficiency. |
| Germany | Federal Ministry for Economic Affairs and Energy; German Environment Agency | National Hydrogen Strategy; EU ETS Compliance | Hydrogen-based steel, industrial decarbonization | Germany is a global leader in green steel development through large-scale investments in hydrogen-based direct reduced iron (DRI) and sustainable steel production. |
Segmental Insights
Application Insights
The construction segment dominated the market with a 41% share in 2025 and is expected to grow at a CAGR of 20.90% over the forecast period. The green building regulation aligns with sustainability initiatives, and demand for green building initiatives drives demand, supporting growth. The infrastructure development plans and industrial decarbonization accelerate growth and procurement, supporting expansion. The public investments, which demand sustainable and green low-carbon materials for the construction of buildings, further support growth.

The automotive segment held 25% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.60% in the forecast period. The rapid expansion of EV production due to increased adoption of lightweight materials and increasing fuel efficiency drives the growth. The net-zero targets of automakers to reduce carbon emissions and use green energy and renewable energy fuels the growth. OEMs supply green steel contracts to the industry where there is a need for outsourcing of the materials, supporting growth.
Green Steel Market Share, By Application, 2025 (%)
| By Application | Market Share (%) |
| Construction | 41% |
| Automotive | 25% |
| Aerospace | 8% |
| Energy | 16% |
| Consumer Goods | 10% |
End Use Insights
The Building Materials Segment Dominated the Green Steel Market With 39% Market Share in 2025
The building materials segment dominated the market with a 39% share in 2025 and is expected to grow at a CAGR of 20.80% over the forecast period, driven by rapid urbanization and green material consumption standards supported by regional sustainability initiatives, which drive growth. Government support and initiatives align and prioritize supporting policies with environmental regulations, which support expansion of the market.
The transportation segment held 24% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.10% in the forecast period. The rapid expansion of electric vehicles and mobility due to growing demand for fuel-efficient and sustainable options drives growth. Modernization of rail increases the demand for steel, especially green steel, due to growing demand, which supports growth. Sustainability commitments and accelerated adoption of green steel in transportation support expansion.
Green Steel Market Share, By End Use, 2025 (%)
| By End Use | Market Share (%) |
| Building Materials | 39% |
| Transportation | 24% |
| Machinery | 15% |
| Infrastructure | 17% |
| Electronics | 5% |
Production Method Insights
The Electric Arc Furnace Segment Dominated the Green Steel Market With 36% Market Share in 2025
The electric arc furnace segment dominated the market with a 36% share in 2025 and is expected to grow at a CAGR of 20.70% over the forecast period. Use of scrap for the production of green steel improves sustainability, and the use of recycled products supports the growth. The renewable electricity demand, as it lowers carbon emissions and improves environmental sustainability, contributes to its growth. The infrastructure development and scaling of the market.
The hydrogen reduction segment held 23% market share in 2025 and is expected to have the fastest growth with a CAGR of 28.50% in the forecast period. The growing green hydrogen investment and use of green hydrogen to reduce reliance on coal, which exempts the release of carbon, support growth. Government-supportive incentives and commercialization of green hydrogen support expansion. The net zero initiatives further propel the use of hydrogen and attract steel makers, which fuels growth.
Green Steel Market Share, By Production Method, 2025 (%)
| By Production Method | Market Share (%) |
| Electric Arc Furnace | 36% |
| Hydrogen Reduction | 23% |
| Direct Reduced Iron | 18% |
| Recycling | 17% |
| Biomass Reduction | 6% |
Material Type Insights
The steel segment dominated the market with a 38% share in 2025 and is expected to grow at a CAGR of 20.60% over the forecast period. The increased consumption due to structural integrity and dominant consumption for structural applications drives growth. Industrial innovation and advancements in steelmaking boost demand and support the growth of the market. The growing demand for premium-grade steel boosts the growth and expansion of the market.
- In July 2026, the Indian Stainless Steel Development Association and the Global Stainless Steel Expo formed a strategic partnership to establish stainless steel as a foundational element of Indias green infrastructure transition. The collaboration focuses on promoting corrosion-resistant alloys for building.(Source: www.aninews.in)
 The flat steel segment held 22% market share in 2025 and is expected to have the fastest growth with a CAGR of 24.30% in the forecast period. The growing demand from the automotive sector, especially electric vehicle demand, drives the growth. The demand from appliance manufacturers and increased adoption of flat steels due to growing applications and demand drive growth.
Green Steel Market Share, By Material Type, 2025 (%)
| By Material Type | Market Share (%) |
| Steel | 38% |
| Alloys | 17% |
| Reinforced Steel | 15% |
| Flat Steel | 22% |
| Long Steel | 8% |
Technology Insights
The smart manufacturing segment dominated the market with a 27% share in 2025 and is expected to grow at a CAGR of 23.60% over the forecast period. The integration of AI to increase production efficiency further supports the growth. The reinforcement and utilization of Industry 4.0 technologies to optimize low-carbon production processes and reduce energy waste. Automated tracking systems help manufacturers meet rigorous carbon border adjustment mechanisms and environmental reporting standards, supporting the growth.
The digital twin technology segment held 14% market share in 2025 and is expected to have the fastest growth with a CAGR of 25.40% in the forecast period. It functions as a critical optimization and simulation segment within the green steel market, helping manufacturers transition to net-zero operations by creating real-time virtual replicas of physical plants, furnaces, and production chains. Manages greenfield and brownfield facility retrofits with minimal disruption to existing infrastructure, supporting the growth and expansion of the market.
Green Steel Market Share, By Technology, 2025 (%)
| By Technology | Market Share (%) |
| Carbon Capture Utilization | 24% |
| Green Steel Market Integration | 17% |
| Smart Manufacturing | 27% |
| Advanced Metallurgy | 18% |
| Digital Twin Technology | 14% |
Regional Insight
How did Asia Pacific dominate the Green Steel Market in 2025?
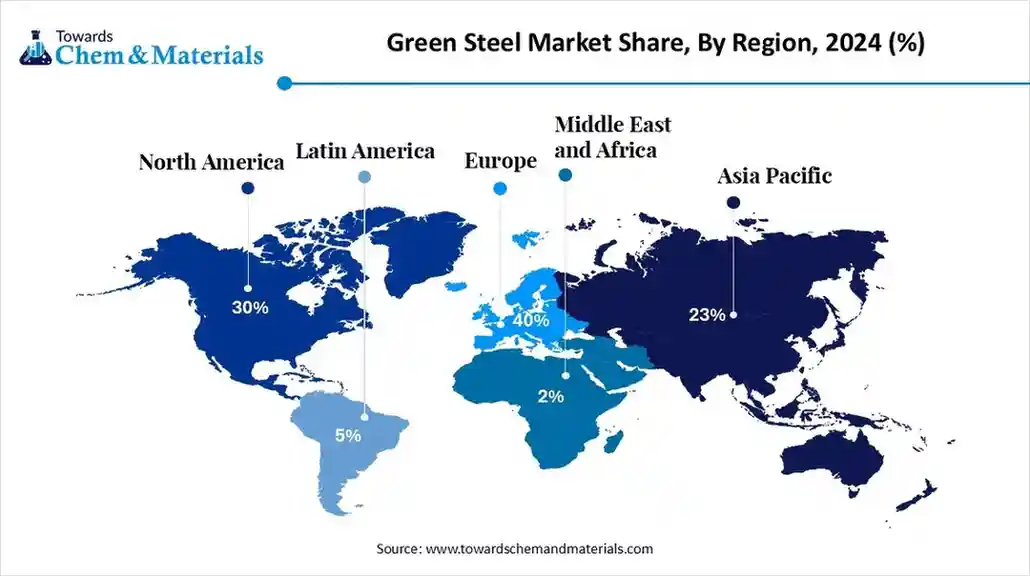
The Asia Pacific green steel market size was estimated at USD 34.37 billion in 2025 and is projected to reach USD 236.76 billion by 2035, growing at a CAGR of 21.29% from 2026 to 2035.Asia Pacific dominated the green steel market with a share of 44% in 2025 and is expected to grow at a CAGR of 22.80% over the forecast period, driven by massive production and consumption due to increased demand and the region being a large steel producer in countries like India, China, Japan, and South Korea, with heavy demand from sectors like automotive, electronics and construction which fuels growth. Strategic industry investments through major giants such as China Baowu, HBIS Group, POSCO, and Nippon Steel help improve energy efficiency, driving growth. The government policies and raw material partnerships which accelerate the shift towards sustainable manufacturing practices.

India Increases Green Steel Demand from Various Sectors
Indias green steel market is entering a rapid growth phase, driven by construction, infrastructure, and automotive sectors due to growing demand for green steel and green products shifting towards sustainable initiatives. The EUs Carbon Border Adjustment Mechanism (CBAM) makes traditional blast-furnace steel increasingly uncompetitive for export, pushing domestic manufacturers toward low-carbon methods.
- For instance, in July 2026, the Government of India is set to launch a ₹50-billion ($528-million) scheme, titled the National Strategy for Sustainable Secondary Steel, to promote clean technology adoption within three months. This initiative targets reducing emissions from the steel sector, which constitutes 10-12% of Indias total greenhouse gas emissions.(Source: carbon-pulse.com)
China Domestic Demand Shifts Towards Green Market
Chinas green steel market growth is driven by its advances in green steel manufacturing through hydrogen-based metallurgy and electric arc furnaces, highlighted by Baowu Steels completion of a 1-million-ton near-zero carbon production line in Zhanjiang, Guangdong province. The domestic shifts, as demand is slowly pivoting away from traditional real estate toward electric vehicles, renewable energy infrastructure, and high-end manufacturing, drive growth.
- For instance, in December 2025, Chinas state-owned steel giant, China Baowu Steel Group, officially put into full operation the countrys first million-tonne near-zero-carbon steel production line. This project marks a massive technological milestone by replacing traditional carbon-heavy coke with hydrogen as the primary reducing agent.(Source: gmk.center)
North America Green Steel Market: Strict Environmental Regulation
The North America green steel market size was estimated at USD 12.50 billion in 2025 and is projected to reach USD 87.79 billion by 2035, growing at a CAGR of 21.52% from 2026 to 2035.North America held 16% market share in the green steel market in 2025 and is expected to experience the fastest growth with a CAGR of 24.70% in the forecast period, driven by stringent environmental regulations as governments are actively setting up stricter carbon emission limits and also forcing heavy industries to cut greenhouse gas outputs, driving growth. Technological innovation, which is driven by high-end investments in advanced processing and scaling of cleaner production, supports growth.
United States Corporate Sustainability Goals
The United States green steel market is heavily driven by corporate sustainability goals and a shift towards the use of technologically advanced processes, which offer scalable alternatives for manufacturing green steel. Leading U.S. producers like Nucor Corporation and technology innovators such as Boston Metal are scaling low-emission output to meet voluntary net-zero commitments demanded by eco-conscious consumers and investors, which is a major growth factor in the expansion of the market.
- For instance, in June 2026, A milestone circular economy and steel recycling project was launched by SSAB Americas in the United States. Developed in a tripartite partnership alongside The Greenbrier Companies and Alter Trading, the initiative establishes a fully closed-loop industrial lifecycle to manufacture sustainable steel with near-zero emissions.(Source: gmk.center)
Canadas Presence of Raw Materials
Canadas green steel market is growing rapidly due to abundant natural resources, government decarbonization support, and rising demand from automotive and construction sectors aiming for net-zero goals. The presence of abundant raw materials provides strong growth for domestic foundations for producing carbon-free raw materials. The federal funding and climate-focused tax regimes are the major growth propellers, as this helps the Canadas produces to transit to sustainability.
Europe Green Steel Market Growth Factor
The Europe green steel market size was estimated at USD 22.65 billion in 2025 and is projected to reach USD 156.95 billion by 2035, growing at a CAGR of 21.36% from 2026 to 2035.Europe held a market share of 29% in 2025, driven by strict environmental regulations, ambitious carbon-neutrality commitments, and rising demand for sustainable supply chains across the automotive and construction sectors. Policies like the European Green Deal and the Carbon Border Adjustment Mechanism penalize high-emission manufacturing while creating strong financial incentives for low-carbon alternatives. The hydrogen projects in the region receive large funding, which drives expansion.
- For instance, in December 2025, ArcelorMittal France launched its €500 million ($545 million) electrical steel production unit at its industrial plant in Mardyck, near Dunkirk. Representing the companys largest capital investment in Europe over the last decade, the advanced complex has successfully rolled its first commercial coils.(Source: gmk.center)
Italy Local Manufacturer Adoption
Italys green steel market grows as local manufacturers adopt cleaner technology to meet strict European Union environmental goals and lower carbon output. Strict European Union climate regulations and rising carbon pricing under the Emissions Trading System (ETS) push Italian steel producers to cut greenhouse gases. Increased regional investments in solar and wind power supply the clean electricity needed for sustainable steelmaking, and hydrogen-based reduction trials further support the growth.
- For instance, in October 2025, Stahl-Holding-Saar (SHS) secured €1.7 billion ($1.85 billion) in funding to officially launch its massive green hydrogen steelmaking initiative, the Power4Steel project, in Saarland.(Source: fuelcellsworks.com)
Germany National Decarbonization Commitments
The German green steel market is primarily driven by strict European Union climate regulations, national decarbonization commitments, and rising demand for low-carbon materials from the automotive and construction sectors. Key domestic industries like construction and automotive increasingly require sustainable, certified building materials and low-carbon components such as DGNB and LEED standards, which drives the growth of the market.
- For instance, in February 2026, the German Federal Ministry for Economic Affairs and Energy (BMWK) confirmed €322 million in additional state funding for Salzgitter AG’s primary green steel transformation program, the SALCOS (Salzgitter Low CO₂-Steelmaking) project.(Source: gmk.center)
Latin America Green Steel Market Export Expansion
The Latin America green steel market size was estimated at USD 3.91 billion in 2025 and is projected to reach USD 29.26 billion by 2035, growing at a CAGR of 22.30% from 2026 to 2035.Latin America held a market share of 5% in 2025, driven by the improved and high availability of renewable energy supply, which helps in increased production of green steel, alternating to the use of traditional carbon steel, which supports growth. The presence of large production creates great and vast opportunities for the export of green materials, leading to the increased global presence of the region. The advanced and modern industrial infrastructure in the region further supports the growth and expansion of the market.
Brazil: Abundant Renewable Energy
Brazils green steel market is growing due to its abundant renewable energy, high-grade iron ore reserves, and rising global demand for low-carbon industrial materials. Brazil has a clean energy grid featuring widespread hydropower, wind, and solar capacity, which lowers the cost of producing green hydrogen needed for low-emission hydrogen-direct reduced iron steelmaking. International markets are shifting toward carbon-differentiated trade, positioning Brazil as a potential global hub for cost-effective green iron and low-carbon exports.
Argentina: Growing Investments
The green steel market in Argentina is growing significantly, driven by Emerging investments, such as Sidersas greenfield electric arc furnace project, which represent pivotal shifts toward modernized, low-carbon manufacturing infrastructure. Increasing international pressure, carbon border mechanisms, and supply-chain sustainability requirements from automotive and construction sectors drive the long-term shift away from traditional blast furnaces.
Middle East and Africa Green Steel Market New Low Carbon Facilities
The Middle East and Africa green steel market size was estimated at USD 4.69 billion in 2025 and is projected to reach USD 34.58 billion by 2035, growing at a CAGR of 22.11% from 2026 to 2035.The Middle East and Africa held a market share of 6% in 2025, driven by high-end green hydrogen projects in the region, which help in rapid expansion of the market and shift towards use of cleaner and greener products, aligning with the regions sustainability initiatives. The development of advanced and new low-carbon steel facilities in the region is an emerging factor for growth as it increases the domestic presence and fulfils the demand. The government investments and diversification strategies further support and contribute largely to the growth and expansion of the market.
- For instance, in August 2025, Meranti Steel finalized its technological roadmap for its upcoming green iron project in Oman, opting to use a blended mix of natural gas and green hydrogen as the primary reducing agents. This dual-fuel transition strategy allows the facility to commence low-carbon industrial manufacturing immediately while regional green hydrogen production infrastructures scale up to commercial volumes.(Source: fuelcellsworks.com)
Saudi Arabia Saudi Vision 2030 and Mega-Projects
Saudi Arabia’s green steel market is projected to grow, driven by national sustainability strategies and massive infrastructure demands. High-profile developments like NEOM, the Red Sea Project, and Riyadh Metro require millions of tonnes of structural and sustainable building materials, which drives demand for green steel in the market. Accelerated adoption of hydrogen-based Direct Reduced Iron technology replaces traditional carbon-heavy blast furnaces, supported by heavy investments in green hydrogen in the region.
UAE Government Initiatives and Climate Targets
The UAE green steel market is growing rapidly due to national net-zero commitments, major investments in green hydrogen, and surging demand for low-carbon construction materials. The UAE’s Net Zero by 2050 strategic initiative and Abu Dhabi’s Low Carbon Hydrogen Policy mandate heavy industry decarbonization. Plans to scale up clean hydrogen production provide the clean fuel necessary to replace natural gas in iron extraction, which is a key part of the national hydrogen strategy.
- For instance, in May 2026, the UAE-based steel companies CIM Steel Industry LLC, Rhino Steel Industries LLC, and Metal Care Center Factory LLC partnered to launch a €110 million integrated steel manufacturing hub in Umm Al Quwain. The projects combined production and processing capacity emphasizes energy-efficient operations, material recycling, and zero-waste green steel manufacturing principles.(Source: www.steelorbis.com)
Recent Development
- In October 2025, Swedish green steel firm Stegra announced a new €975 million ($1.1 billion) funding round, aiming to finish building what will be the world’s first large-scale green steel plant. Situated in Boden, northern Sweden, the plant will use renewable hydrogen to substitute coal in steel manufacturing, a sector thats particularly challenging to decarbonize.(Source:esgnews.com)
- In November 2025, the environmental think-tank iFOREST, in partnership with the Indian Steel Association, launched Indias first ESG report and unified emissions tracking tool dedicated entirely to the steel sector. Designed to streamline corporate disclosures and unlock global climate finance, this initiative establishes a standardized framework to combat the high carbon intensity of domestic manufacturing.(Source:www.livemint.com)
Competitive Analysis
The growing manufacturers and suppliers are collaborating for commercializing and for adoption of sustainable products due to rising environmental concerns, and competition between cheaper carbon steel manufacturers is also a major growing competition factor
- In March 2026, the CSIRO announcement reveals a breakthrough India-Australia Green Steel Research Partnership that successfully demonstrated a world-first commercial trial using agricultural waste to decarbonise steelmaking. Conducted at a Jindal Steel plant in Odisha, the project partially replaces coal with locally sourced rice husk pellets to generate synthesis gas for iron ore reduction.(Source: www.csiro.au)
- In July 2025, the ETEnergyworld article outlines a critical turning point in the A$105 billion iron ore trade between Australia and China. During a bilateral meeting in Shanghai, Australian Prime Minister Anthony Albanese advocated for closer bilateral cooperation on green steel and steel decarbonisation.(Source: energy.economictimes.indiatimes.com)
- In November 2025, South Korean steelmaker POSCO Holdings Inc. partnered with Australia’s Heavy Industry Low-carbon Transition Cooperative Research Centre to build a "collective voice" aimed at supporting price premiums for low-carbon emissions iron and steel products, boosting green steel.(Source: www.spglobal.com)
Top players in the Green Steel Market & Their Offerings
| Company | Company Type/Position | Major Headquarters | Geographic Presence | Green Steel Offerings | Key Offering/Strength |
| SSAB AB | Leading low-carbon steel manufacturer | Stockholm, Sweden | Europe, North America | Fossil-free steel, high-strength steel, and sustainable steel solutions for automotive, construction, and heavy equipment | Pioneer in fossil-free steel production using hydrogen-based technology |
| ArcelorMittal S.A. | Global integrated steel producer | Luxembourg City, Luxembourg | Europe, North America, Asia Pacific, South America | Low-carbon steel, recycled steel, and carbon-reduced flat and long steel products | Strong decarbonization strategy supported by hydrogen and electric arc furnace technologies |
| thyssenkrupp Steel Europe AG | Integrated steel manufacturer | Duisburg, Germany | Europe, North America, Asia Pacific | Green flat steel, low-carbon steel, and sustainable steel solutions | Advanced hydrogen-based steelmaking and large-scale decarbonization initiatives |
| H2 Green Steel | Green steel producer | Stockholm, Sweden | Europe | Hydrogen-based green steel for automotive, industrial, and construction applications | Dedicated green steel production using renewable energy and green hydrogen |
| POSCO Holdings Inc. | Global steel and materials company | Pohang, South Korea | Asia Pacific, Europe, North America | Low-carbon steel, high-performance steel, and hydrogen-based steel products | Strong investment in hydrogen-based steelmaking and carbon-neutral production technologies |
Other Top Players Are
- China Baowu Steel Group (China)
- Tata Steel (India)
- Nucor Corporation (U.S.)
- Nippon Steel Corporation (Japan)
- Voestalpine AG (Austria)
- Salzgitter AG (Germany)
- Emirates Steel Arkan (UAE)
- JFE Steel Corporation (Japan)
- JSW Steel (India)
- Outokumpu Oyj (Finland)
- Boston Metal (U.S.)
- Liberty Steel Group (UK/Global)
- Swiss Steel Group (Switzerland)
- Jindal Steel & Power (India)
- Tenaris (Luxembourg)
Segments Covered
By Application
- Construction
- Residential Buildings
- Commercial Buildings
- Industrial Buildings
- Bridges
- Tunnels
- Public Infrastructure
- Automotive
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
- Heavy-Duty Vehicles
- Automotive Components
- Aerospace
- Commercial Aircraft
- Military Aircraft
- Space Systems
- Aircraft Components
- Energy
- Wind Energy
- Solar Energy
- Hydropower
- Nuclear Energy
- Oil & Gas
- Power Transmission
- Consumer Goods
- Home Appliances
- Furniture
- Packaging
- Sports Equipment
- Household Products
By End Use
- Building Materials
- Structural Steel
- Roofing Systems
- Reinforcement Products
- Steel Panels
- Transportation
- Automotive Manufacturing
- Railway Equipment
- Marine
- Aviation
- Machinery
- Industrial Machinery
- Agricultural Machinery
- Mining Equipment
- Construction Equipment
- Infrastructure
- Roads
- Bridges
- Airports
- Ports
- Utilities
- Electronics
- Consumer Electronics
- Electrical Equipment
- Industrial Electronics
- Telecommunications Equipment
By Production Method
- Electric Arc Furnace (EAF)
- Scrap-Based Electric Arc Furnace
- Direct Reduced Iron (DRI)-Based EAF
- Hybrid Electric Arc Furnace
- Hydrogen Reduction
- Green Hydrogen Direct Reduction
- Renewable Hydrogen Reduction
- Electrolysis-Based Hydrogen Reduction
- Direct Reduced Iron (DRI)
- Natural Gas-Based DRI
- Hydrogen-Based DRI
- Hot Briquetted Iron (HBI)
- Recycling
- Ferrous Scrap Recycling
- Industrial Steel Scrap Recycling
- End-of-Life Steel Recycling
- Closed-Loop Recycling
- Biomass Reduction
- Biomass Gasification
- Biomass-Derived Syngas Reduction
By Material Type
- Steel
- Carbon Steel
- Low Carbon Steel
- Medium Carbon Steel
- High Carbon Steel
- Structural Steel
- Alloys
- Stainless Steel
- High-Strength Low-Alloy (HSLA) Steel
- Tool Steel
- Specialty Alloys
- Reinforced Steel
- Reinforcing Bars (Rebar)
- Welded Wire Mesh
- Prestressing Steel
- Flat Steel
- Hot Rolled Steel
- Cold Rolled Steel
- Galvanized Steel
- Coated Steel
- Electrical Steel
- Long Steel
- Wire Rod
- Steel Bars
- Structural Sections
- Rails
- Merchant Bars
By Technology
- Carbon Capture Utilization (CCU)
- Post-Combustion Carbon Capture
- Pre-Combustion Carbon Capture
- Carbon Mineralization
- Carbon Utilization Technologies
- Green Steel Market Integration
- Renewable Energy Integration
- Green Power Purchase Agreements
- Green Supply Chain Platforms
- Carbon Credit Integration
- Smart Manufacturing
- Artificial Intelligence
- Industrial Internet of Things (IIoT)
- Robotics & Automation
- Machine Learning
- Real-Time Process Monitoring
- Advanced Metallurgy
- Low-Carbon Alloy Development
- High-Efficiency Smelting
- Secondary Refining
- Advanced Casting Technologies
- Digital Twin Technology
- Plant Digital Twins
- Production Line Digital Twins
- Predictive Asset Management
- Process Simulation
- Virtual Commissioning
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.