
Advanced Polymer Composites Market Size, Share, Trends and Forecast 2026 to 2035
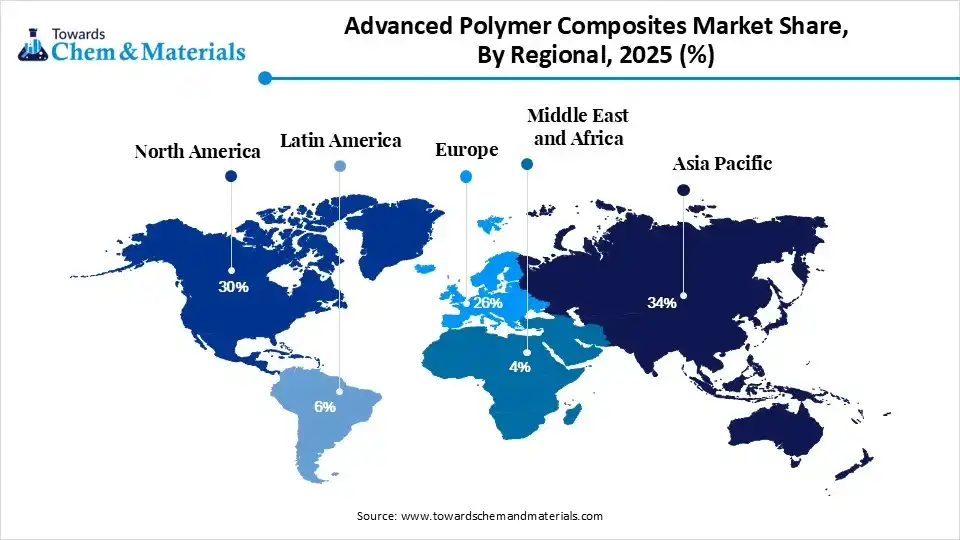
The global advanced polymer composites market size was valued at USD 12.75 billion in 2025, is estimated to reach USD 13.87 billion in 2026, and is projected to reach USD 29.50 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 8.75% over the forecast period from 2026 to 2035.Asia Pacific dominated the advanced polymer composites market with the largest revenue share of 34% in 2025 and is expected to grow at the fastest CAGR of 8.90% during the forecast period. In terms of volume, the advanced polymer composites market is projected to grow from 3.88 million tons in 2025 to 8.34 million tons by 2035. growing at a CAGR of 7.95% from 2026 to 2035. The emergence of lightweight yet durable materials has shaped the industry path in recent years. The assessment of major sectors like aerospace and automobiles is heavily generating value-added opportunities for industry participants in the current era as per the industry analysis. 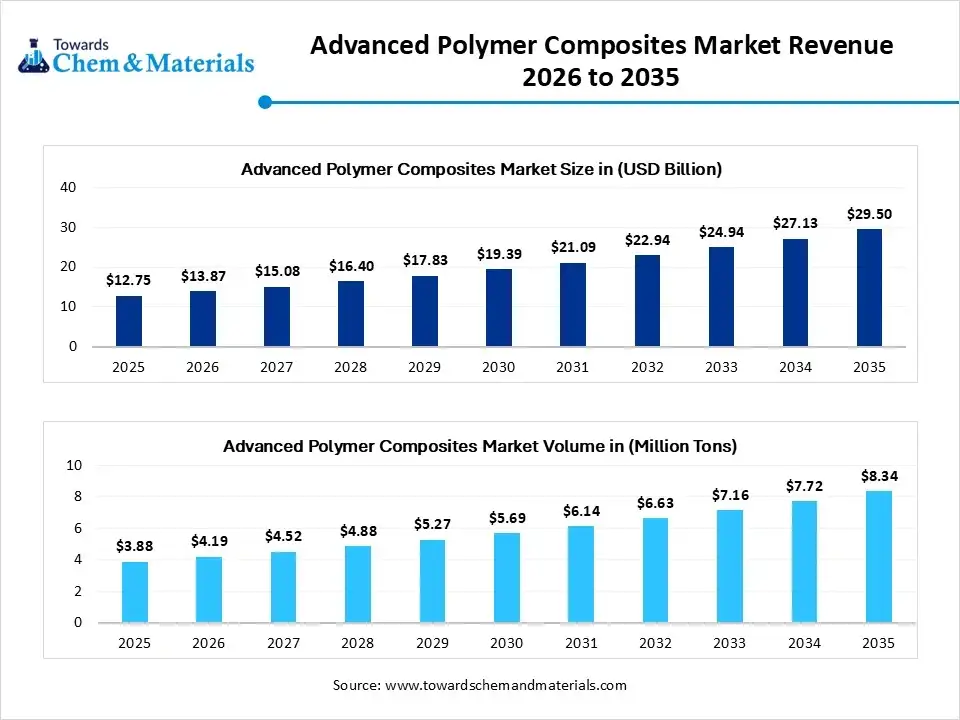
Market Highlights
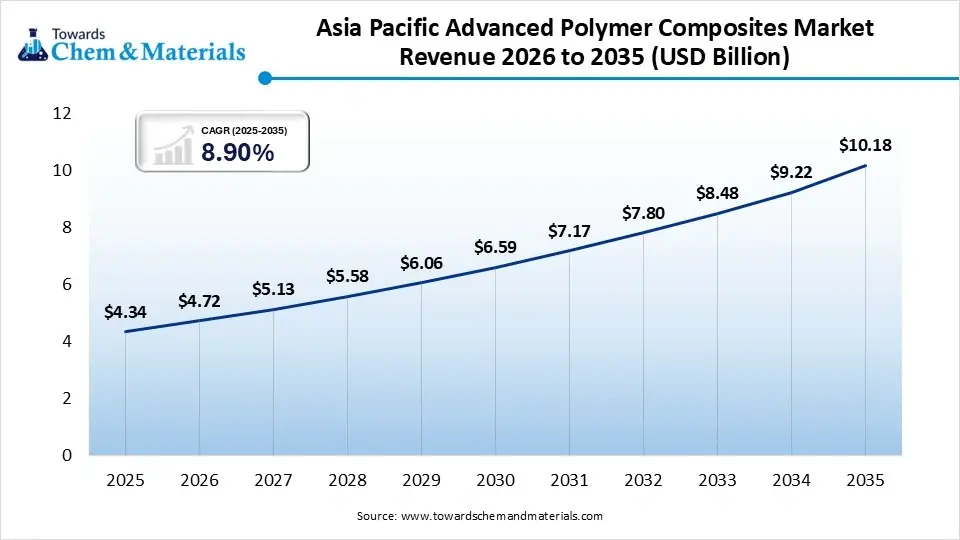
- By region, Asia Pacific dominated the market with a share of 34% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 10.02% in the forecast period, due to heavy and advanced manufacturing facilities.
- By region, North America held 30% market share in 2025, owing to continuous investment in aerospace, defense, electric vehicles, and advanced manufacturing technologies.
- By material, the resin segment dominated the market with 44% share in 2025, as resin acts as the binding material that holds reinforcing fibers together and provides structural strength.
- By material, the fiber segment held a 41% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 9.26% in the forecast period, owing to industries are increasingly focusing on stronger and lighter reinforcement materials.
- By application, the aerospace & defense segment dominated the market with 31% share in 2025, owing to aircraft manufacturers requiring lightweight materials with excellent strength and durability.
- By application, the automotive segment held a 27% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 9.64% in the forecast period, owing to vehicle manufacturers working to reduce weight and improve energy efficiency.
From Normal Application to Aerospace
The integration into major global fields such as aerospace, automobiles, and satellite communications, the advanced polymer composites have gained global attention in recent years. Also, the emergence of durable and technology-driven materials has actively pushed the industry's potential in the past few years. Moreover, the sudden shift towards eco-friendly, low-cost, and recycled materials is likely to lead to industry sales during the projected time period. Even manufacturers are heavily investing in their R&D practices with the adoption of modern technology and robotics as per the recent survey.
- For instance, in February 2025, The Mallinda Inc has unveiled the latest resin. Also, it is a hot melt resin and is specially designed for recyclability of high-performance composites, as per the company's claim. Also, a newly launched resin called the Vitrimax versatile hot melt resin.(Source: interplasinsights.com)
The development of innovative materials has positively responded to industry standards, where manufacturers and their advanced facilities become key elements. Also, practical engineering operations have been observed, which are making the industry more diverse and practical. Major regions such as Asia Pacific and North America are actively establishing and investing in local production initiatives. Also, the major raw material importers are trying to reduce heavy and costly imports in the current period.
Global Investment Flow for the Advanced Polymer Composites Market 2026
Companies are investing in latest composite manufacturing facilities to meet growing demand from automotive, aerospace, & renewable energy industries.Manufacturers are expanding research activities to develop lighter, stronger, and more sustainable composite materials for future industrial applications.
- For instance, in June 2026, Nawah established its latest plant of advanced composite materials in the United States with a $10 million investment as per the published report.(Source: www.jeccomposites.com)
Strategic collaborations and facility expansions are helping improve production capacity, supply chain reliability, and global market reach.
Advanced Polymer Composites Market Trends
- The need for lightweight materials has offered substantial growth prospects for the manufacturing firms. Major manufacturers in the automobile sector are seen demanding these types of lightweight materials due to the fuel efficiency and lower maintenance costs.
- The quick move towards eco-friendly and recyclable materials has enabled high return ventures for manufacturers. Also, several governments have implemented different bans on above-micron plastics in the current period as per the recent observations.
- The greater need and usage from the aerospace and defense sector is expected to enhance market participation for the producers. In both sectors, higher durability and lower maintenance are key needs which are likely to be easily fulfilled by the advanced composites manufacturers in the coming years.
Report Scope
| Report Attributes | Details |
| Market Size in 2026 | USD 13.87 Billion/ 4.19 Million Tons |
| Expected Size in 2035 | USD 29.50 Billion/ 8.34 Million Tons |
| Growth Rate | CAGR of 8.75% |
| Forecast Period | 2025-2035 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Material, By Application, By Region |
| Key Companies Profiled | Toray Industries, Hexcel Corporation, Toray Industries, Hexcel Corporation, Syensqo, Teijin Limited, Owens Corning, SGL Carbon, Mitsubishi Chemical Group, Gurit, Arkema |
High-performance Materials Through Higher Technologies
The industry is moderately moving toward automated manufacturing and high-performance composite technologies. Also, companies are introducing automated fiber placement, advanced resin systems, and digital production monitoring to improve manufacturing accuracy and product consistency. In the current period, the manufacturers are developing recyclable composite materials and faster curing technologies to improve sustainability and production efficiency.
Supply Chain Analysis of the Advanced Polymer Composites Market
Production & Processing
- Composite manufacturing combines reinforcing fibers with a polymer matrix through processes such as prepreg layup, resin transfer molding, compression molding, pultrusion and filament winding.
- They layer these wet sheets into specific shapes and depending on the material and process, composite laminates may be consolidated and cured using autoclaves, ovens, presses, resin-transfer processes or other manufacturing methods
- Toray Industries: Toray Industries supplies carbon fiber, prepreg, fabrics and composite materials for aerospace, defense, sports and industrial applications
- Key players: Solvay, Hexcel Corporation, Teijin Limited, and Owens Corning
Quality Testing and Certification
- Testing advanced composites means pushing the cured materials to their absolute breaking points inside specialized stress laboratories.
Technicians blast parts with ultra-high frequency soundwaves to listen for microscopic hidden air pockets or loose internal glue layers. - Earning a structural safety stamp proves these high-strength materials can survive severe temperature shifts and violent turbulence without fracturing.
- Intertek: Intertek is an international key player that primarily operates an advanced materials laboratory.
- Key agencies: Bureau Veritas, TÜV SÜD, Element Materials Technology, Exova, and Applus+
Distribution to Industrial Users
- Distributing high-tech composites means getting delicate, pre-soaked fiber sheets and cured parts to factories in perfect condition.
- Logistics teams use refrigerated trucks to stop raw, wet resins from curing too early during transit. They coordinate closely with production floors to deliver materials exactly when needed for assembly lines.
- Avient: Avient Corporation is a premier global distributor and formulator of specialized polymer materials.
- Key players: Brenntag, Univar Solutions, Biesterfeld, and Chase Plastics
Advanced Polymer Composites Market Regulatory Landscape: Regulations
| Country Region | Regulatory Body | Key Regulations | Focus Areas |
| United States | Federal Aviation Administration (FAA) | Federal Aviation Regulations [14 CFR Section 25.603]: Enforces a strict legal mandate for commercial aircraft builds. | Aerospace Structural Integrity: Streamlining safety checks and non-destructive ultrasonic scans for complex, automated carbon fiber layouts used in next-generation commercial planes and defense aircraft. |
| Europe | European Union Aviation Safety Agency (EASA) | REACH Regulation [(EC) No 1907/2006] Annex XVII Entry 69: Imposes a strict consumer ban on the chemical. | Material Lifecycle Accountability: Driving automotive and aerospace plants to design parts that can be separated and recycled easily, cutting down on the volume of unrecyclable thermoset scrap hitting landfills. |
| China | Ministry of Industry and Information Technology (MIIT) | Civil Aviation Regulations of China [CCAR Part 25 Section 25.603]: Replicates strict structural aviation rules, legally requiring deep-dive safety evaluations for all domestic commercial airplane components built out of advanced resin-fiber systems. | Domestic Quality Stabilization: Standardizing manufacturing protocols across regional factories to ensure that massive batches of raw carbon fiber strands maintain perfectly consistent strength metrics. |
Advanced Polymer Composites Market Dynamics
Driver
Flexible Material Dominance
“Demand is supported by applications requiring high specific strength, stiffness, corrosion resistance and lightweight construction, particularly in aerospace, automotive, wind energy, marine and infrastructure projects. In the current period, aerospace, automotive, wind energy, marine, and construction companies are replacing traditional metals with advanced polymer composites to improve product performance and reduce overall weight. Lightweight materials help lower fuel consumption, improve energy efficiency, and support sustainability goals. Moreover, manufacturers are investing in advanced production technologies to increase composite use in large-scale applications.
Restraint
High Production Cost Restrictions
The high production cost is expected to hinder industry growth during the forecast period. Also, advanced fibers and specialty resins are more expensive than conventional materials, making finished composite products costly for many industries. In recent years, the manufacturing process has also required advanced equipment, skilled workers, and strict quality control, increasing overall production expenses.
Opportunity
Electric Vehicle and Renewable Energy Emergence
The industries continue developing electric vehicles, renewable energy projects, and next-generation aircraft, which is likely to create lucrative opportunities during the projected time period. Additionally, manufacturers are focusing on recyclable composites, bio-based resins, and automated production methods to improve sustainability and reduce manufacturing costs. Moreover, governments are supporting clean transportation and green infrastructure projects, creating new demand for lightweight composite materials.
Segmental Insights
Material Insights
The resin segment accounted for 44% of market revenue in 2025, the largest share among the material categories, as resin acts as the binding material that holds reinforcing fibers together and provides structural strength. In recent years, epoxy, polyester, and vinyl ester resins have been widely used because they offer excellent durability, corrosion resistance, and strong mechanical performance. These resins are suitable for aerospace, automotive, marine, construction, and wind energy applications.Thermoset systems such as epoxy, polyester and vinyl ester remain important matrix materials, while thermoplastics such as PEEK, PPS, PEI, polyamide and polypropylene support applications requiring rapid processing, recyclability or thermoplastic performance characteristics
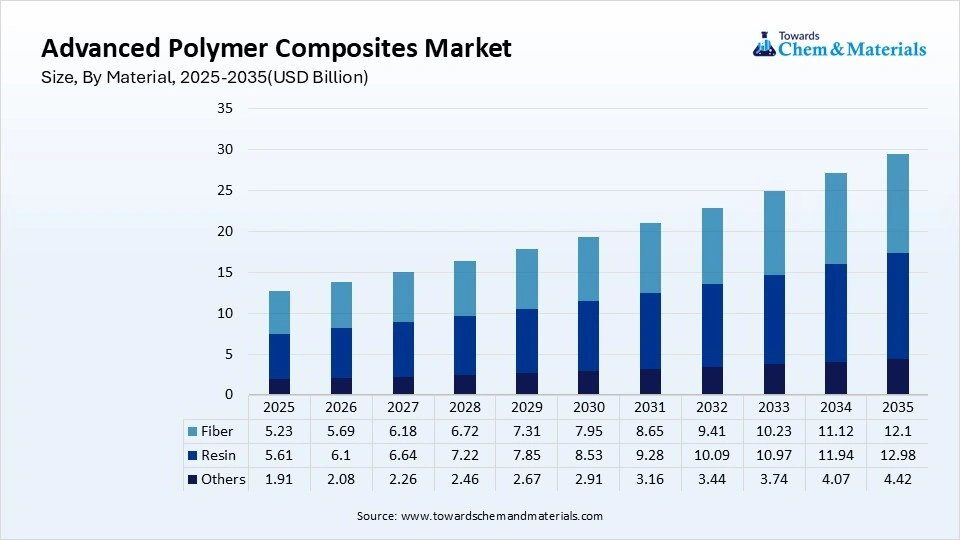 The fiber segment held a 41% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 9.26% in the forecast period, owing to industries are increasingly focusing on stronger and lighter reinforcement materials. Carbon fiber, glass fiber, and aramid fiber help improve product strength while reducing overall weight. In the current period, growing demand for electric vehicles, aircraft, wind turbine blades, and sporting equipment is increasing fiber consumption.
Advanced Polymer Composites Market Share, By Material, 2025 (%)
| By Material | Revenue Share, 2025 (%) |
| Resin | 44% |
| Fiber | 41% |
| Others | 15% |
Application Insights
The aerospace & defense segment dominated the market with 31% share in 2025, owing to aircraft manufacturers require lightweight materials with excellent strength and durability. Advanced polymer composites help reduce aircraft weight, improve fuel efficiency, and increase operational performance. In recent years, both commercial and military aircraft programs have increased the use of composite structures in fuselages, wings, interiors, and engine components.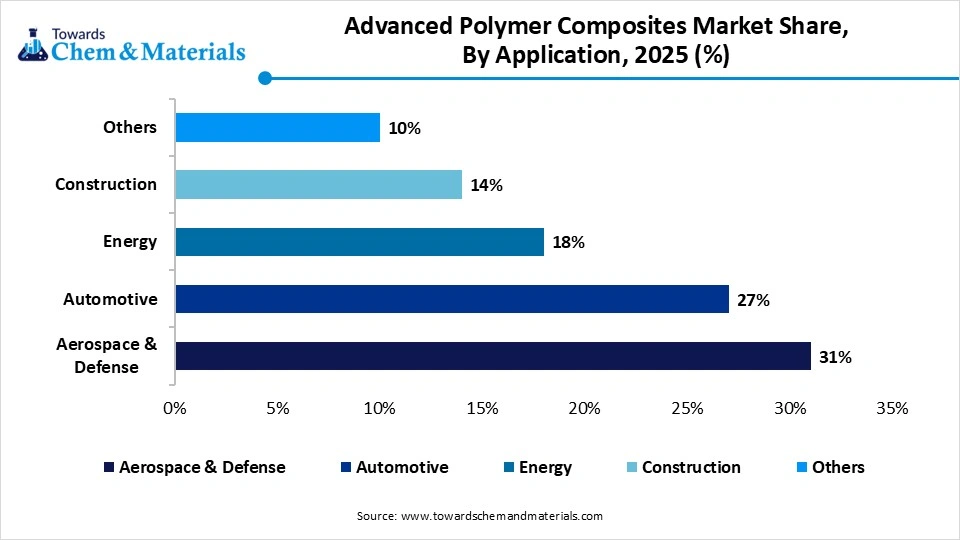
The automotive segment held a 27% market share in 2025 and is expected to be the fastest-growing in the market, with a CAGR of 9.64% in the forecast period, owing to vehicle manufacturers working to reduce weight and improve energy efficiency. In the current period, electric vehicle production is increasing the demand for lightweight composite materials that help extend battery range and improve vehicle performance. Furthermore, advanced polymer composites provide better corrosion resistance and design flexibility than traditional metals.
Advanced Polymer Composites Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Aerospace & Defense | 31% |
| Automotive | 27% |
| Energy | 18% |
| Construction | 14% |
| Others | 10% |
Regional Analysis
How did Asia Pacific Dominated the Advanced Polymer Composites Market in 2025?
The Asia Pacific advanced polymer composites market size was estimated at USD 4.34 billion in 2025 and is projected to reach USD 10.18 billion by 2035, growing at a CAGR of 8.90% from 2026 to 2035. Asia Pacific dominated the market with a share of 34% in 2025 and is expected to be the fastest-growing region in the market, with a CAGR of 10.02% in the forecast period, due to heavy and advanced manufacturing facilities. Also, the regional countries across the region continue expanding production of automobiles, electronics, aerospace components, and wind energy equipment, creating strong demand for advanced composite materials. Moreover, lower manufacturing costs, improving production technologies, and supportive industrial policies encourage both domestic and international investments.
China
China is an important Asia Pacific market because of its automotive, renewable-energy, aerospace and industrial manufacturing base. Also, the country is expanding composite material production while improving domestic supply chains. Moreover, growing industrial output and increasing demand for lightweight materials continue supporting market growth across multiple end-use industries.
Japan
The country is expanding composite material production while improving domestic supply chains, and growing industrial output and increasing need for lightweight materials continue supporting market growth across multiple end-use industries. Also, the collaboration between industrial companies to develop environmentally friendly production methods in the country nowadays.
Advanced Polymer Composites Market Evaluation in North America
The North America advanced polymer composites market size was estimated at USD 3.83 billion in 2025 and is projected to reach USD 9.00 billion by 2035, growing at a CAGR of 9.96% from 2026 to 2035. North America held 30% market share in 2025, owing to continuous investment in aerospace, defense, electric vehicles, and advanced manufacturing technologies. The region benefits from high research spending, strong industrial capabilities, and early adoption of advanced materials across multiple industries. Moreover, companies are focusing on sustainable composite solutions and automated production systems to improve efficiency.
United States
The United States leads the regional industry through strong aerospace, defense, automotive, and renewable energy industries, while major investments in next-generation aircraft, electric vehicles, and advanced manufacturing continue increasing demand for high-performance composite materials. Continuous innovation and strong research activities further support industry expansion as per the expectations.
Canada
Canada is strengthening its market through growing aerospace manufacturing, clean energy projects, and industrial innovation, while the country is increasing the use of advanced polymer composites in transportation and renewable energy applications. Also, government support for sustainable manufacturing and advanced material research is creating new opportunities for market growth.
Europe Enzyme Industry Conditions
The Europe advanced polymer composites market size was estimated at USD 3.32 billion in 2025 and is projected to reach USD 7.82 billion by 2035, growing at a CAGR of 8.94% from 2026 to 2035. Europe held a 26% market share in 2025, owing to industries across the region focusing on sustainable manufacturing, lightweight transportation, and renewable energy development. Also, the automotive, aerospace, wind energy, and industrial equipment manufacturers are increasing the use of advanced polymer composites to improve efficiency and reduce emissions. Moreover, strict environmental regulations encourage companies to adopt advanced materials that support long-term sustainability goals.
Germany
Germany plays a major role in Europe's growth because of its strong automotive engineering, industrial manufacturing, and aerospace industries and manufacturers are increasing the use of lightweight composite materials to improve vehicle efficiency and industrial performance. In addition, the continuous investment in advanced manufacturing technologies further supports market development.
Italy
Italy heavily contributes to regional growth through its expanding automotive, marine, industrial equipment, and high-performance manufacturing sector, while companies are adopting advanced polymer composites to improve product quality and reduce overall weight. Furthermore, lightweight engineering materials are likely to present better business ideas as per the recent survey.
Advanced Polymer Composites Market Survey in Latin America
The Latin America advanced polymer composites market size was estimated at USD 0.77 billion in 2025 and is projected to reach USD 1.92 billion by 2035, growing at a CAGR of 10.69% from 2026 to 2035. Latin America held a 5% market share in 2025 as growing investments in automotive production, renewable energy, construction, and industrial manufacturing. In the current period, manufacturers are increasing the use of lightweight composite materials to improve product performance and durability. Also, the growing investments in automotive production, renewable energy, construction, and industrial manufacturing. In the current period, manufacturers are increasing the use of lightweight composite materials to improve product performance and durability.
Brazil
Brazil is the largest contributor in the region nowadays owing to its strong aerospace, automotive, wind energy, and industrial manufacturing sectors. Also, the country continues expanding the use of advanced polymer composites to improve fuel efficiency, product strength, and operational performance. Growing renewable energy investments and industrial modernization are also supporting demand for advanced composite materials.
Argentina
Argentina is actively strengthening the regional market through its expanding automotive, aerospace, and electronics manufacturing industries while international manufacturers continue investing in production facilities across the country, increasing the demand for lightweight engineering materials. Moreover, the country's strong export-oriented manufacturing sector and improving industrial capabilities are supporting wider adoption of advanced polymer composites.
Middle East and Africa Methanol Sector Observation
The Middle East and Africa advanced polymer composites market size was estimated at USD 0.51 billion in 2025 and is projected to reach USD 1.33 billion by 2035, growing at a CAGR of 10.06% from 2026 to 2035. The Middle East and Africa held a 5% market share in 2025, as investments increase in infrastructure, renewable energy, oil and gas, and transportation projects. In recent years, industries have started using advanced polymer composites because of their corrosion resistance, lightweight properties, and long service life. Moreover, governments are supporting industrial diversification and modern manufacturing to reduce dependence on traditional sectors.
Saudi Arabia
The country is heavily investing in industrial diversification, advanced manufacturing, and renewable energy projects. The increasing use of advanced polymer composites in construction, oil and gas equipment, transportation, and infrastructure is Industrial diversification, infrastructure and renewable-energy projects can create additional applications for composite materials in the Saudi market. These investments are creating steady demand for high-performance composite materials.
South Africa
South Africa supports regional growth through its mining, transportation, renewable energy, and industrial manufacturing sectors. Also, the country is gradually adopting advanced polymer composites to improve equipment performance, reduce maintenance needs, and increase operational efficiency. Also, growing industrial modernization is expected to support upcoming demands.
Competitive Analysis
Major suppliers compete through composite-material development, production capacity, application qualification, customer relationships and manufacturing technologies.Toray has been actively advancing and improving its production facilities. Also, the company has showed their next generation composite technologies recently at JEC World 2025. The motive behind these showcases is to promote sustainability through collaboration and technology.
- Hexcel continues to expand its advanced-composites portfolio across carbon fiber, prepregs, resin systems, honeycomb and engineered composite structures.
Recent Development
- In July 2026, Toray introduced its latest fast-cure composites. Also, these composites are specifically designed for aerospace manufacturing, which is known as Toray’s 3960 FC. Moreover, this curing system can reduce cure time by 45% with improvement of performance standards as per the published report.(Source: www.plasticstoday.com)
Top Vendors in the Advanced Polymer Composites Market & Their Offerings
| Company | Company Type/Position | Major Headquarters | Geographic Presence | Offerings | Key Strength |
| Toray Industries | Global Fiber Giant | Tokyo, Japan | Dominant manufacturing hubs across Asia, North America, and Europe, supplying global supply chains. | Premium carbon fiber strands, pre-impregnated (prepreg) sheets, and woven fabric matrices for structural builds. | Unmatched production capacity and long-term contracts as the primary carbon fiber supplier for mainline commercial jets. |
| Hexcel Corporation | Structural Materials Leader | Connecticut, USA | Heavy industrial presence in North America and Europe, targeting aerospace and defense sectors. | Advanced honeycombs, lightweight carbon fiber prepregs, structural adhesives, and engine | World-class expertise in complex, lightweight core technologies designed explicitly to handle extreme aviation stress. |
| Syensqo | Advanced Chemistry Innovator |
Brussels, Belgium | Deep operational and research footprint stretching across Europe, the Americas, and Asia-Pacific. | High-performance thermoplastic composites, specialized curing resins, and structural bonding tapes. | Pioneer in highly recyclable thermoplastic resins that allow factories to stamp out lightweight auto parts rapidly. |
- Toray Industries
- Hexcel Corporation
- Syensqo
- Teijin Limited
- Owens Corning
- SGL Carbon
- Mitsubishi Chemical Group
- Gurit
- Arkema
Market Segments
By Material
- Resin
- Thermoset Resin
- Epoxy
- Polyester
- Vinyl Ester
- Phenolic
- Others
- Thermoplastic Resin
- PEEK
- PPS
- PEI
- Polyamide (PA)
- Polypropylene (PP)
- Others
- Thermoset Resin
- Fiber
- Carbon Fiber
- Glass Fiber
- Aramid Fiber
- Basalt Fiber
- Natural Fiber
- Others
- Others
- Fillers
- Core Materials
- Additives
- Nanomaterials
By Application
- Aerospace & Defense
- Commercial Aircraft
- Military Aircraft
- Spacecraft
- UAVs
- Automotive
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
- Motorsports
- Energy
- Wind Energy
- Oil & Gas
- Hydrogen
- Power Transmission
- Construction
- Infrastructure
- Commercial Buildings
- Residential Buildings
- Bridges
- Others
- Marine
- Sporting Goods
- Medical
- Consumer Electronics
By Region
- North America
- Europe
- Asia Pacific
- Middle East & Africa
- Latin America
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.