Find the Right Market Report
Search thousands of industry reports, market insights, and research studies in one place.
Not sure where to start? Try one of these:
The global high-performance catalyst market size was valued at USD 43.18 billion in 2025, is estimated to reach USD 46.14 billion in 2026, and is projected to reach USD 83.76 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 6.85% over the forecast period from 2026 to 2035.Asia Pacific dominated the high-performance catalyst market with the largest revenue share of 43% in 2025 and is expected to grow at the fastest CAGR of 6.97% during the forecast period. In terms of volume, the high-performance catalyst market is projected to grow from 8.15 million tons in 2025 to 14.53 million tons by 2035. growing at a CAGR of 5.95% from 2026 to 2035. The market growth is driven by strict environmental rules in place, and the shift toward cleaner fuels is really pushing the use of newer catalytic technologies. At the same time, more petrochemical production is happening, and there is also a growing need for more careful pharmaceutical manufacturing, so the industry wants high-performance catalysts that can boost overall process efficiency, cut emissions, and support more sustainable industrial work.
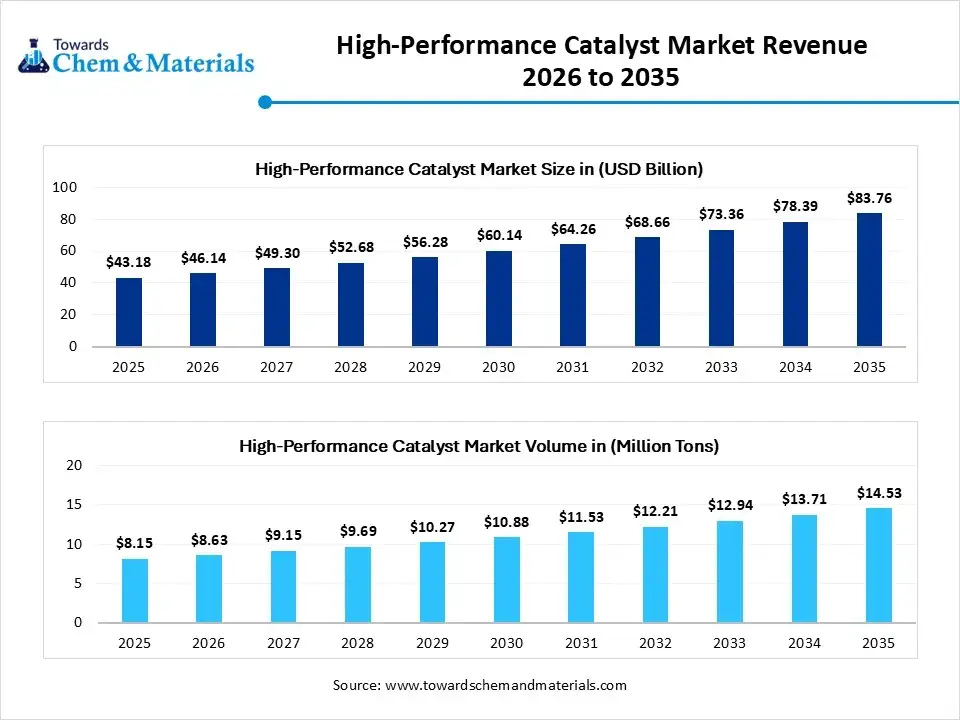
Leading players like BASF SE, Johnson Matthey, Honeywell, and Topsoe A/S are prominent in the industrial catalysts market and are investing heavily in sustainable technology and advanced catalysts. Market consolidation is gaining momentum as businesses look to acquire others to bolster green tech portfolios, access key supply chains, and power up circular economy solutions. Market growth is also being boosted by government measures, including tougher emission standards and subsidies for low-carbon industrial processes.
For example, the Government of India has recently amended and strengthened its legally binding Greenhouse Gas Emission Intensity (GEI) Reduction Rules and the implementation of the Carbon Credit Trading Scheme (CCTS) for reducing emissions from industries. At the same time, innovations in the field of Green Hydrogen using Nano-catalysts and Electro-catalysts are also being supported by the Department of Science and Technology in India.
| Report Attributes | Details |
| Market Size in 2025 | USD 43.18 Billion/ 8.15 Million Tons |
| Expected Size in 2035 | USD 83.76 Billion/ 14.53 Million Tons |
| Growth Rate | CAGR of 6.85% |
| Base Year of Estimation | 2025 |
| Forecast Period | 2025-2035 |
| Dominant Region | North America |
| Segment Covered | By Market Type, By Application, By End-User, By Active Component, By Region |
| Key Companies Profiled |
Arkema, Johnson Matthey, BASF, Zeolyst International, SABIC, Albemarle, Honeywell, LyondellBasell, Haldor Topsoe Ashland, Clariant, Shell, Chevron Phillips Chemical, ExxonMobil, Evonik Industries |
The high-performance catalyst market is witnessing transformative momentum driven by evolving industrial needs and global sustainability goals. A primary market driver is the increasing environmental compliance pressure on industries to adhere to stringent environmental regulations.
Governments and regulatory bodies across the globe are enforcing emission standards that necessitate cleaner and more efficient industrial processes. This compels industries to adopt high-performance catalysts, which are critical in reducing emissions and enhancing process efficiencies across sectors such as refining, chemicals, and power generation.
A significant market opportunity lies in the rapidly expanding hydrogen economy. As nations push towards decarbonization, hydrogen emerges as a clean and promising energy vector. High-performance catalysts play a vital role in hydrogen production, storage, and in fuel cells making them essential for scaling up hydrogen infrastructure globally.
The market continues to face challenges, notably the high production costs associated with these catalysts. The reliance on rare and precious metals, such as platinum and palladium, significantly elevates production expenses.
Furthermore, the complex research and development processes needed to create efficient, stable catalysts limit their widespread commercial deployment. This cost factor remains a key hurdle, especially for small- and medium-scale enterprises which limit the expansion in the high-performance catalyst market.
North America dominates the high-performance catalyst market in 2025. The growth of the market is attributed due to its strong industrial base, advanced technological infrastructure, and stringent environmental regulations. The region has seen substantial investments in refining, petrochemical, and environmental sectors, where the adoption of high-performance catalysts is crucial for enhancing process efficiency and reducing emissions.
Additionally, the presence of leading market players such as Albemarle Corporation, W. R. Grace & Co., and Honeywell UOP further reinforces North Americas dominance through continuous innovation and large-scale production capabilities.
Europe expects the fastest growth in the market during the forecast period. The growth of the market is attributed due to homogeneous precious metal catalyst segment. This growth is primarily fueled by the regions well-established chemical manufacturing base and increasing pressure to comply with strict environmental regulations. Projections suggest a strong compound annual growth rate in the forecasting period, signaling Europes rising dominance in this space.
Countries such as Germany and U.K are witnessing a surge in demand for cleaner and more sustainable catalytic processes across various industries including energy, automotive, and pharmaceuticals. The region also benefits from favorable government initiatives, increased R&D activities, and growing foreign direct investments.
Key players operating in this region include BASF SE, Johnson Matthey, and Umicore, all of which are actively expanding their footprint through strategic partnerships and innovation.
Heterogeneous catalysts segment dominated the high-performance catalyst market share 61% in 2025. The growth of the segment is attributed due to their reusability, ease of separation, and widespread industrial application, especially in large-scale chemical and petrochemical processes. Their solid-state nature makes them ideal for continuous production environments, contributing significantly to operational efficiency.
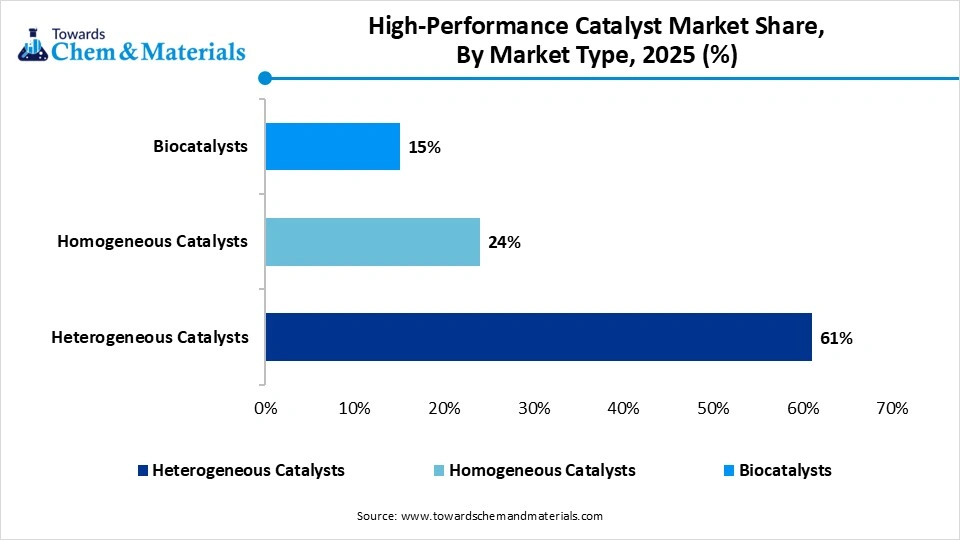 Homogeneous catalysts segment expects significant growth in the market during the forecast period. The growth of the segment is attributed due to their higher selectivity and efficiency in fine chemical and pharmaceutical synthesis. Their rapid adoption in specialized applications is driving innovation and expansion in niche sectors.
High-Performance Catalyst Market Share, By Market Type, 2025 (%)
| By Market Type | Revenue Share, 2025 (%) |
| Heterogeneous Catalysts | 61% |
| Homogeneous Catalysts | 24% |
| Biocatalysts | 15% |
The petrochemical segment dominates high-performance catalyst market share 46% in 2025. The growth of the segment is owing to the heavy reliance on catalysts for cracking, reforming, and hydro processing operations. The global demand for refined fuels and petrochemical derivatives continues to sustain this dominance.
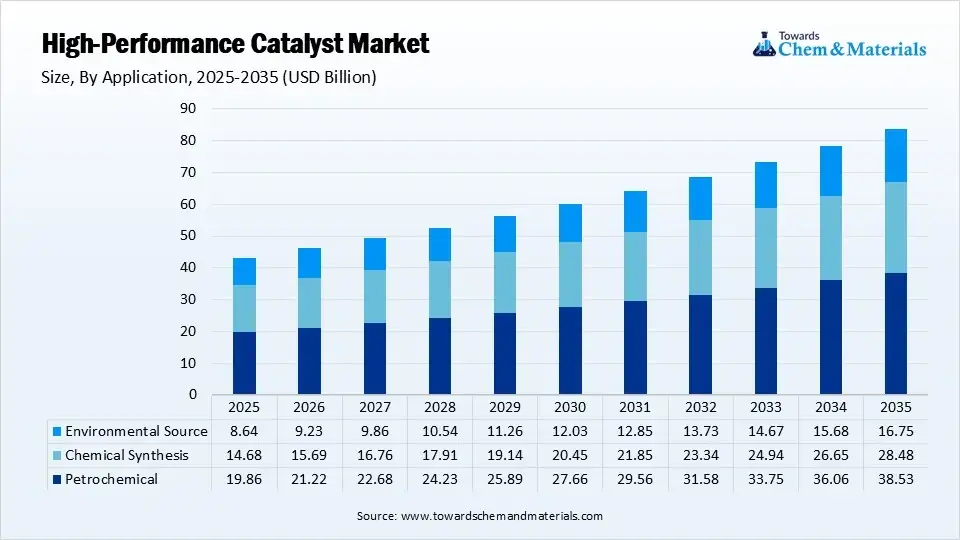 Chemical synthesis segment expects substantial growth in the market during the forecast period. The need for precision, sustainability, and innovation in specialty and fine chemicals drives the adoption of high-performance catalysts with advanced capabilities.
High-Performance Catalyst Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Petrochemical | 46% |
| Chemical Synthesis | 34% |
| Environmental Source | 20% |
The automotive industry segment dominates high-performance catalyst market share 28% in 2025. The growth of the segment is supported by the increasing need for catalytic converters that help meet stringent vehicle emission regulations. Catalysts are crucial for transforming harmful exhaust gases into less toxic substances, making them indispensable in this sector.
Chemical manufacturing segment is experiencing significant growth in the market during the forecast period. The growth of the segment is attributed due to growing demand for specialty chemicals, sustainable production methods, and advancements in catalyst technologies that enable greener and more efficient processes.
High-Performance Catalyst Market Share, By End Use, 2025 (%)
| By End Use | Revenue Share, 2025 (%) |
| Automotive | 28% |
| Chemical Manufacturing | 39% |
| Oil Gas | 33% |
Noble metals segment dominates high-performance catalyst market share 44% in 2025. The growth of the segment is attributed due to their exceptional catalytic properties, especially in emission control and refining processes. Their high efficiency and reliability make them a preferred choice for high-performance catalytic applications.
Transition metals segment expects significant growth in the market during the forecast period.
The transition metals like nickel, copper, and cobalt are the fastest-growing category, owing to their cost-effectiveness, availability, and increasing use in emerging applications, including green chemistry and renewable energy systems. These metals are gaining traction as viable alternatives to reduce dependency on expensive noble metals.
High-Performance Catalyst Market Share, By Active Component, 2025 (%)
| By Active Component | Revenue Share, 2025 (%) |
| Noble Metals | 44% |
| Transition Metals | 36% |
| Metal Oxides | 20% |
How did the Asia Pacific dominate the High-Performance Catalyst Market in 2025?
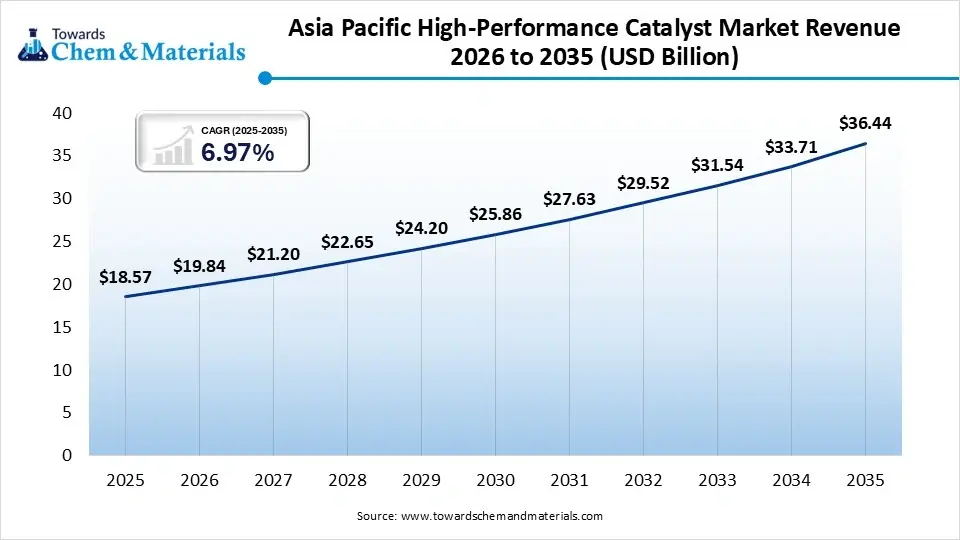
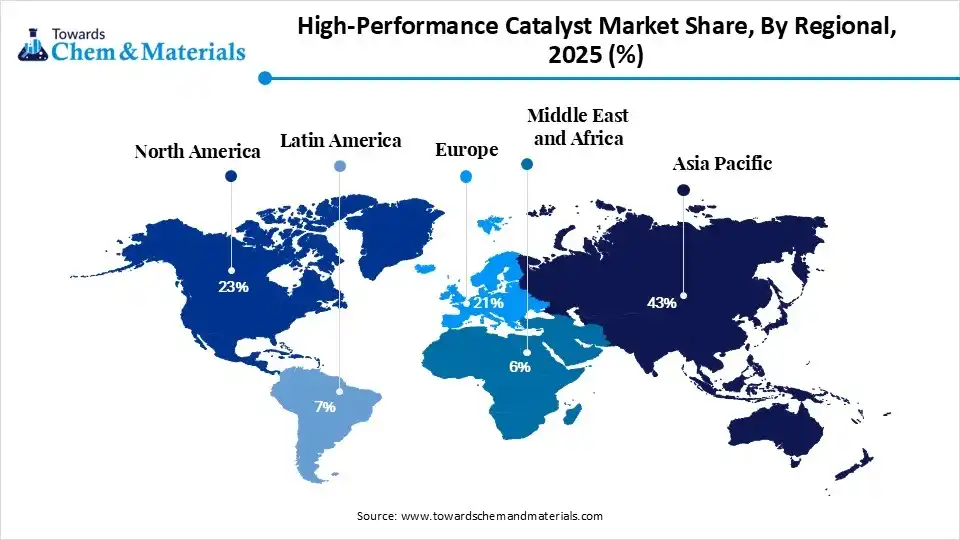
The Asia Pacific high-performance catalyst market size was estimated at USD 18.57 billion in 2025 and is projected to reach USD 36.44 billion by 2035, growing at a CAGR of 6.97% from 2026 to 2035.Asia Pacific held the 43% market share in 2025 and is expected to grow at the fastest CAGR of 7.8% during the forecast period, because of the rapid industrialization, growth in refining and petrochemicals capacity, and increase in chemical manufacturing activities. The region also enjoyed supportive government policies for the promotion of clean energy, emission reduction technology, and hydrogen development. Investment in specialty chemicals and sustainable manufacturing further bolstered the advanced catalyst solutions market.
 China
India
North America held 23% market share in 2025, owing to strict environmental regulations, substantial investments in clean fuels, and upgradation of refining and petrochemical infrastructure. Hydrogen and carbon capture technologies and the growing potential for sophisticated catalyst solutions also offer a competitive advantage in the region, as do advanced research capabilities and the development of advanced pharmaceutical manufacturing.
United States
Canada
Europe held 21% market share in 2025, supported by the stringent environmental regulations, ambitious decarbonization targets, and the general implementation of the principles of the circular economy. The demand for catalysts was boosted by investments in renewable energy, green hydrogen production, and sustainable chemical manufacturing. The development of the market was also significantly boosted by the advanced industrial infrastructure and innovation capabilities.
Germany
France
Latin America held 7% market share in 2025, due to high-performance catalysts, and it was bolstered by catalysts for the growing refinery modernization initiatives, expanding petrochemical production, and the use of cleaner industrial processes in Latin America. Governments and private industries increasingly shifted their attention to sustainability and emission reduction projects, which opened up prospects for the use of new catalyst technologies in energy, chemicals, and manufacturing.
High-Performance Catalyst Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| Asia-Pacific | 43% |
| North America | 23% |
| Europe | 21% |
| Latin America | 7% |
| Middle East & Africa | 6% |
Brazil
Chile
The Middle East & Africa held 6% market share in 2025, due to the high number of activities in the oil & gas industry, refinery expansion, and investments in petrochemicals and clean energy industry. Governments all over the region are focusing on economic diversification and sustainability in industry, with the promotion of using more advanced catalysts in efficient processing and emission reduction applications.
 Saudi Arabia
South Africa

By Market Type
By Application
By End-user
By Active Component
By Regional
Reliable market intelligence and data-driven insights across the global chemicals and materials industry, helping businesses understand trends, competition, pricing, and emerging opportunities.
Schedule a Demo