
Ferrous Metals Market Size Analysis Report 2035
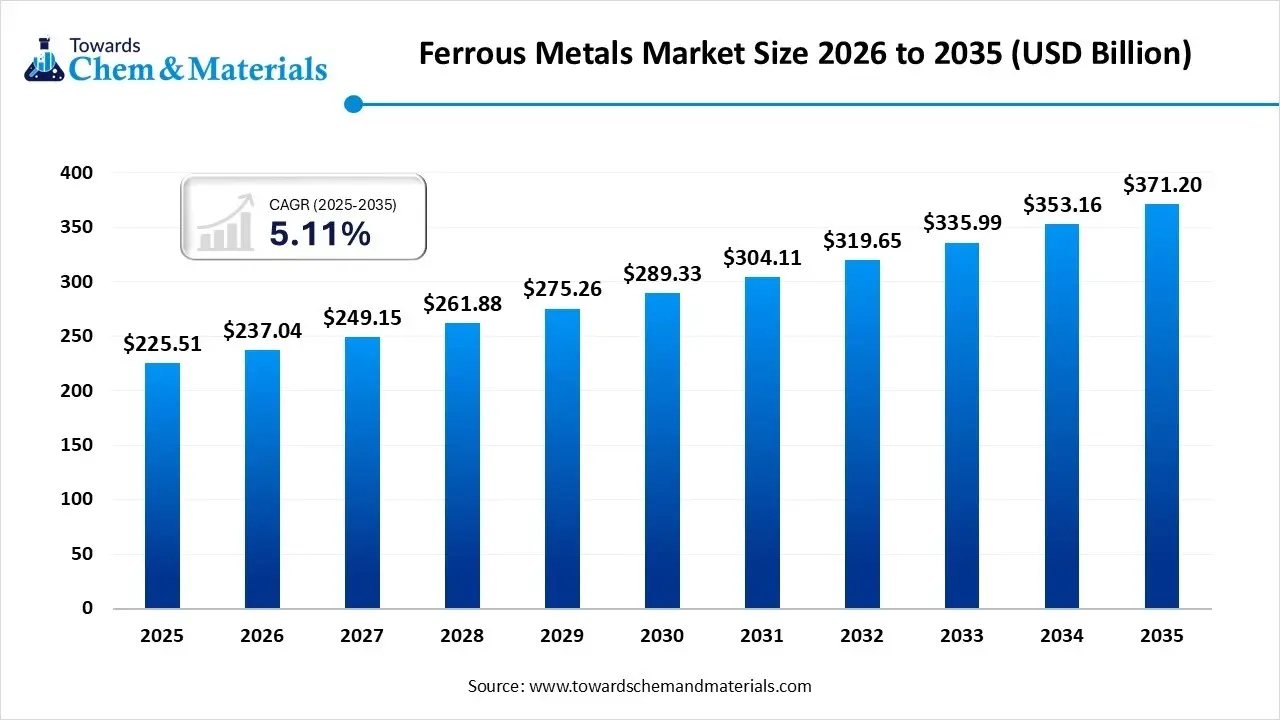
The global ferrous metals market size was estimated at USD 225.51 billion in 2025 and is expected to increase from USD 237.04 billion in 2026 to USD 371.20 billion by 2035, growing at a CAGR of 5.11% from 2026 to 2035. Asia Pacific dominated the ferrous metals market with the largest revenue share of 58% in 2025.The strong infrastructure development in emerging economies is the key factor driving market growth. Also, ongoing product demand from the manufacturing and automotive sectors, coupled with rapid urbanization, can fuel market growth further. the global ferrous metals market comprises metals and alloys that contain iron as their primary constituent, most notably carbon steel, stainless steel, and cast iron. In 2026, the market is navigating a "low growth but high transformation" phase, with traditional demand from construction slowing down while specialty demand from energy transition infrastructure and AI data centers surges.
Market Highlights
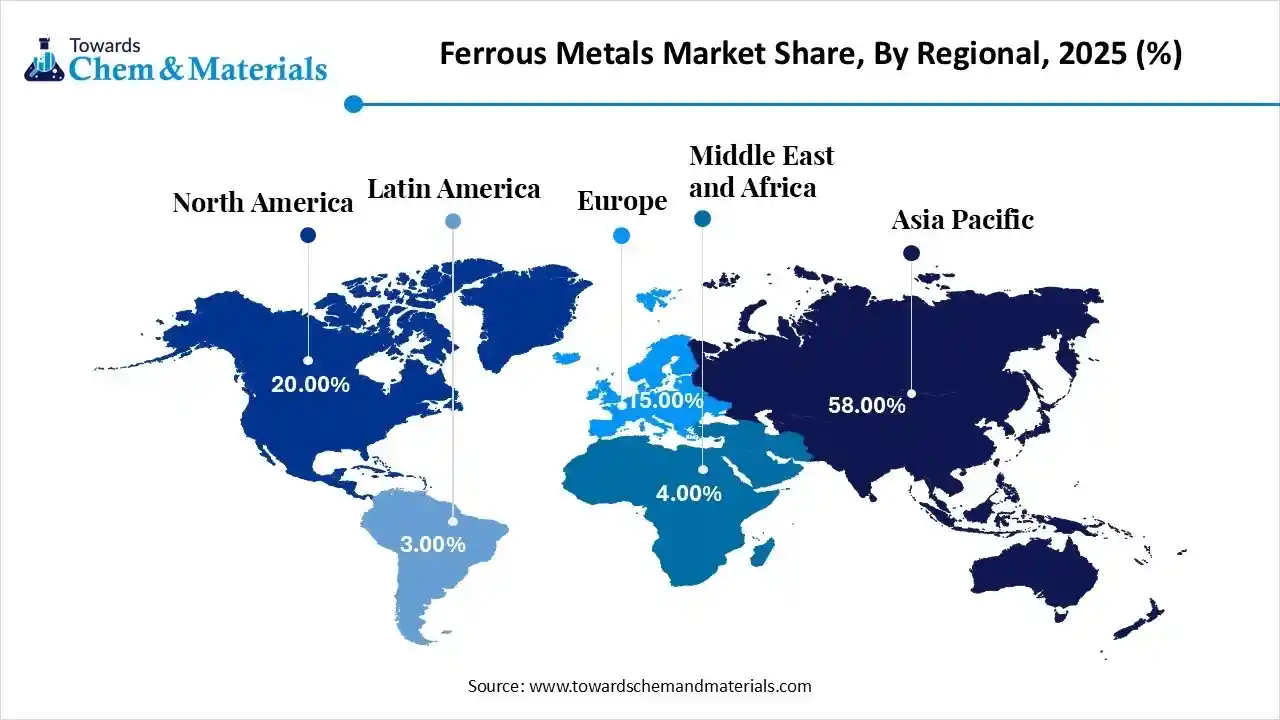
- The Asia Pacific dominated ferrous metals market with the largest revenue share of 58% in 2025.The dominance of the region can be attributed to the increasing demand for construction materials.
- By material type, the stainless-steel segment dominated the market and accounted for the largest revenue share of 45% in 2025. share in 2025. The dominance of the segment can be attributed to the ongoing urbanisation.
- By product form, the flat steels segment led the market with the largest revenue share of 49.00% in 2025. The dominance of the segment can be linked to the rising demand for lightweight materials.
- By application, the construction & infrastructure segment dominated the market and accounted for the largest revenue share of 40% in 2025.The dominance of the segment is owing to the rising population density in major cities.
How Cutting-Edge Technologies Are Revolutionizing the Ferrous Metals Market?
Advanced technologies such as hydrogen-based reduction, AI-driven sorting, and IoT-enabled smart production are transforming the market by improving product quality, efficiency, and sustainability. Furthermore, these advancements automate complex tasks, minimize CO2 emissions, and optimize supply chains, propelling a shift towards high-precision and green steel recycling.
Trade Analysis of the Ferrous Metals Market Import & Export Statistics
- According to American Iron and Steel Institute (AISI) and preliminary Census Bureau data, U.S. steel imports enhance in December 2024, with total imports touched 2,123,000 net tons (NT) a 2.7% increase over November. Finished steel imports increase by 14.3% to 1,820,000 NT.
- Between June 2024 to May 2025, the buyers globally imported 26,564 shipments of Metal Ferrous, through 26,564 exporters and 22,113 verified buyer.
- Russia, Ukraine, and Uzbekistan ranked as the top three importers of ferrous metals, while China, Germany, and Russia led as the top three exporters.
Market Trends
- The ongoing push towards green steel is the latest trend in the market, shaping positive market growth as major companies are shifting from coal-dependent blast furnaces to reduced iron by utilizing green hydrogen. These advancements can further minimize carbon footprints.
- Rapid technological innovations, especially through the adoption of AI and Industry 4.0, are fuelling cost savings and operational efficiencies in markets that use AI for predictive maintenance, substantially enhancing uptime and decreasing unexpected stoppages.
- The growing emphasis on recycling is another major trend in the market, impacting positive growth. The transition towards sustainability not only conserves natural resources but also decreases the overall manufacturing costs for market players.
Report Scope
| Report Attribute | Details |
| Market Size in 2026 | USD 237.04 Billion |
| Revenue Forecast in 2035 | USD 371.20 Billion |
| Growth Rate | CAGR 5.11% |
| Forecast Period | 2026 - 2035 |
| Base Year | 2025 |
| Dominant Region | Asia Pacific |
| Segment Covered | By Material Type, By Product Form, By Application, By Region |
| Key companies profiled | ArcelorMittal S.A., Baoshan Iron & Steel, Nippon Steel Corporation, Tata Steel Limited., Nucor Corporation, JFE Holdings Inc., Thyssenkrupp AG., BHP Group, Rio Tinto Group, Vale S.A., Hyundai Steel Company.,United States Steel Corporation., Gerdau S.A., Cleveland-Cliffs Inc. |
Market Value Chain Analysis
Feedstock Procurement
- It is the systematic acquisition, sourcing, and supply chain management of essential raw materials such as ferrous scrap, iron ore, and coking coal required to produce steel and iron.
- Major Players: ArcelorMittal, Tata Steel
Chemical Synthesis and Processing
- It refers to the application of metallurgical treatments and chemical reaction treatments to refine, extract, alloy, and finish steel and iron products.
- Major Players: POSCO, Nucor Corporation
Packaging and Labelling
- It includes the industrial processes of coating, wrapping, binding, and marking metal products to safeguard them from environmental damage.
- Major Players: POSCO, JFE Steel Corporation.
Regulatory Compliance and Safety Monitoring
- It refers to the environmental, legal, and occupational standards created to ensure safe manufacturing practices and product quality.
- Major Players: Steel Authority of India, JSW Steel
Ferrous Metals Market s Regulatory Landscape: Global Regulations 2x 5
| Country/Region | Key Regulations |
| European Union (EU) | Starting January 1, 2026, CBAM transition from reporting to definitive financial obligations for iron and steel imports. Importers must purchase CBAM certificates based on the embedded carbon emissions of their goods. |
| United States (US) | In 2025/26, the US removed many earlier country exemptions, applying standardized duties to a wider array of processed steel products, including fasteners and structural components. |
| China | Effective January 1, 2026, China has implemented an export licence system for 300 steel products, including hot-rolled and cold-rolled coils. This is intended to manage global trade tensions and reduce low-end overcapacity. |
| India | A new EPR framework for non-ferrous and ferrous-related scrap goes into effect April 1, 2026. It sets recycling targets starting at 10% for the 2026-27 period. |
Segmental Insights
Material Type Insights
How Much Share Did the Stainless Steel Segment Held in 2025?
The carbon steel segment dominated the market with approximately 45.00% share in 2025.The dominance of the segment can be credited to its high demand in energy, medical, and aerospace industries, along with escalating infrastructure development across the globe. Stainless steel is favoured for chassis components, battery enclosures, and thermal management systems because of its high corrosion resistance.
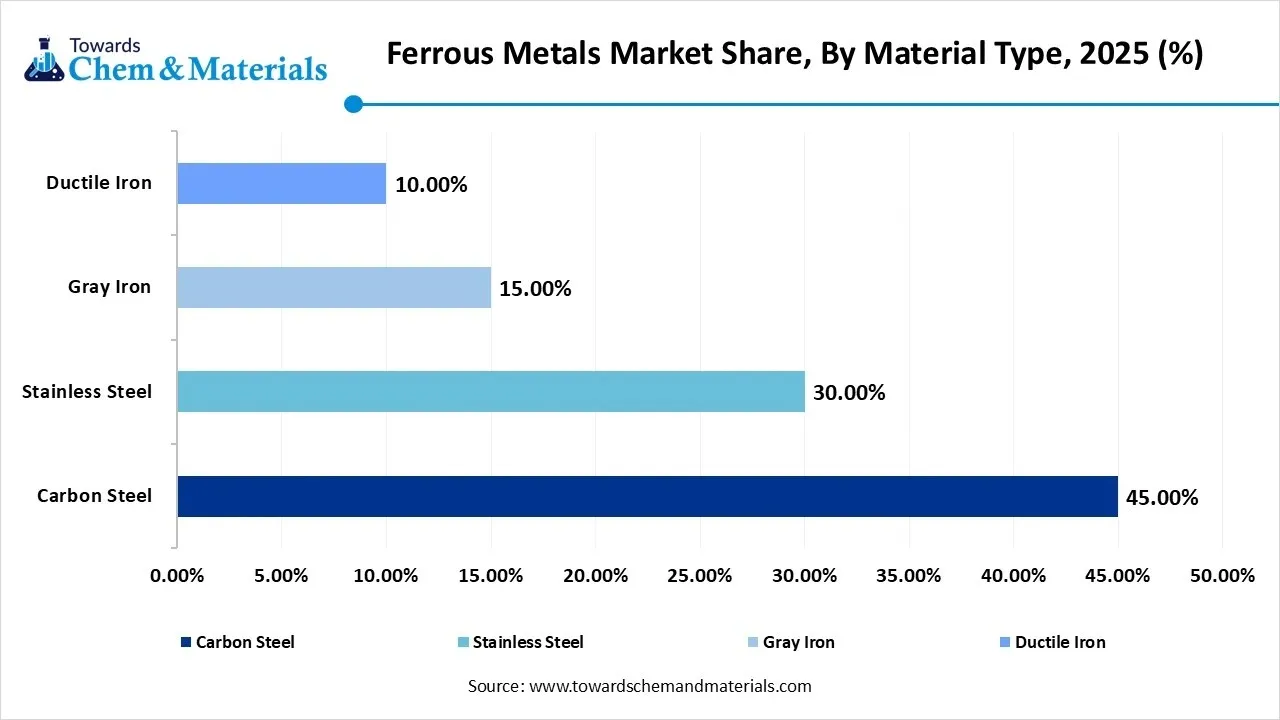
The carbon steel segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be attributed to the ongoing urbanisation and robust shift towards recycling, especially in emerging regions such as the Asia-Pacific. In addition, carbon steel is preferred for its better mechanical properties and cost-effectiveness compared to other materials, leading to significant growth.
Ferrous Metals Market Share, By Material Type, 2025 (%)
| By Material Type | Revenue Share, 2025 (%) |
| Carbon Steel | 30.00% |
| Stainless Steel | 45.00% |
| Gray Iron | 15.00% |
| Ductile Iron | 10.00% |
Product Form Insights
Which Product Form Type Segment Dominated Ferrous Metals Market in 2025?
The flat steel segment held the largest market share 49.00% in 2025. The dominance of the segment can be linked to the rising demand for lightweight and durable materials across several key industries, especially in emerging countries. Additionally, major market players are rapidly adopting Advanced High-Strength Steel (AHSS) to minimize vehicle weight for crashworthiness and fuel efficiency in EV and conventional vehicles.
The pipes & tubes segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment can be driven by a surge in total energy demand, the rapid growth of power generation, and the automotive sector. Also, the rise in demand for corrosion-resistant and high-strength pipes for renewable energy projects is creating lucrative opportunities for the market.
Ferrous Metals Market Share, By Product Form, 2025 (%)
| By Product Form | Revenue Share, 2025 (%) |
| Flat Steels | 49.00% |
| Long Steels (Rebar, wire rods). | 25.00% |
| Pipes & Tubes. | 15.00% |
| Other Product Types | 11.00% |
Application Insights
Which Application Type Segment Dominated Ferrous Metals Market in 2025?
The construction & infrastructure segment dominated the market with nearly 40% share in 2025. The dominance of the segment is owing to the rising population density in major cities, along with the implementation of various government initiatives in developing countries. Furthermore, the trend towards prefabricated and modular construction is propelling product demand further.
The energy transition segment is expected to grow at the fastest CAGR over the forecast period. The growth of the segment is due to the increasing need for high-strength materials for low-carbon infrastructure, coupled with the development of renewable energy infrastructure. Moreover, strict policies are encouraging the use of sustainable material sourcing, driving segment growth shortly.
Ferrous Metals Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Construction & Infrastructure | 40.00% |
| Automotive | 30.00% |
| Energy Transition | 17.00% |
| AI Infrastructure | 13.00% |
Regional Insights
How did Asia Pacific Dominate the Ferrous Metals Market in 2025?
The Asia Pacific ferrous metals market size was valued at USD 130.80 billion in 2025 and is expected to be worth around USD 215.30 billion by 2035, exhibiting at a compound annual growth rate (CAGR) of 5.15% over the forecast period from 2026 to 2035.
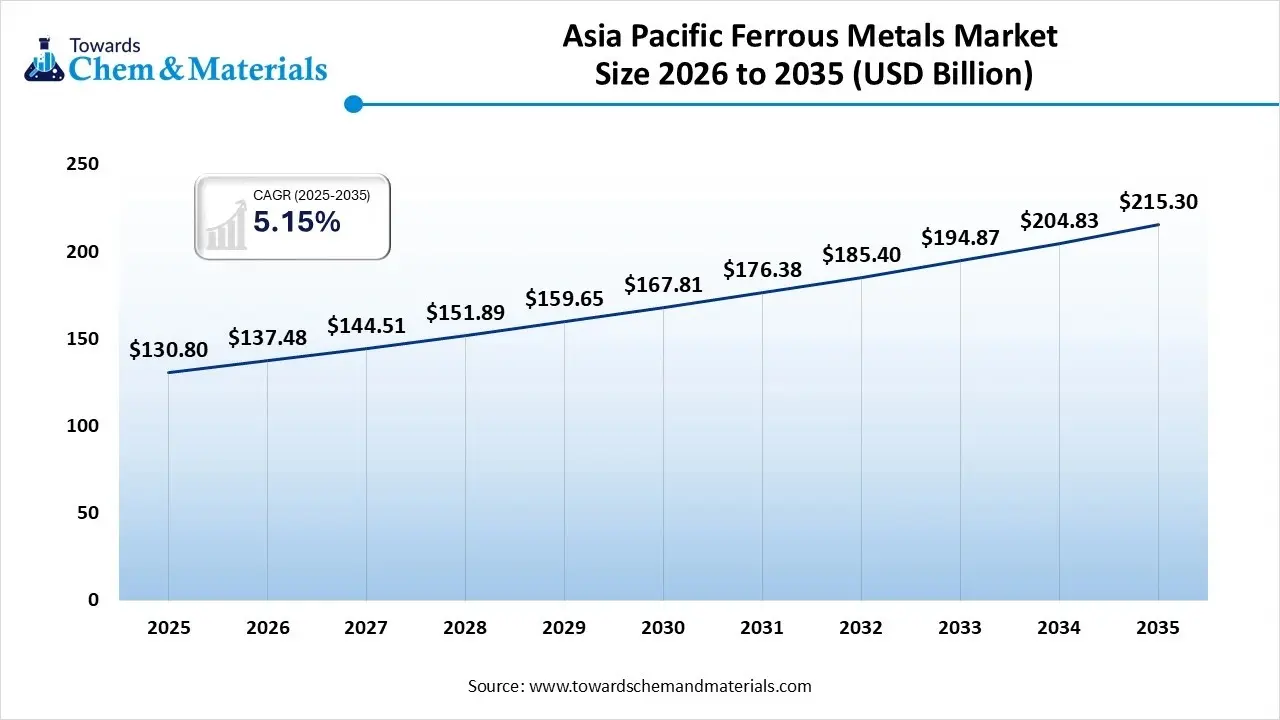
Asia Pacific dominated the market with the largest share of approximately 58% in 2025. The dominance of the region can be attributed to the increasing demand for construction materials and rising ferrous scrap recycling for sustainability. In addition, the surge in tools, machinery, and industrial equipment manufacturing is propelling the demand for steel and iron products soon.
China Ferrous Metals Market Trends
In the Asia Pacific, China dominated the market owing to extensive infrastructure projects and increasing product demand from the manufacturing industry. Also, the country heavily relies on imports of raw materials, with most of its ore coming from Australia and Brazil, necessitating robust and long-term strategic purchasing agreements.
North America ferrous metals market segment accounted for the major revenue share of 20.00% in 2025. North America is expected to grow at the fastest CAGR over the forecast period. The growth of the region can be credited to the rapid implementation of cutting-edge production technologies and an increase in the usage of stainless steel. Major market players are using AI to enhance crop sorting, optimize furnace temperatures, and use predictive maintenance to minimize downtime and overall production costs.
U.S. Ferrous Metals Market Trends
In North America, the U.S. led the market due to strong product demand from the construction, automotive, and manufacturing industries, coupled with the rising adoption of stainless steel. Moreover, the rapid shift towards hybrid and electric vehicles is propelling the demand for lightweight, specialized, and durable stainless-steel materials.
Europe Ferrous Metals Market Trends
Europe ferrous metals market segment accounted for the major revenue share of 15.00% in 2025.Europe is expected to grow at a notable CAGR over the forecast period. The growth of the region can be driven by increasing product demand for recycled scrap and its strong automotive manufacturing sector. Furthermore, the rising adoption of AI-driven automation, smart factory concepts, and cutting-edge heat treatment technologies improves the overall operational efficiency.
Ferrous Metals Market Share, By Regional, 2025 (%)
| Regional | Revenue Share, 2025 (%) |
| North America | 20.00% |
| Europe | 15.00% |
| Asia Pacific | 58.00% |
| Latin America | 3.00% |
| Middle East & Africa | 4.00% |
Germany Ferrous Metals Market Trends
The growth of the market in the country can be fuelled by the growing adoption of Industry 4.0 automation and additive production in manufacturing processes, which require specialized steel products. Additionally, stringent environmental policies and climate goals are pushing market players to adopt energy-efficient processes and strategies, leading to market growth soon.
Recent Developments
- In November 2025, Shanghai Metals Market (SMM) announced the operational commencement and launch of its Korea Office. This growth reflects SMMs commitment to the Northeast Asian market and highlights its emphasis on delivering localized services to clients.(Source: news.metal.com)
Market Top Companies
- ArcelorMittal S.A.: ArcelorMittal S.A. is a dominant force in the global ferrous metals market, currently ranked as the worlds second-largest steel producer. Headquartered in Luxembourg, it operates a vertically integrated business model that spans the entire value chain from iron ore mining to finished steel products.
- Baoshan Iron & Steel: Baoshan Iron & Steel Co., Ltd. (commonly known as Baosteel) is the premier, state-owned steel manufacturer in China and a central subsidiary of the China Baowu Steel Group, the worlds largest steelmaker.
- Nippon Steel Corporation: Nippon Steel Corporation is the largest Japanese steelmaker and a top five global producer, focusing on high-grade steel production and international expansion with a goal of 100 million tons in capacity.
- Tata Steel Limited.
- Nucor Corporation
- JFE Holdings Inc.
- Thyssenkrupp AG.
- BHP Group
- Rio Tinto Group
- Vale S.A.
- Hyundai Steel Company.
- United States Steel Corporation.
- Gerdau S.A.
- Cleveland-Cliffs Inc.
Segments Covered in the Report
By Material Type
- Carbon Steel
- Stainless Steel
- Gray Iron
- Ductile Iron
By Product Form
- Flat Steels (Hot-rolled, Cold-rolled coils)
- Long Steels (Rebar, wire rods).
- Pipes & Tubes.
By Application
- Construction & Infrastructure
- Automotive
- Energy Transition
- AI Infrastructure
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- South Korea
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- Saudi Arabia
- South Africa
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.