
Smart Coating Market Size, Competitive Landscape Analysis Report 2035
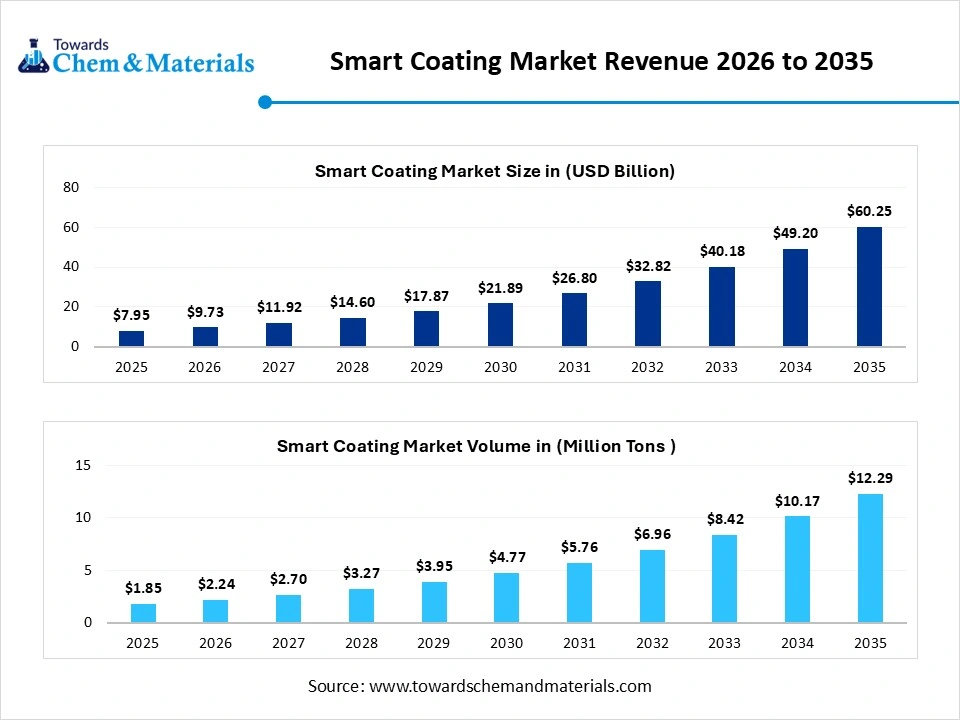
The global smart coating market size was estimated at USD 7.95 billion in 2025 and is expected to be worth around USD 60.25 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 22.45% over the forecast period from 2026 to 2035. In terms of volume the smart coating market is projected to grow from 1.85 million tons in 2025 to 12.29 million tons by 2035. growing at a CAGR of 20.85% from 2026 to 2035.This report provides comprehensive insights into market size, segment-wise data by type, functionality, and end-use industries, along with regional analysis across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. It also covers key company profiles, manufacturers and suppliers data, competitive landscape, value chain analysis, and detailed trade statistics, highlighting the increasing demand for self-healing, anti-corrosion, and anti-fouling coatings.
Key Takeaways
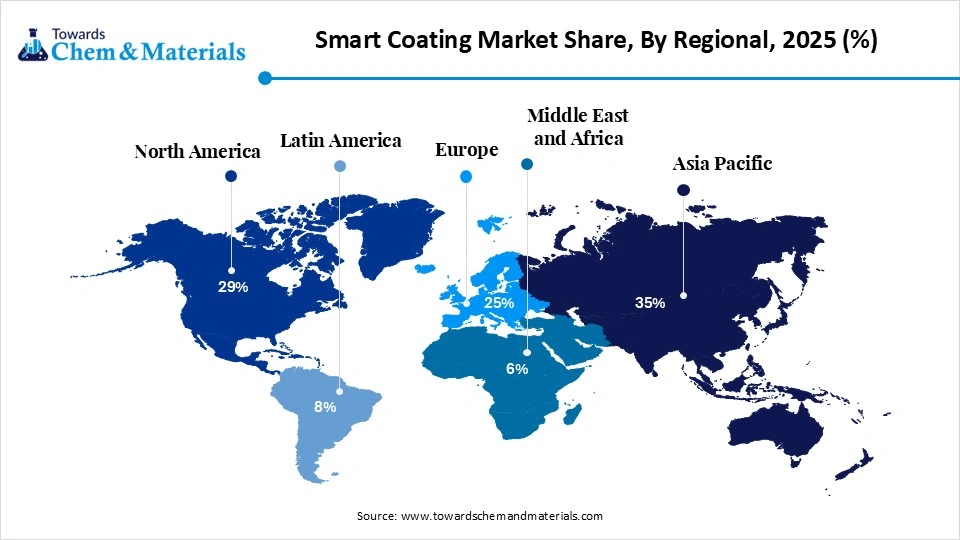
- By region, Asia Pacific dominated the market with a share of 32% in 2025 and is expected to have the fastest growth with a CAGR of 24.30% in the forecast period. The growth is driven by rapid urbanization.
- By region, North America held the second largest share of 29% in 2025. The regulatory concerns and supports drive the growth of the market.
- By type, the anti-corrosion coatings segment dominated the market with 32% share in 2025. High use in various industries drives the growth of the market.
- By type, the self-healing coatings segment held the second largest share of 28% in 2025 and is expected to have the fastest growth with a CAGR of 25.80% in the forecast period. The increased use due to its properties, such as durability, increases the demand for the market.
- By function, the protection segment dominated the market with 38% share in 2025. The increased demand for coatings due to the demand for corrosion resistance drives the demand.
- By function, the sensing segment held the fourth largest share of 18% in 2025 and is expected to have the fastest growth with a CAGR of 24.7% in the forecast period. The increased use of aerospace and defense monitoring drives the demand for the market.
- By end use industry, the automotive segment dominated the market with 24% share in 2025. Increasing vehicle production globally boosts coating demand
- By end use industry, the healthcare segment held the fourth largest share of 12% in 2025 and is expected to have the fastest growth with a CAGR of 24.90% in the forecast period. Increased healthcare infrastructure spending supports growth.
- By technology, the nano-coatings segment dominated the market with 34% share in 2025 and is expected to have the fastest growth with a CAGR of 25.20% in the forecast period. Increasing R&D investments accelerate innovation.
- By technology, the polymer-based coatings segment held the second largest share of 28% in 2025. High adoption in the automotive and construction sectors.
Market Overview
What is the Significance of the Smart Coating Market?
The smart coating market is highly significant for enabling materials to respond to environmental stimuli such as self-healing, anti-corrosion, and anti-microbial properties, drastically increasing the longevity and efficiency of industrial assets. It is projected to grow rapidly, driven by demand in automotive, aerospace, and construction for energy efficiency and reduced maintenance. Smart materials are increasingly used to regulate temperature and enhance the efficiency of solar panels, contributing to sustainability goals and lowering energy consumption.
Smart Coating Market Growth Trends:
- Self-Healing and Anti-Corrosion Technologies: A significant trend is the development of coatings that autonomously repair scratches and micro-cracks, protecting assets in harsh industrial environments.
- IoT and Real-Time Monitoring: Smart coatings are increasingly integrating with sensors and IoT devices to allow for real-time monitoring of structural health, corrosion levels, and temperature, enabling predictive maintenance.
- Sustainability and Eco-Friendly Formulations: There is a strong focus on developing eco-friendly coatings with low volatile organic compounds (VOCs) and bio-based ingredients to comply with stricter environmental regulations.
Key Technological Shifts In The Smart Coating Market:
The smart coating market is undergoing a shift toward self-healing, self-cleaning, and stimuli-responsive materials, with a strong emphasis on sustainability and nanotechnology. Key innovations include AI-driven development, IoT-enabled predictive maintenance, and multifunctional coatings that improve energy efficiency and durability in high-growth sectors like autonomous vehicles and renewable energy. The integration of sensors and AI into coatings allows for real-time monitoring of structural integrity, enabling predictive maintenance rather than reactive repairs.
Trade Analysis Of Smart Coating Market: Import & Export Statistics
- According to Global Export Data, the world exported 15,431 Coatings shipments between July 2024 and June 2025 (TTM) via 859 exporters and 1,395 buyers, representing an 8% YoY change.
Top-performing Coatings Exporters by volume:
- AUDAX PROTECTIVE FABRICS PRIVATE: 2,976 shipments (38%)
- Mayur Uniquoters Ltd: 2,133 shipments (27%)
- Veer Plastics Pvt Ltd: 540 shipments (7%)
Smart Coating Market - Supply Chain Analysis
Coating Formulation & Functionalization
Smart coatings are developed through the formulation of advanced materials such as self-healing polymers, anti-corrosion agents, hydrophobic/hydrophilic layers, and stimuli-responsive compounds for enhanced performance in various environments.
- Key players: PPG Industries, AkzoNobel, Sherwin-Williams, BASF.
Quality Testing and Certification
Smart coatings must meet standards for durability, corrosion resistance, environmental compliance, and performance under varying conditions.
- Key players: International Organization for Standardization, ASTM International, European Chemicals Agency, Underwriters Laboratories
Distribution to Industrial Users
Smart coatings are supplied to automotive manufacturers, aerospace companies, construction industries, marine applications, electronics manufacturers, and healthcare sectors.
- Key players: PPG Industries, AkzoNobel, Sherwin-Williams.
Smart Coating Regulatory Landscape: Global Regulations
| Country / Region | Regulatory Body | Key Regulations | Focus Areas | Notable Notes |
| U.S. | Environmental Protection Agency (EPA); Occupational Safety and Health Administration (OSHA) | Toxic Substances Control Act (TSCA); Clean Air Act; OSHA Hazard Communication Standard | Chemical safety, VOC emissions, and worker safety | Smart coatings containing functional additives (self-healing, anti-corrosion, antimicrobial) must comply with VOC emission limits and workplace safety regulations. |
| Europe | European Chemicals Agency (ECHA); European Commission | REACH Regulation; CLP Regulation; Biocidal Products Regulation (BPR) | Chemical registration, hazardous substance restriction, and antimicrobial coatings regulation | The EU strictly regulates coatings with biocidal or nano-enabled properties, requiring authorization and safety assessment. |
| China | Ministry of Ecology and Environment (MEE); Ministry of Industry and Information Technology (MIIT) | Environmental Protection Law; VOC Emission Standards | Industrial emissions, coating safety, and chemical control | China enforces VOC limits and promotes eco-friendly coatings technologies in the industrial and construction sectors. |
| India | Ministry of Environment, Forest and Climate Change (MoEFCC); Central Pollution Control Board (CPCB) | Environment Protection Act; National Air Quality Standards | VOC emissions, environmental safety | India is increasingly regulating VOC emissions from paints and coatings, supporting the shift toward low-VOC smart coatings. |
| Japan | Ministry of Economy, Trade and Industry (METI); Ministry of the Environment | Chemical Substances Control Law (CSCL); Air Pollution Control Act | Chemical management, emission control | Japan enforces strict chemical safety and emission regulations for advanced coatings used in automotive and electronics industries. |
| South Korea | Ministry of Environment (MoE); Ministry of Trade, Industry and Energy (MOTIE) | K-REACH; Clean Air Conservation Act | Chemical registration, VOC control | South Korea regulates smart coatings under chemical safety and air quality laws, especially for industrial applications. |
Segmental Insights
Type Insights
The Anti-Corrosion Coatings Segment Dominated The Market With 32% Market Share In 2025
The anti-corrosion coatings segment dominated the market with 32% share in 2025, high demand for durable, self-healing protection in the automotive, aerospace, and marine industries. These advanced coatings use technologies like pH-sensitive microcapsules to release inhibitors upon damage, significantly extending infrastructure lifespan and reducing maintenance costs. Strong growth is fueled by infrastructure investment, particularly in oil and gas for pipelines and offshore structures, which fuels the growth of the market.
The self-healing coatings segment held the second largest share of 28% in 2025 and is expected to have the fastest growth with a CAGR of 25.80% in the forecast period, driven by demand for enhanced durability in automotive, construction, and electronics sectors. Growth is fueled by the need for reduced maintenance costs and longer asset lifespans, with extrinsic (microcapsule-based) systems currently dominating due to easier, cost-effective integration into existing production.
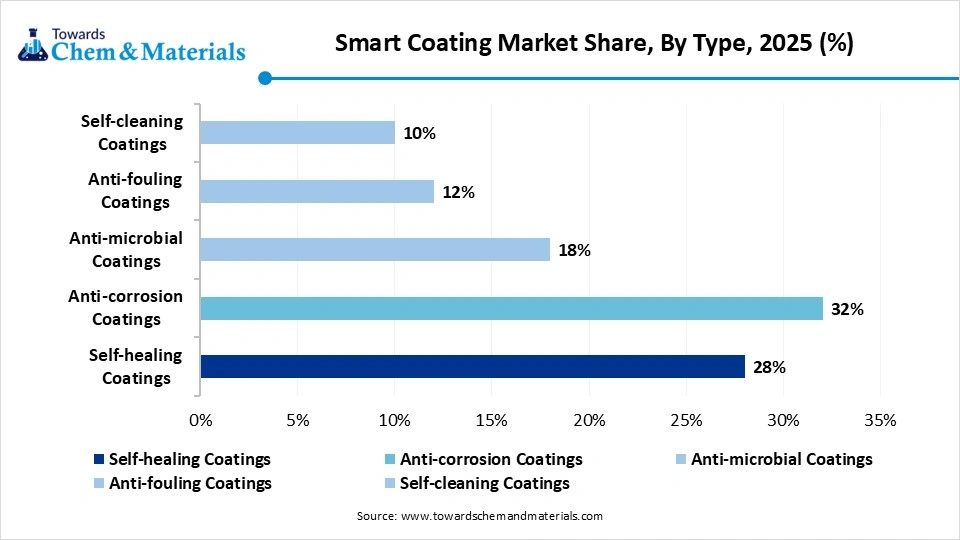
The anti-microbial coatings segment held the third largest share of 18% in 2025, driven by heightened hygiene awareness, infection control needs in healthcare, and advanced nanotechnology. The surge in hospital-acquired infections (HAIs) has accelerated the demand for, and adoption of, antimicrobial coatings on medical devices and surfaces. The market is evolving from basic antimicrobial applications to multi-functional coatings that provide additional benefits like anti-fouling or UV resistance.
The anti-fouling coatings segment held the fourth largest share of 12% in 2025, driven by the need to reduce marine biofouling and enhance fuel efficiency to meet environmental regulations. The market is shifting toward non-toxic, nanotechnology-based, and self-cleaning coatings that offer high durability and low-friction, reducing aquatic toxicity. Strict regulations against toxic biocide leaching have led to high demand for eco-friendly, green antifouling alternatives.
Function Insights
The Protection Segment Dominated The Market With 38% Market Share In 2025
The protection segment dominated the market with 38% share in 2025, driven by demand for advanced corrosion resistance, self-healing functionalities, and anti-microbial properties in automotive, aerospace, and infrastructure. The segment is expanding to enhance asset longevity, reduce maintenance costs, and meet stricter environmental regulations. Growing focus on sustainability and energy efficiency in construction, alongside protective coatings for wind turbines and solar installations, further fuels the growth and expansion.
The self-repairing segment held the second largest share of 24% in 2025, driven by advancements in nanotech, microencapsulation, and high demand from automotive, aerospace, and construction sectors. These coatings autonomously fix damages, reducing maintenance costs and increasing component lifespan. Industries are actively adopting self-healing coatings to minimize repair costs and prolong the life of materials, particularly in automotive and construction.
The aesthetic enhancement segment held the third largest share of 20% in 2025, driven by the increasing integration of functional properties such as self-cleaning, color-shifting, and scratch resistance that preserve or improve the visual appeal of surfaces while providing superior durability. This segment is closely linked to the automotive and construction industries, where consumer demand for high-end finishes, easy maintenance, and long-lasting aesthetics is rising.
The sensing segment held the fourth largest share of 18% in 2025 and is expected to have the fastest growth with a CAGR of 24.7% in the forecast period, driven by the integration of IoT-enabled sensors that monitor structural health, corrosion, and environmental conditions in real-time. This growth is accelerated by demand for proactive maintenance in infrastructure and automotive sectors, with smart coatings acting as both protection and functional sensors.
End-use Industry Insights
The Automotive Segment Dominated The Market With 24% Market Share In 2025
The automotive segment dominated the market with 24% share in 2025, fueled by demand for anti-corrosion, self-healing, and aesthetic, high-gloss finishes, driving the growth of the market. The shift toward waterborne and environmentally friendly, low-VOC coatings is boosting adoption in automotive production, aligning with environmental regulations. The adoption of nanotechnology and waterborne technologies for better performance further boosts growth.
The construction segment held the second largest share of 22% in 2025, fueled by demand for sustainable, energy-efficient, and durable materials in residential and commercial projects. The market is growing through the adoption of self-cleaning, anti-corrosion, and anti-fouling coatings that reduce maintenance and improve structural longevity, with construction set to outpace other segments.
Smart Coating Market Share, By End-use Industry, 2025 (%)
| By End-use Industry | Revenue Share, 2025 (%) |
| Automotive | 24% |
| Aerospace & Defense | 15% |
| Construction | 22% |
| Marine | 10% |
| Healthcare | 12% |
| Electronics | 9% |
| Energy | 8% |
The aerospace & defense segment held the third largest share of 15% in 2025, driven by the need for enhanced durability, corrosion resistance, and structural health monitoring in extreme environments, which fuels the growth. The integration of nanotechnology, IoT-enabled functionalities, and self-cleaning capabilities allows coatings to provide real-time monitoring of structural integrity.
The healthcare segment held the fourth largest share of 12% in 2025 and is expected to have the fastest growth with a CAGR of 24.90% in the forecast period, driven by the surging demand for antimicrobial, antibiofilm, and self-cleaning surfaces to prevent healthcare-associated infections (HAIs). This sector is adopting advanced coatings for medical devices, implants, and surface sterilization to improve patient outcomes and enhance medical infrastructure safety.
Technology Insights
The Nano Coatings Segment Dominated The Market With 34% Market Share In 2025
The nano coatings segment dominated the market with 34% share in 2025 and is expected to have the fastest growth with a CAGR of 25.20% in the forecast period, driven by the demand for superior performance, durability, and multifunctionality, with the automotive and construction sectors adopting anti-corrosion, self-cleaning, and antimicrobial features. The segment dominates through applications like anti-fingerprint, self-healing, and thermal insulation, particularly in high-end, luxury vehicles.
Smart Coating Market Share, By Technology, 2025 (%)
| By Technology | Revenue Share, 2025 (%) |
| Nano-coatings | 34% |
| Polymer-based Coatings | 28% |
| Sol-gel Coatings | 16% |
| Layer-by-layer Assembly | 12% |
| Others | 10% |
The polymer-based coatings segment held the second largest share of 28% in 2025, fueled by the demand for self-healing, self-cleaning, and anti-corrosion properties in automotive, construction, and electronics sectors. The market for polymer coatings is projected to grow significantly, with polyurethane, epoxy, and acrylic types leading due to their durability and responsiveness to environmental stimuli.
The sol-gel coatings segment held the third largest share of 16% in 2025, driven by high-performance polyurethane (PU) in automotive and industrial uses. The market is driven by increasing demand for anti-corrosion, self-healing, and self-cleaning functionality in construction and automotive sectors. Rapid expansion in applications such as self-healing and anti-corrosion relies heavily on polymer-based technologies, driving growth in the market.
The layer-by-layer assembly segment held the fourth largest share of 12% in 2025, driven by increasing demand for self-healing and multifunctional coatings in automotive, aerospace, and electronics sectors. The market is growing due to demand for advanced materials in the construction and automotive sectors. The growth is further propelled due to their widespread use in automotive, aerospace, and construction, due to their properties, which increase the demand.
Regional Insights
How did Asia Pacific Dominate the Smart Coating Market in 2025?
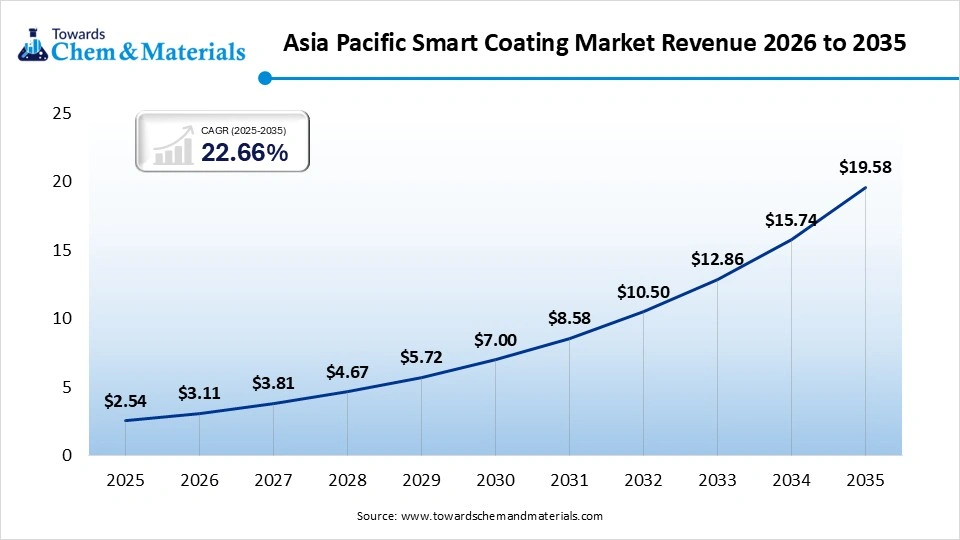
The Asia-Pacific smart coating market size was estimated at USD 2.54 billion in 2025 and is projected to reach USD 19.58 billion by 2035, growing at a CAGR of 22.66% from 2026 to 2035. Asia Pacific dominated the market with a share of 32% in 2025 , due to rapid industrialization, massive infrastructure projects, and high demand from the automotive, construction, and electronics sectors in China, India, and Japan. Growth is driven by the urgent need for advanced, high-performance, and sustainable materials, such as self-healing and anti-corrosion coatings, supported by significant local manufacturing and research investments. Lower manufacturing costs in the region allow for high-volume production, making advanced coatings more affordable.
India Smart Coating Market Growth Factor
The Indian smart coating market is driven by rapid industrial expansion, particularly in the automotive, construction, and electronics sectors. Rising demand for self-cleaning and anti-corrosion properties, advancements in nanotechnology, and increased urbanization requiring durable, high-performance protective materials are some of the major growth factors in the country. The integration of nanotechnology is a primary factor, allowing for thinner, more robust coatings, with self-healing technologies gaining traction in the Indian market.
North America Smart Coating Market Growth Factor
North America held the second largest share of 29% in 2025, driven by high demand in aerospace, automotive, and infrastructure sectors, rising needs for self-healing and anti-corrosion properties, advancements in nanotechnology, and increased adoption of sustainable, energy-efficient solutions. Continuous innovation in nanomaterials and functional coatings enables superior surface protection and longevity, driving up high-performance coatings.
U.S. Smart Coating Market Growth Factor
The U.S. smart coating market is driven by high demand for self-healing, anti-corrosion, and anti-microbial functionalities, with the automotive and aerospace sectors leading adoption. Growth is fueled by infrastructure investment, demand for energy-efficient materials, and advancements in nanotechnology. The market is expected to see significant expansion, with North America being a leading region. Post-pandemic hygiene awareness has surged demand for antimicrobial coatings in public spaces, healthcare, and consumer goods.
Recent Developments
- In April 2026, Onyx Coating expanded its automotive protection lineup with the global launch of Vunyx® Smart Shield Films. The new lineup is cost-effective, self-healing TPU paint protection films designed for professional installers. it is a new two‑tier paint protection film (PPF) family designed for installers, high‑clarity, detailers, car workshops, panel beaters, and distributors looking for reliable, value‑driven protection solutions.
- In July 2025, Nippon Paint introduced Walltron Advance Thermal Comfort Solutions (WATCS), a smart coating designed to combat the urban heat island effect. This technology features a high Solar Reflectance Index (SRI) of 108, reducing surface temperatures by up to 25°C and offering hydrophobic, crack-bridging protection for buildings.
Smart Coating Market Competitive Landscape Analysis
Tier 1 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | PPG Industries, Inc. | Pittsburgh, Pennsylvania | United States | Global leader in advanced functional and protective coatings with strong R&D capabilities | Self-cleaning coatings, anti-corrosion coatings, aerospace coatings, conductive coatings |
| 2 | Akzo Nobel N.V. | Amsterdam | Netherlands | Leading supplier of smart protective coatings for marine, industrial, and infrastructure applications | Anti-fouling coatings, self-polishing coatings, protective coatings |
| 3 | The Sherwin-Williams Company | Cleveland, Ohio | United States | Major provider of high-performance industrial and protective smart coating technologies | Protective coatings, antimicrobial coatings, corrosion-resistant coatings |
| 4 | Axalta Coating Systems Ltd. | Philadelphia, Pennsylvania | United States | Global supplier of advanced coatings for automotive, transportation, and industrial sectors | Functional automotive coatings, anti-corrosion coatings, specialty coatings |
| 5 | Nippon Paint Holdings Co., Ltd. | Tokyo | Japan | Strong presence in functional coatings with significant investments in smart coating technologies | Self-cleaning coatings, antimicrobial coatings, industrial coatings |
Tier 2 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | Jotun A/S | Sandefjord | Norway | Major supplier of advanced marine and protective coatings with smart surface technologies | Anti-fouling coatings, corrosion-resistant coatings, marine coatings |
| 2 | Hempel A/S | Kongens Lyngby | Denmark | Strong portfolio of high-performance industrial and marine smart coatings | Protective coatings, anti-corrosion coatings, fouling defense systems |
| 3 | BASF SE | Ludwigshafen, Rhineland-Palatinate | Germany | Supplier of advanced coating resins, additives, and functional materials for smart coatings | Functional coating resins, additives, nanomaterials |
| 4 | Henkel AG & Co. KGaA | Düsseldorf, North Rhine-Westphalia | Germany | Developer of functional surface technologies and specialty coatings for electronics and industrial markets | Functional coatings, conductive coatings, protective surface technologies |
| 5 | 3MCompany | Saint Paul, Minnesota | United States | Developer of specialty coatings and advanced surface protection technologies | Hydrophobic coatings, optical coatings, protective films, functional coatings |
Tier 3 Companies
|
Rank
|
Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
| 1 | NEI Corporation | Somerset, New Jersey | United States | Specialist in nanostructured and multifunctional smart coating technologies | Self-cleaning coatings, anti-corrosion nanocoatings, conductive coatings |
| 2 | Nanovere Technologies, LLC | League City, Texas | United States | Developer of nano-enabled smart coatings for industrial and energy applications | Hydrophobic coatings, anti-corrosion nanocoatings |
| 3 | ACTnano, Inc. | Cambridge, Massachusetts | United States | Innovator in ultra-thin protective coatings for electronics and automotive applications | Waterproof nano coatings, conformal protective coatings |
| 4 | Tesla NanoCoatings, Inc. | Pittsburgh, Pennsylvania | United States | Developer of advanced anti-corrosion and asset protection coating technologies | Corrosion-resistant smart coatings, industrial protective coatings |
| 5 | BioCote Limited | Coventry, England | United Kingdom | Specialist in antimicrobial coating technologies for healthcare and consumer applications | Antimicrobial coatings, hygienic surface technologies |
Top players in the Smart Coating Market & Their Offerings
- Clariant AG: Clariant develops specialty additives used in smart coatings, enabling functionalities such as UV resistance, anti-microbial properties, and improved durability. The company supports innovation in high-performance coating formulations.
- Nippon Paint Holdings Co., Ltd.: Nippon Paint develops smart coatings for the construction and automotive sectors, including heat-reflective, anti-bacterial, and self-cleaning coatings. The company focuses on energy-efficient and environmentally friendly coating technologies.
- PPG Industries, Inc.: PPG Industries develops advanced smart coatings with functionalities such as self-healing, anti-corrosion, anti-fouling, and temperature-sensitive properties. The company serves industries including aerospace, automotive, marine, and construction with high-performance coating solutions.
- Akzo Nobel N.V.: Akzo Nobel offers smart coating technologies focused on corrosion resistance, antimicrobial protection, and self-cleaning surfaces. Its products are widely used in marine, infrastructure, and industrial applications, emphasizing sustainability and durability.
Selected Companies Active in Coatings and Related Technologies
- The Sherwin-Williams Company
- Axalta Coating Systems
- 3M Company
- BASF SE
- RPM International Inc.
- Jotun A/S
- Hempel A/S
- DuPont de Nemours, Inc.
Smart Coating Market Segments List
By Type
- Self-healing Coatings
- Microcapsule-based
- Intrinsic Polymer-based
- Anti-corrosion Coatings
- Epoxy-based
- Polyurethane-based
- Acrylic-based
- Anti-microbial Coatings
- Silver-based
- Copper-based
- Organic-based
- Anti-fouling Coatings
- Biocide-based
- Non-toxic foul-release
- Self-cleaning Coatings
- Hydrophobic
- Photocatalytic
By Function
- Protection
- Corrosion Resistance
- Wear & Abrasion Resistance
- Sensing
- Temperature-sensitive
- Pressure-sensitive
- Chemical-sensitive
- Self-repairing
- Aesthetic Enhancement
- Color-changing
- Anti-fingerprint
By End-use Industry
- Automotive
- OEM
- Aftermarket
- Aerospace & Defense
- Construction
- Residential
- Commercial
- Infrastructure
- Marine
- Healthcare
- Medical Devices
- Hospital Surfaces
- Electronics
- Energy
- Oil & Gas
- Renewable Energy
By Technology
- Nano-coatings
- Polymer-based Coatings
- Sol-gel Coatings
- Layer-by-layer Assembly
- Others
By Application Method
- Spray Coating
- Dip Coating
- Spin Coating
- Brush Coating
- Others
By Regions
- North America:
- U.S.
- Canada
- Mexico
- Rest of North America
- Latin America:
- Brazil
- Argentina
- Rest of Latin America
- Europe:
- Western Europe
- Germany
- Italy
- France
- Netherlands
- Spain
- Portugal
- Belgium
- Ireland
- UK
- Iceland
- Switzerland
- Poland
- Rest of Western Europe
- Eastern Europe
- Austria
- Russia & Belarus
- Türkiye
- Albania
- Rest of Eastern Europe
- Asia Pacific:
- China
- Taiwan
- India
- Japan
- Australia and New Zealand
- ASEAN Countries (Singapore, Malaysia)
- South Korea
- Rest of APAC
- MEA:
- GCC Countries
- Saudi Arabia
- United Arab Emirates (UAE)
- Qatar
- Kuwait
- Oman
- Bahrain
- South Africa
- Egypt
- Rest of MEA
- GCC Countries
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.