
Boron Nitride Powder Market Size, Competitive Landscape Analysis Report 2035
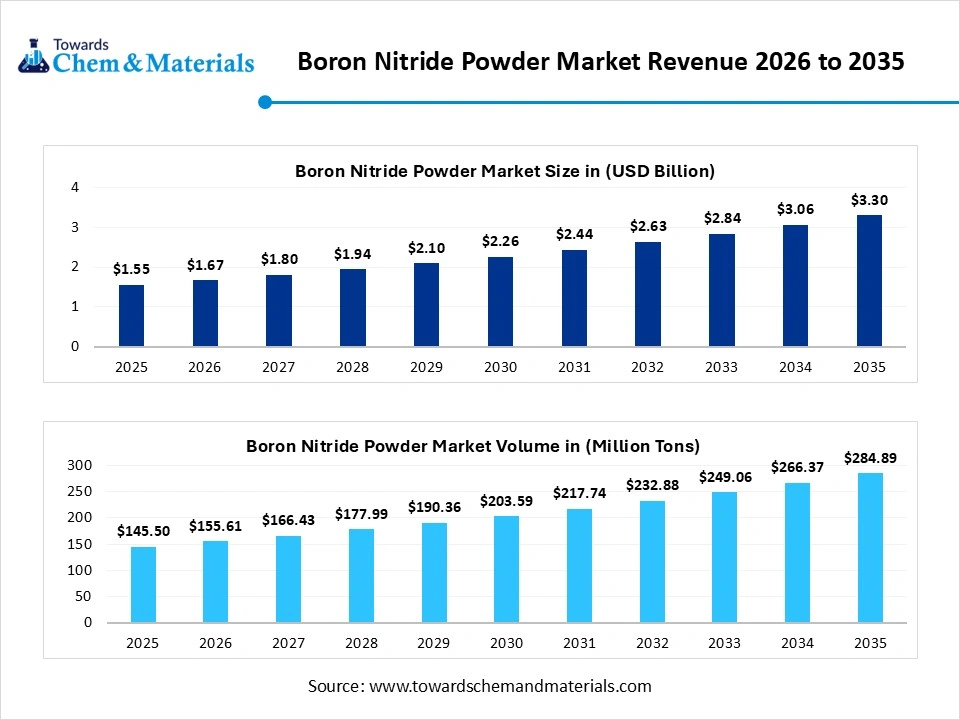
The global boron nitride powder market was valued at USD 1.55 billion in 2025, is estimated to reach USD 1.67 billion in 2026, and is projected to reach USD 3.3 billion by 2035, growing at a CAGR of 7.85% from 2026 to 2035. In terms of volume, the boron nitride powder market is projected to grow from 145.5 million tons in 2025 to 284.89 million tons by 2035. growing at a CAGR of 6.95% from 2026 to 2035.
Key Takeaways
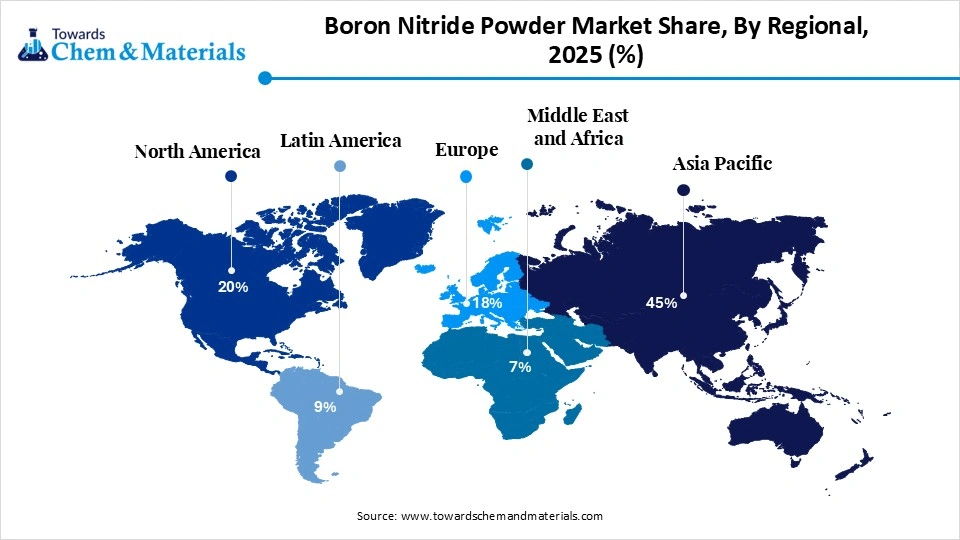
- By region, Asia Pacific dominated the boron nitride powder market by holding 45% share in 2025 and is expected to grow at the fastest CAGR of 8.6% over the forecast period.
- By region, North America held 22% market share in 2025 and expects notable growth with 7.20% CAGR during the forecast period.
- By type, the hexagonal boron nitride (h-BN) segment dominated the market with the largest share of 62% in 2025
- By type, the cubic boron nitride (c-BN) segment held 21% market share in 2025 and is expected to grow at the fastest CAGR of 8.6% over the forecast period.
- By grade, the industrial grade segment dominated the market with the largest share of 48% in 2025
By grade, the high-purity grade segment held 20% market share in 2025 and is expected to grow at the fastest CAGR of 9.1% over the forecast period. - By application, the thermal management segment dominated the market with the largest share of 28% in 2025 and is expected to grow at the fastest CAGR of 8.5% over the forecast period.
- By end-use industry, the electronics & semiconductor segment dominated the market with the largest share of 34% in 2025 and is expected to grow at the fastest CAGR of 8.7% over the forecast period.
- By form, the powder segment dominated the market with the largest share of 55% in 2025
By form, the suspension/dispersion segment held 25% market share in 2025 and is expected to grow at the fastest CAGR of 8.4% over the forecast period.
Market Size and Volume Forecast
- Market Estimated Size (2026): USD 1.67 Billion | CAGR (2026–2035): 7.85%
- Market Projected Size (2035): USD 3.30 Billion
- Market Volume (2025): 145.50 Tons | Volume CAGR (2026–2035): 6.95%
- Market Projected Volume (2035): 284.89 Tons
- Market Pricing (2025):
- Average Manufacturing Price (2025): USD 6,210 per Ton
- Average Selling Price (2025): USD 8,760 per Ton
- Pricing CAGR (2025–2035): 3.8%
Market Overview
Boron nitride powder is defined by its demand in high-performance modern engineering. It acts as a synthetic ceramic and thermal management solution that offers higher thermal conductivity and dielectric insulation in modern high-power electronics. The material serves as a solid-state lubricant and surface-energy modifier by ensuring tribological excellence.
The demand for technical purity, particle morphology driving the substantial investment in innovation and boron nitride powder adoption in aerospace, personal care, medical, and automotive industries. Additionally, emerging regional industrial expansion and focus on sustainable manufacturing make it a key material in operational safety and clean technology.
Boron Nitride Powder Market Trends
- Demand in High-Tech Manufacturing: The rising demand for thermal interface material and electrical insulation in EV, aerospace, electronics, defense, and semiconductors makes boron nitride a key material.
- Rising Focus on Green Synthesis: The stringent regulatory framework reinforce manufacture towards sustainable manufacturing, like plasma technology, to lower environmental impact in energy-heavy processes.
Key Technological Shifts and AI in the Boron Nitride Powder Market
- The market is a combination of artificial intelligence and boron nitride to enhance thermal stabilizer especially for AI-processor and 5G infrastructure. The technological shift is shifting the market towards intelligent material design and optimization in molecular synthesis.
- The emerging 3D chip stacking and GPU cooling are driving technological innovation. The commercialization of boron nitride nanotubes and the shift toward ultra-dense computing convert powder into dynamic and high-performance smart materials.
Supply Chain Analysis of the Boron Nitride Powder Market
Raw material Procurement:
The extraction of boron minerals and pre-processing into boric acid and boron trioxide. The stage depends on mineral purity and safe logistics.
- Key Players: Rio Tinto, Eti Maden, Minera Santa Rita, U.S. Borax, and American Elements
Boron Nitride Synthesis and Processing:
The chemical synthesis of boron with nitrogen at a high-temperature furnace to produce h-BN and c-BN powder through purification, milling, and surface treatment.
- Key Players: 3M Company, Momentive Technologies, Sain-Gobain, Kennametal Henze Bn, and Denka
End-Product Integration and Formulation:
The integration of BN powder into thermal interface materials, cosmetics, lubricants, semiconductors, and advanced ceramics.
- Key Players: Shin-Etsu Chemical, Honeywell, Intel, L'Oréal, BASF SE, Henkel, and Dow
Regulatory Framework: Boron Nitride Powder Market
| Region | Key Regulation | Regulatory Focus |
| North America | EPA standards, FDA, and TSCA | Focus on workplace safety with stringent reporting and regulation of the domestic supply chain for BN production and food contact |
| European Union | REACH Standards, EU Cosmetic Regulation, ECHA, and SSC | Sustainable product regulation and boron nitride nanomaterial annexure and standard for monitoring purity in a clean cosmetic framework. |
| Asia pacific | METI, China's five-year Plan and MEE | Chemical assessment focuses on the environmental stability of nitrides in electronic waste and industrial policy for boron-related chemical waste. |
| Global | GHS and ISO Regulation | Standard for characterizing boron nitride nanomaterials and safety data sheets to classify non-toxic inert dust for safe logistics. |
Boron Nitride Powder Market Dynamics
Driver
Integration and Commercialisation of Nanotechnology
The major leader focus n integration of nanotechnology, that boosting the shift towards boron nitride nanotube and nanosheets by ensuring higher mechanical strength and superior thermal stability for modern composites.
Restraints
Complexity in Synthesis
The boron nitride powder requires energy-intensive chemical vapor deposition and higher thermal synthesis that require high operational cost and limit the scalability of BN powder in price-sensitive sectors.
Opportunity
R&D Focuses on Healthcare and Energy Storage
The opportunity in the market is driving innovation for boron nitride biocompatibility and expansion in grid-scale energy storage, where h-BN improves safety, performance, and operation efficiency.
Segmental Insights
Type Insights
Hexagonal Boron Nitride (h-BN) Segment Dominated the Boron Nitride Powder Market with 62% of Market Share in 2025
Hexagonal boron nitride (h-BN) segment dominated the market with the largest share of 62% in 2025, driven by its balance of superior thermal conductivity and higher electrical insulation. It acts as a heat interface material in key applications, including semiconductor, electronics, and automotive sectors. The surge in 5G infrastructure and advancement in ceramic driving the demand for h-BN. Additionally, the segment is an essential high-temperature industrial lubricant and release agent that offers a low friction coefficient and chemical inertness.
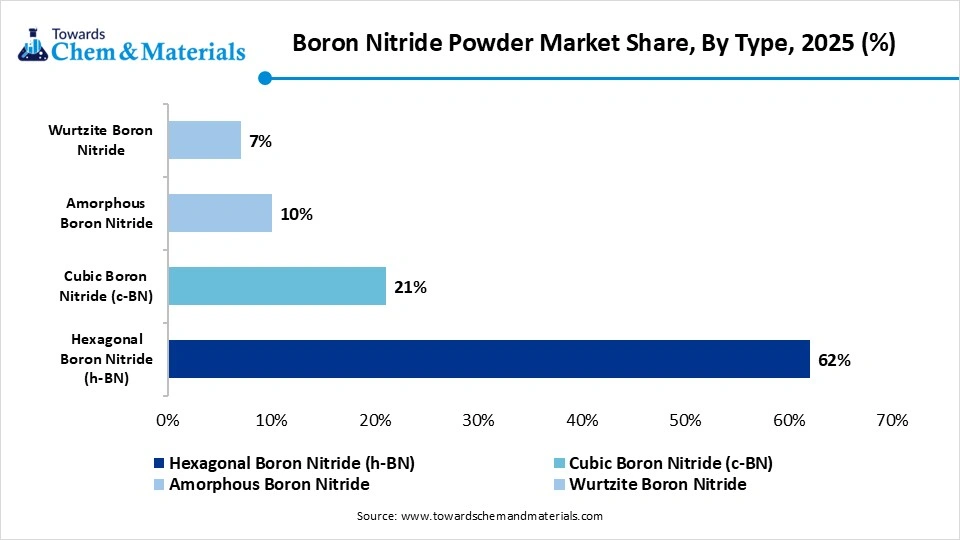
Cubic boron nitride (c-BN) segment held the 21% market share in 2025 and is expected to grow at the fastest CAGR of 8.6% over the forecast period. Represent as a key choice in precision grinding, processing of ferrous alloys, and heavy-duty machining by offering superior hardness, wear resistance, and chemical stability. The c-BN can maintain structural integrity, operational efficiency, and longevity in the aerospace and automotive industries. The segment is a key pillar for advanced manufacturing by ensuring tight tolerances for precision engineering.
Amorphous boron nitride segment held the 10% market share in 2025, serves as a key transforming type in the next generation of 5G/6G infrastructure and miniaturized processors. It is categorized by its disordered atomic structure and ultra-low dielectric constant by offering thermal consistency and preventing metal diffusion. In semiconductor it provides high-performance interlayer dielectric in nanoscale circuits, while in electronic its ensure uniformity for thin-film coating and optical barriers.
Wurtzite boron nitride segment held 7% market share in 2025, driven by its higher compressive strength and rock drilling for heavy-duty abrasives. This type is synthesized through shock-wave compression to create a hexagonal-pyramidal structure. The wurtzite boron nitride is the key choice for deep-sea drilling, aerospace defense, ballistic armor, and cutting-edge metallurgy that enable market expansion.
Grade Insights
The Industrial Grade Segment Dominated the Boron Nitride Powder Market with 48% of Market Share in 2025
The industrial grade segment dominated the market with the largest share of 48% in 2025, driven by rising high volume demand for rugged durability and cost-effective solutions for large-scale metallurgy, crucible coatings, and heavy-duty refractories. The industrial grade is optimized for bulk processing, where this material offers lubricity, reliable chemical stability, and higher release agent. The segment set a standard for the automotive, ceramics, and construction supply chain.
Boron Nitride Powder Market Share, By Grade, 2025 (%)
| By Grade | Revenue Share, 2025 (%) |
| Industrial Grade | 48% |
| Technical Grade | 32% |
| High-Purity Grade | 20% |
The technical grade segment held the 32% market share in 2025, driven by the requirement of high-reliability performance, enhancement in purity, and consistent particle size for precision engineering. The technical grade is a mid-level solution that strengthens mass-market scaling for high-value engineering polymers and automotive sensors by balancing optimized thermal flow and dielectric strength.
The high-purity grade segment held the 20% market share in 2025 and is expected to grow at the fastest CAGR of 9.1% over the forecast period, engineered for zero-defect performance in modern chip fabrication and quantum compounding innovation. The high-purity grade offers superior thermal conductivity and dielectric stability for sub-5nm semiconductor packaging, aerospace sensors, and vacuum furnace components. The surge in 5G and 6G infrastructure and high-power LED by maintaining key ultra-low oxygen content.
Application Insights
The Thermal Management Segment Dominated the Boron Nitride Powder Market with 28% of Market Share in 2025
The thermal management segment dominated the market with the largest share of 28% in 2025, and is expected to grow at the fastest CAGR of 8.5% over the forecast period, driven by its demand in high-density modern electronics. The boron nitride powder serves as a conductive filler, offering superior thermal conductivity and an efficient heat transfer system for EV battery modules, 5G hardware, power semiconductors, and AI processors. The segment shift towards the next generation of miniaturization and high-performance hardware is achieved by ensuring cooling efficiency and rapid heat dissipation.
The electronics & semiconductors segment held the 20% market share in 2025, driven by demand in power modules and microprocessors, by offering dielectric insulation, cooling, and heat dissipation. Boron nitride powder is key for advanced wafer manufacturing that boosts the surge for nanoscale chips and 6G connectivity by ensuring high-reliability performance in modern circuitry and technological supply chain.
Boron Nitride Powder Market Share, By Application, 2025 (%)
| By Application | Revenue Share, 2025 (%) |
| Thermal Management | 28% |
| Electrical Insulation | 16% |
| Coatings & Lubricants | 18% |
| Cosmetics | 8% |
| Electronics & Semiconductors | 20% |
| Metal Processing | 10% |
The coatings & lubricants segment held the 18% market share in 2025, acting as the most durable and dry-film barrier solution by offering lubricity and non-wetting properties. The material acts as a release agent in molten metal and glass manufacturing. Its ability to maintaining low coefficient of friction and chemical inertness for aerospace engines and high-pressure extrusion set standard for tool longevity and thermal processing operations.
The electrical insulation segment held 16% market share in 2025, known for its safety and dielectric barrier for power grids and fast-charging systems. The boron nitride powder is an insulating filler in high-frequency transformers, power electronics, motors and IGBT modules by offering high breakdown voltage and low dielectric constant, strengthening its presence in modern power electronics by ensuring reliability and safe miniaturization.
End-Use Industry Insights
The Electronics & Semiconductor Segment Dominated the Boron Nitride Powder Market with 34% of Market Share in 2025
The electronics & semiconductor segment dominated the market with the largest share of 34% in 2025, and is expected to grow at the fastest CAGR of 8.7% over the forecast period due to demand for boron nitride powder in modern wafer fabrication and advanced packaging by blending zero-electrical conductivity and higher intense heat loads. The electronics & semiconductor required rapid cooling and signal clarity in AI chips, power semiconductor and 5G networks by preventing system failure. Additionally, its rising demand is driving innovation and substantial investment by accelerating market growth.
The automotive segment held the 20% market share in 2025, due to a shift towards electric vehicles, where BN powder acts as a thermal dissipation and safety material in EV battery modules and power inverters. The technological scalability and large-scale demand foster innovation by ensuring charging efficiency and lowering mechanical friction. Additionally, its non-stick properties and lubricity are ideal for high-accuracy aluminum casting and engine components.
Boron Nitride Powder Market Share, By End-Use Industry, 2025 (%)
| By End-Use Industry | Revenue Share, 2025 (%) |
| Electronics & Semiconductor | 34% |
| Automotive | 20% |
| Aerospace & Defense | 12% |
| Industrial Manufacturing | 18% |
| Cosmetics & Personal Care | 6% |
| Energy & Power | 10% |
The industrial manufacturing segment held the 18% market share in 2025, driven by its demand in high-heat processing, refractory lining, and foundry applications where boron nitride powder offers a non-wetting nature, flawless surface finish, and longevity. The industrial expansion is driven by heavy-duty dry lubricant manufacturing and molten metal handling, ensuring clean and high-precision separation in the global supply chain.
The aerospace & defense segment held 12% market share in 2025. It acts as a thermal protection material for rocket and hypersonic vehicles by ensuring structural stability. In defense electronics, BN powder offers radar-transparent properties by enabling signal transmission. The material is a combination of lightweight resilience and chemical stability, setting a standard for space exploration and advanced weaponry.
Form Insights
The Powder Segment Dominated the Boron Nitride Powder Market with 55% of Market Share in 2025
The powder segment dominated the market with the largest share of 55% in 2025. The expansion is driven by its dispersibility, purity, and optimization in surface area into greases, polymers, and composite materials. The powder particle morphologies create high-performance fillers by acting as raw materials for industrial lubricants, advanced ceramics, EV thermal pads, and 5G chipsets by ensuring a resilient and versatile delivery system.
Boron Nitride Powder Market Share, By Form, 2025 (%)
| By Form | Revenue Share, 2025 (%) |
| Powder | 55% |
| Granules | 20% |
| Suspension/Dispersion | 25% |
The suspension/dispersion segment held the 25% market share in 2025 and is expected to grow at the fastest CAGR of 8.4% over the forecast period, because its liquid solution is engineered for flawless surface coverage and integrated automation. This form enable uniform, micro-thin block for high-speed foundry lines and precision glass manufacturing by preventing particle agglomeration. The segment is required for large-scale and high-purity industrial workflows.
The granules segment held the 20% market share in 2025 due to its highly efficient delivery system that provides consistent dosing and higher bulk density for automated manufacturing scale. The granules are key for advanced ceramic pressing and extrusion by maintaining cleanroom safety and superior production. Overall, granules maximize operational precision for the manufacturing of semiconductor and high-performance thermal insulators.
Regional Insights
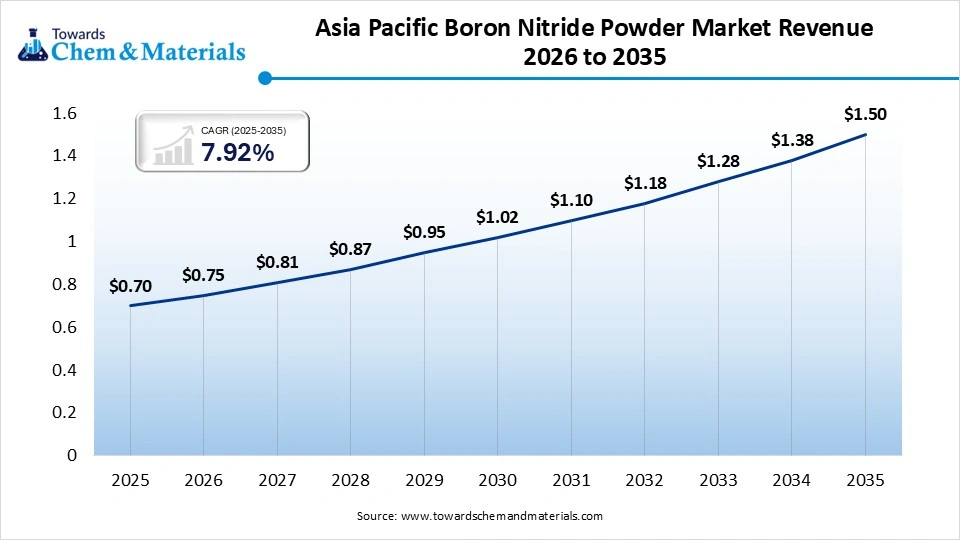
The Asia Pacific boron nitride powder market size was estimated at USD 0.70 billion in 2025 and is projected to reach USD 1.50 billion by 2035, growing at a CAGR of 7.92% from 2026 to 2035 The region integrating boron nitride powder in the advanced electric vehicle supply chain and semiconductor fabrication. The domestic player is shifting towards next-generation thermal interface materials and innovation in chemical synthesis, positioning the region as a key pillar of the industrial ecosystem.
China Boron Nitride Powder Market Growth Trends
China market is characterized by its high-tech consumption and large-scale manufacturing by combining a vertically integrated supply chain. China is a leader in the electric vehicle transition and semiconductor infrastructure. The R&D project supported by the government focuses on advancing heat management and next-generation thermal materials to meet regulatory compliance.
North America Boron Nitride Powder Market Growth Trends
North America held the 22% market share in 2025 and expects notable growth in the market with 7.20% CAGR during the forecast period, defined by its strategic onshoring and substantial investment for domestic innovation to achieve a resilient supply chain. The region demands bulk volume in industrial applications, including aerospace, power electronics, defense, and semiconductor. Additionally, North America uses these powders in next-generation AI chips and satellite hardware by strengthening regional dominance in mission-critical applications.
U.S. Boron Nitride Powder Market Growth Trends
The United States market is represented by its technical refinement and its specialized boron nitride grade. The region's demand for extra-high purity material in the domestic semiconductor, aerospace, and automotive sectors. The U.S. based national federal initiative aligns with a public-private partnership through extensive investment focus on local synthesis by ensuring a self-sufficient supply chain.
Recent Developments
- In April 2026, Stanford Advanced Materials announced the launch of 99.99% pure pyrolytic boron nitride crucibles to ensure contamination and thermal instability in compound semiconductor crystal growth.
- In February 2024, Saint-Gobain Boron Nitride announced the achievement of a platinum medal from EcoVadis as a top 1% company for sustainability performance. Saint-Gobain's overall score of 83/100 for its Amherst site and Ecovadis assessment focus 4 core themes, including labor & human rights. Sustainable procurement, ethics, and environment.
Boron Nitride Powder Market Competitive Landscape Analysis
Tier 1 Companies
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
|---|---|---|---|---|---|
| 1 | Saint-Gobain S.A. | Courbevoie, Île-de-France | France | Global leader in advanced ceramic materials and boron nitride technologies | Hexagonal boron nitride powders, cubic boron nitride abrasives, advanced ceramics |
| 2 | Momentive Technologies LLC | Strongsville, Ohio | United States | One of the world's leading suppliers of engineered boron nitride materials | Hexagonal BN powders, BN coatings, thermal management materials |
| 3 | Denka Company Limited | Tokyo | Japan | Major producer of high-purity boron nitride for electronics and industrial applications | Boron nitride powders, ceramic fillers, thermal interface materials |
| 4 | 3M Company | Saint Paul, Minnesota | United States | Significant supplier of specialty ceramic and thermal management materials utilizing BN technologies | Boron nitride fillers, thermal conductivity materials, specialty ceramics |
Tier 2 Companies
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
|---|---|---|---|---|---|
| 1 | Höganäs AB | Höganäs, Skåne County | Sweden | Active supplier of advanced powders including specialty ceramic materials | Boron nitride powders, engineered powder materials |
| 2 | Tokuyama Corporation | Tokyo | Japan | Important producer of specialty ceramic materials and BN powders | Hexagonal boron nitride, advanced ceramic powders |
| 3 | H.C. Starck Tungsten GmbH | Goslar, Lower Saxony | Germany | Supplier of high-performance ceramic and refractory materials | Boron nitride powders, technical ceramics, specialty materials |
| 4 | Ferro-Ceramic Grinding Inc. | Wakefield, Massachusetts | United States | Specialized producer and processor of technical ceramic materials | Boron nitride powders, machinable ceramics |
Tier 3 Companies
| Rank | Company Name | Headquarters | Country | Why Relevant to This Market | Key Products / Material Portfolio |
|---|---|---|---|---|---|
| 1 | Qingzhou Fangyuan New Material Co., Ltd. | Qingzhou, Shandong | China | Specialized producer of boron nitride powders for industrial and electronics applications | Hexagonal boron nitride powders, BN ceramics |
| 2 | Pengda Advanced Ceramics Co., Ltd. | Dalian, Liaoning | China | Growing supplier of boron nitride and technical ceramic products | Boron nitride powders, ceramic components |
| 3 | Combat Boron Nitride | Palm Bay, Florida | United States | Specialized BN supplier serving aerospace, industrial, and research applications | Boron nitride powders, machinable BN components |
| 4 | Kennametal Inc. | Pittsburgh, Pennsylvania | United States | Active participant in cubic boron nitride-based tooling and abrasive applications | Cubic boron nitride abrasives, superhard materials |
Top Companies in the Boron Nitride Powder Market
- Merck
- 3M Company
- Denka Company Limited
- ACS Material
- Advanced Abrasives
- ESPI METALS
- Henze Boron Nitride Products AG
- LGC Group
- MaTeck
- 3M Company
- Momentive Performance Materials
- American Elements
- H.C. Starck GmbH
- Resonac Holdings
- Nanografi Nanotechnology AS
- Nanoshel LLC
- Pacific Particulate Materials
- Saint-Gobain
- ZYP Coatings
- Dandong Chemical Engineering Institute
- Haihang Industry
- TANYUN
Boron Nitride Powder Market Segment List
By Type
- Hexagonal Boron Nitride (h-BN)
- Standard Grade
- High Purity Grade
- Cubic Boron Nitride (c-BN)
- Abrasive Grade
- Coating Grade
- Amorphous Boron Nitride
- Wurtzite Boron Nitride (w-BN)
By Grade
- Industrial Grade
- Technical Grade
- High-Purity Grade
- 99% Purity
- 99.5%+ Purity
By Application
- Thermal Management
- Thermal Interface Materials
- Heat Sink Fillers
- Electrical Insulation
- Coatings & Lubricants
- Solid Lubricants
- Protective Coatings
- Cosmetics
- Electronics & Semiconductors
- Metal Processing
- Mold Release Agents
- Crucibles
By End-Use Industry
- Electronics & Semiconductor
- Automotive
- EV Components
- Engine Components
- Aerospace & Defense
- Industrial Manufacturing
- Cosmetics & Personal Care
- Energy & Power
By Form
- Powder
- Fine Powder
- Ultra-Fine Powder
- Granules
- Suspension/Dispersion
By Region
- North America:
- U.S.
- Canada
- Mexico
- Rest of North America
- Latin America:
- Brazil
- Argentina
- Rest of Latin America
- Europe:
- Western Europe 
- Germany
- Italy
- France
- Netherlands
- Spain
- Portugal
- Belgium
- Ireland
- UK
- Iceland
- Switzerland
- Poland
- Rest of Western Europe
- Eastern Europe
- Austria
- Russia & Belarus
- Türkiye
- Albania
- Rest of Eastern Europe
-  Asia Pacific:
- China
- Taiwan
- India
- Japan
- Australia and New Zealand,
- ASEAN Countries (Singapore, Malaysia)
- South Korea
- Rest of APAC
- MEA:
- GCC Countries
- Saudi Arabia
- United Arab Emirates (UAE)
- Qatar
- Kuwait
- Oman
- Bahrain
- South Africa
- Egypt
- Rest of MEA
- GCC Countries
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.