
Biomaterials Market Size and Forecast 2024 to 2034
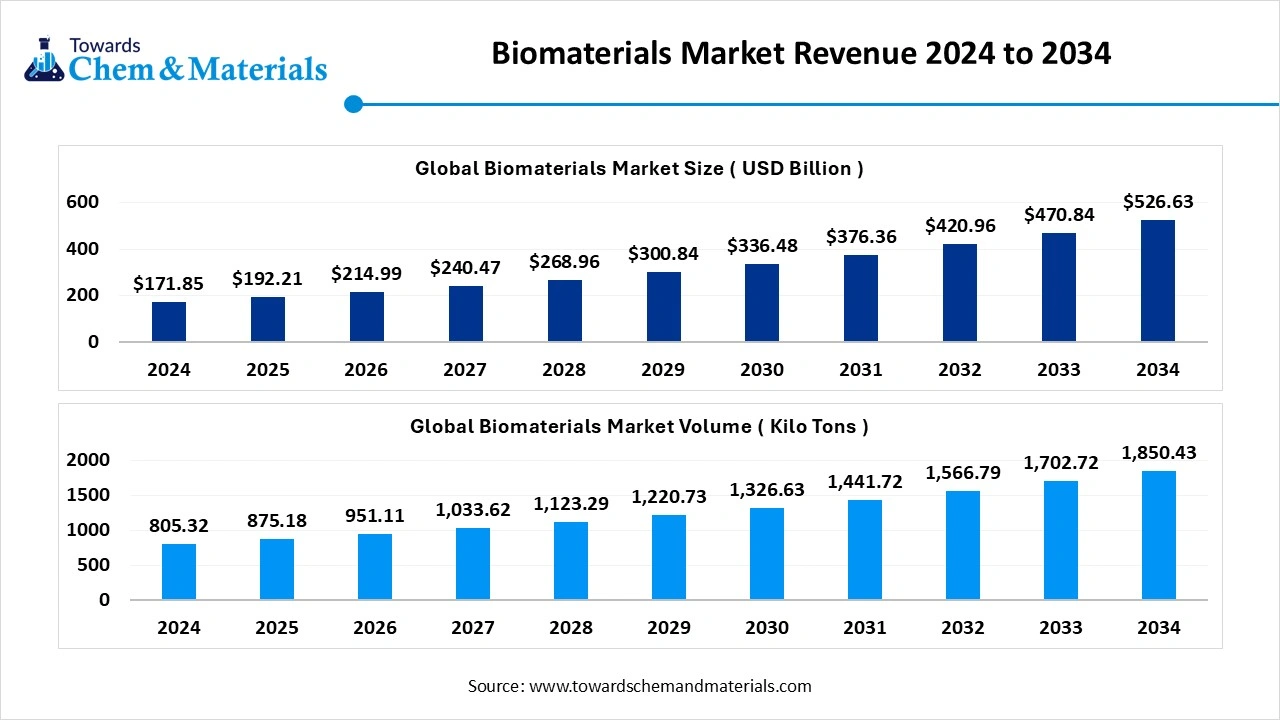
The global biomaterials market size was valued at USD 171.85 billion in 2024 and is anticipated to reach around USD 526.63 billion by 2034, growing at a CAGR of 11.85% from 2025 to 2034.
The global biomaterials market volume was reached at 805.32 kilo tons in 2024 and is expected to be worth around 1850.43 kilo tons by 2034, growing at a compound annual growth rate (CAGR) of 8.68% over the forecast period 2025 to 2034. The growth of the market is driven by the growing demand for sustainable and eco-friendly materials, and due to the rising prevalence of chronic diseases with an increased aging population, which fuels the growth.
Key Takeaways
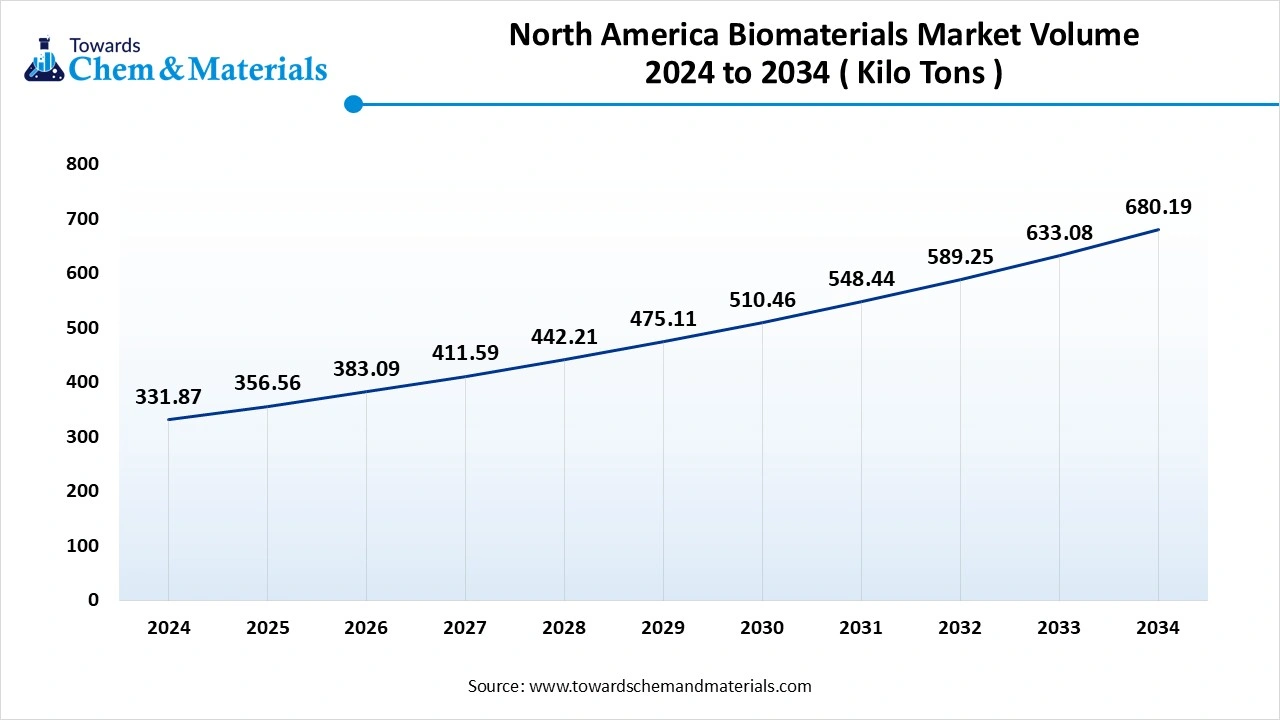
- The North America biomaterials market Volume is estimated at 356.56 Kilo Tons in 2025 and is expected to reach 680.19 Kilo Tons by 2034, growing at a CAGR of 7.44% from 2025 to 2034.
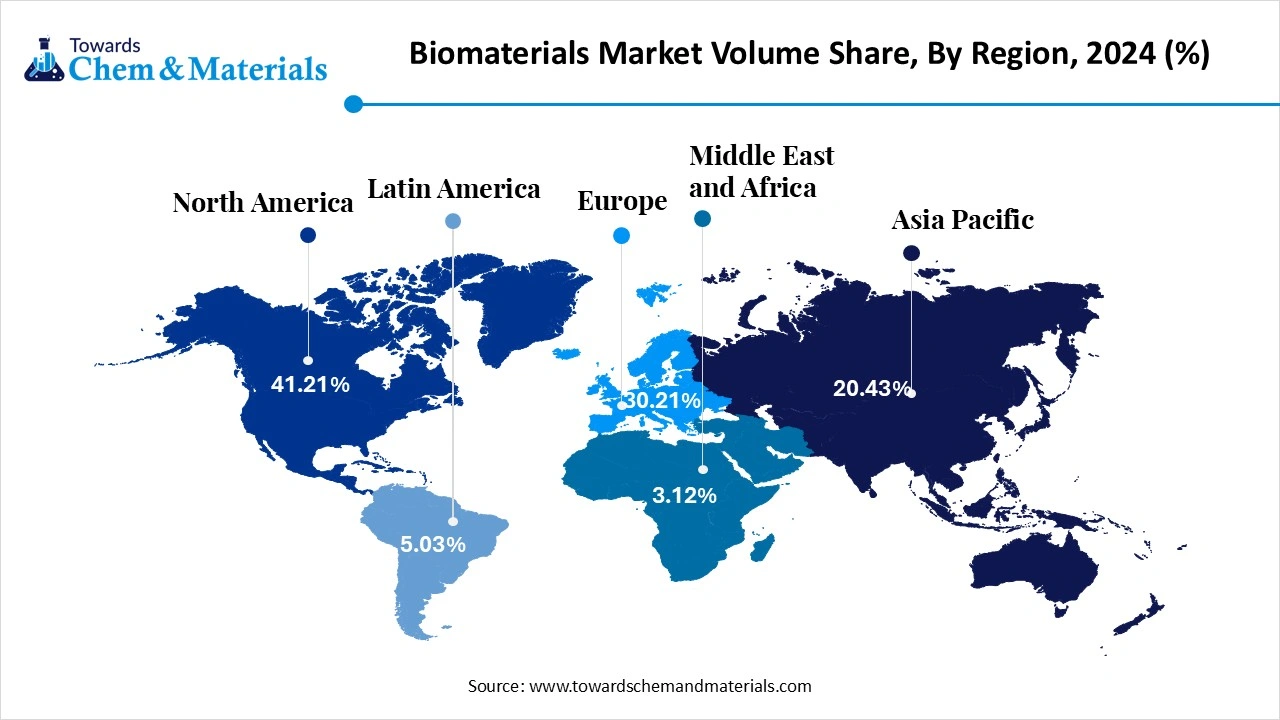
- The North America biomaterials market held the largest volume share of 41.21% of the global market in 2024.
- The Asia Pacific biomaterials market is expected to register the fastest CAGR of 14.96% over the forecast period by 2025-2034.
- By Material Type, the synthetic biomaterials segment dominated the market with the largest volume share of 73.34% in 2024.
- By Material Type, the natural biomaterials segment is projected to grow at the fastest CAGR of 13.15% over the forecast period by 2025-2034.
- By application, the orthopaedic segment dominated the market in 2024. The orthopaedic segment held a 35% share in the market in 2024. The growing application in the department fuels the growth of the market.
- By application, the tissue engineering segment is expected to grow in the forecast period. The technological advancements in the procedure and materials drive the growth.
Market Overview
Rising Demand For Durable Materials: Biomaterials Market To Expand
The biomaterials market refers to the global industry involving the development, manufacturing, and application of natural or synthetic materials engineered to interact with biological systems for medical purposes, either as a therapeutic (e.g., implants, scaffolds) or a diagnostic aid. These materials are used in fields such as tissue engineering, regenerative medicine, orthopaedics, cardiovascular, dental, and wound healing.
What Are The Key Growth Drivers Responsible For The Growth Of The Biomaterials Market?
The growth of the market is driven by the growing aging population and increased prevalence of chronic diseases like cardiovascular disease and orthopaedic conditions, which increases the demand for medical equipment. Advancements in material science and rising demand for medical devices and implants with minimally invasive surgeries surge the demand for the market, which propels growth.
The Government funding and research for innovative and advanced biomaterial technologies drive the demand for the market. Other key growth drivers are customization and personalization, like 3D printing and other advanced technologies, fueling the growth. The growing healthcare industry in emerging economies is due to increasing healthcare investments, and the adoption of advanced medical technologies boosts the growth and expansion of the market.
Market Trends
- The rising demand for biodegradable materials that can be absorbed by the body safely fuels the growth of the market.
- The growing demand for 3D printing for revolutionizing the design and manufacturing of medical implants and devices for complex and patient monitoring increases the growth of the market.
- The growing focus on sustainability and demand for sustainable biomaterials boosts the growth of the market.
- The growing application in cardiovascular and orthopaedic applications drives the growth of the market.
Report Scope
| Report Attribute | Details |
| Market Volume in 2025 | 875.18 Kilo Tons |
| Expected Volume by 2034 | 1850.43 Kilo Tons |
| Growth Rate from 2025 to 2034 | 8.68% |
| Base Year of Estimation | 2024 |
| Forecast Period | 2025 - 2034 |
| Dominant Region | North America |
| Segment Covered | By Material Type , By Application , By Region |
| Key Companies Profiled | Evonik Industries AG , BASF SE, Covestro AG , Corbion N.V. , DSM Biomedical , Berkley Advanced Biomaterials , Zimmer Biomet Holdings, Inc. , Medtronic plc , Stryker Corporation , Johnson & Johnson (DePuy Synthes), Royal DSM , Celanese Corporation , Invibio Ltd (Victrex plc) , NUSIL (Avantor) , Bioretec Ltd , CoorsTek Medical , Aran Biomedical , REVA Medical, LLC , Astra Tech (Dentsply Sirona) , Acumed LLC |
Market Opportunity
What Are The Key Growth Opportunities That Influence The Growth Of The Biomaterials Market?
The growing application in various departments created a great opportunity for the growth of the market. The application in cardiovascular, orthopaedic, and dental for dental implants, bone grafts, restorative materials, tissue regeneration, wound healing, development of artificial organs, in cardiovascular diseases for the development of stents, artificial heart valves, and other cardiovascular devices, which increases the growth of the market. The growing demand for spinal implants, joint replacements, and other orthopaedic procedures also increases the growth and expansion of the market, creating great opportunities for growth.
Market Challenge
What Are The Key Challenges That Limit The Growth Of The Biomaterials Market?
The key challenges that limit the growth of the market are the high development costs and regulatory hurdles. The development of biomaterials requires heavy investments in research with financial inputs, which limits the growth of the market. The stringent biocompatibility and toxicity testing delays product approvals. The limited availability and cost of materials, which are expensive, affect and hinder the affordability, which leads to disruption of the supply chain, which limits the growth and expansion of the market.
Segmental Insights
Material Type Insights
Which Material Type Segment Dominated The Biomaterials Market In 2024?
The synthetic biomaterial segment the synthetic biomaterial segment dominated the market in 2024. Synthetic biomaterials are man-made compounds such as polymers, ceramics, and metals engineered to perform specific biological functions. These materials offer superior strength, controlled degradation rates, and design flexibility, making them ideal for orthopedic implants, dental devices, cardiovascular stents, and drug delivery systems. Common examples include polyethylene, polylactic acid (PLA), titanium alloys, and bioinert ceramics. Their consistent quality, scalability, and adaptability to advanced manufacturing methods like 3D printing drive widespread use. Continued innovation in surface modification and composite formulation is enhancing tissue integration and reducing rejection risks, ensuring synthetic biomaterials remain a dominant force across diverse medical applications.
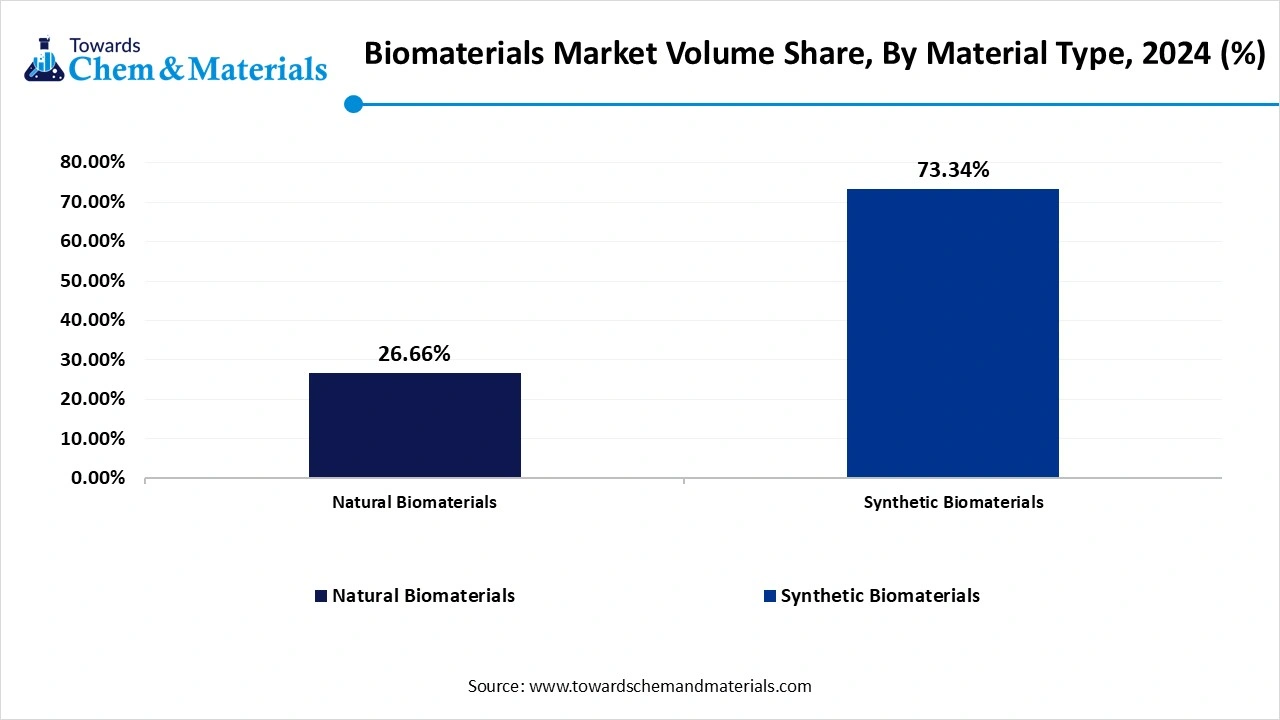
The natural biomaterial segment is expected to experience notable growth in the market. Natural biomaterials are derived from biological sources such as collagen, gelatin, chitosan, alginate, silk, and hyaluronic acid, and are widely used for their excellent biocompatibility and biodegradability. These materials play a vital role in wound healing, tissue engineering, drug delivery, and surgical sutures. The segment is gaining traction due to growing preference for bio-based, non-toxic materials that integrate well with human tissues. Advances in processing techniques and material customization have improved their mechanical properties and stability. As research progresses in regenerative medicine and cell therapy, natural biomaterials continue to be a key focus area, especially in soft tissue applications..
Biomaterials Market Volume Share, By Material Type, 2024-2034 (%)
| By Material Type | Volume Share, 2024 (%) | Market Volume - 2024 | Volume Share, 2034 (%) | Market Volume - 2034 | CAGR (2025 - 2034) |
| Natural Biomaterials | 26.66% | 214.70 | 35.27% | 652.65 | 13.15% |
| Synthetic Biomaterials | 73.34% | 590.62 | 64.73% | 1197.78 | 8.17% |
| Total | 100.00% | 805.32 | 100.00% | 1850.43 | 8.68% |
Application Insights
How Did Orthopaedic Segment Dominated The Biomaterials Market In 2024?
The orthopaedic segment dominated the market in 2024. Orthopaedic applications form the largest segment of the market, driven by rising incidences of bone injuries, osteoarthritis, and joint replacement surgeries. Biomaterials are extensively used in hip and knee replacements, spinal implants, fracture fixation, and bone graft substitutes. The growing aging population, advancements in surgical techniques, and increasing sports-related injuries are fueling demand. Innovations in bioresorbable materials, 3D-printed implants, and surface-modified metals are enhancing compatibility and long-term performance. With hospitals and orthopaedic clinics increasingly adopting advanced implants and fixation devices, this segment continues to lead in both revenue and technological development across the global market.
The tissue engineering segment expects significant growth in the market during the forecast period. Tissue engineering is an emerging and rapidly growing application segment in the market, focused on regenerating or replacing damaged tissues and organs using scaffolds, cells, and biologically active molecules. Biomaterials play a critical role in creating supportive structures for cell growth and tissue regeneration, especially in skin, bone, cartilage, and vascular engineering. This segment is driven by advancements in stem cell research, 3D bioprinting, and bioactive material development. Increasing demand for organ replacement, wound healing solutions, and customized grafts is accelerating adoption. Despite being in its early stages commercially, tissue engineering holds immense potential for transforming future regenerative medicine.
Regional Insights
How Did North America Dominate The Biomaterials Market In 2024?
The North America biomaterials market volume was estimated at 331.87 Kilo Tons in 2024 and is anticipated to reach 680.19 Kilo Tons by 2034, growing at a CAGR of 7.44% from 2025 to 2034.
North America dominated the biomaterials market in 2024. The growth of the market is driven by the presence of strong research and advanced technology in the region and robust infrastructure development, which propels the demand for the market. The growing aging population, which leads to a rising prevalence of chronic diseases which increases the demand for the market. The advancement in medical technology, like novel biomaterials with improved biocompatibility and performance, with the help of government initiatives and funding in healthcare infrastructure development and for research in the region, further fuels the growth and expansion of the market.
U.S. Significant Growth In The Biodegradable Materials Fuels The Growth Of The Market.
The U.S. has seen significant growth driven by the growing focus on biodegradable materials for tissue engineering and regenerative medicine influences the growth of the market. The adoption of advanced biomaterials is increasing in the country, such as 3D printed implants and personalized medical devices, which is surging the growth of the market. Companies in the country are focusing on mergers and acquisitions, which expand their presence and product, along with ensuring product safety and efficiency, boosting the growth of the market.
The Growing Government Initiatives Boost The Growth Of The Market In The Asia Pacific.
Asia Pacific is expected to have significant growth in the biomaterials market in the forecasted period. The supportive government initiatives and policies in the region foster investment and market growth, which further increases the demand. Other key drivers are technological advancements, the growing medical tourism, and the growing demand for biomaterials due to their applications and for building implants for medical, which further increases the growth of the market, aligning with the rapid growth of natural biomaterials, boosting the growth and expansion of the market.
India Has Seen Significant Growth In The Market, Driven By Technological Advancements.
The growth of the market is driven by technological advancements like innovation in biomaterials and the development of new polymers, ceramics, and natural biomaterials further fuels the growth of the market. The technological advancements are also supported by the government funding and support for research and development of biomaterials, which drives the growth in the country. The key players like Medtronic PLC, Evonik Industries AG, Carpenter Technology Corporation, BASF SE, Corbion, CoorsTeck Inc., and Stryker play a major role in the growth of the market, supporting the expansion of the market in the country.
- The United States shipped out 3000 Dental Materials shipments. These exports were handled by 375 United States exporters to 445 buyers.(Source : www.volza.com)
- Globally, India, Germany, and Japan are the top three exporters of Dental Materials. India is the global leader in Dental Materials exports with 26,150 shipments, followed closely by Germany with 23,635 shipments, and Japan in third place with 17,241 shipments.(Source: www.volza.com)
Biomaterials Market Volume Share, By Region, 2024-2034 (%)
| By Region | Volume Share, 2024 (%) | Market Volume - 2024 | Volume Share, 2034 (%) | Market Volume - 2034 | CAGR (2025 - 2034) |
| North America | 41.21% | 331.87 | 34.21% | 680.19 | 7.44% |
| Europe | 30.21% | 243.29 | 27.01% | 499.80 | 8.33% |
| Asia Pacific | 20.43% | 164.53 | 31.19% | 577.15 | 14.96% |
| Latin America | 5.03% | 40.51 | 4.54% | 84.01 | 8.44% |
| Middle East & Africa | 3.12% | 25.13 | 3.05% | 56.44 | 9.41% |
| Total | 100% | 805.32 | 100% | 1850.43 | 8.68% |
Recent Developments
- In April 2025, Northern Illinois University launched a new line of biomaterials and tissue engineering laboratory to improve and for an efficient biomedical engineering programme, which helps students experiment with innovative technology and creates opportunities with advanced analysis tools.(Source: cleanroomtechnology.com)
- In April 2025, Covation Biomaterials announced the launch of its innovation, CovationBio bioPTMEG, an advanced polytetramethylene ether glycol (PTMEG) that helps in reducing environmental impact amid growing environmental concerns, which offers high performance.(Source: worldbiomarketinsights.com )
Top Companies List
- Evonik Industries AG
- BASF SE
- Covestro AG
- Corbion N.V.
- DSM Biomedical
- Berkley Advanced Biomaterials
- Zimmer Biomet Holdings, Inc.
- Medtronic plc
- Stryker Corporation
- Johnson & Johnson (DePuy Synthes)
- Royal DSM
- Celanese Corporation
- Invibio Ltd (Victrex plc)
- NUSIL (Avantor)
- Bioretec Ltd
- CoorsTek Medical
- Aran Biomedical
- REVA Medical, LLC
- Astra Tech (Dentsply Sirona)
- Acumed LLC
Segments Covered
By Material Type
- Natural Biomaterials
- Collagen
- Gelatin
- Fibrin
- Cellulose
- Alginate
- Silk
- Chitosan
- Hyaluronic Acid
- Starch-based Biomaterials
- Synthetic Biomaterials
- Polymers
- Polylactic Acid (PLA)
- Polyglycolic Acid (PGA)
- Polycaprolactone (PCL)
- Polyethylene Glycol (PEG)
- Polyurethane (PU)
- Polyetheretherketone (PEEK)
- Ceramics
- Alumina
- Zirconia
- Calcium Phosphates (e.g., Hydroxyapatite)
- Bioactive Glass
- Metals
- Stainless Steel
- Titanium & Titanium Alloys
- Cobalt-Chromium Alloys
- Magnesium Alloys
- Composites
- Polymer-Ceramic Composites
- Metal-Polymer Composites
- Carbon Fiber-Reinforced Composites
By Application
- Orthopaedic
- Joint Replacements
- Bone Grafts & Substitutes
- Spine Implants
- Cardiovascular
- Stents
- Heart Valves
- Vascular Grafts
- Dental
- Dental Implants
- Tissue Regeneration
- Wound Healing
- Dressings
- Skin Substitutes
- Plastic Surgery
- Soft Tissue Fillers
- Breast Implants
- Neurology
- Neural Implants
- Nerve Regeneration Scaffolds
- Ophthalmology
- Contact Lenses
- Intraocular Lenses
- Drug Delivery
- Injectable Biomaterials
- Microspheres & Nanoparticles
- Tissue Engineering
- Scaffolds
- Hydrogels
- Others
- Urological Applications
- Gastrointestinal Stents
By Region
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Sweden
- Denmark
- Norway
- Asia Pacific
- China
- Japan
- India
- South Korea
- Thailand
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East and Africa (MEA)
- South Africa
- UAE
- Saudi Arabia
- Kuwait
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.