
Europe Chemical Recycling of Plastics Market Size, Trends, Share, and Innovations
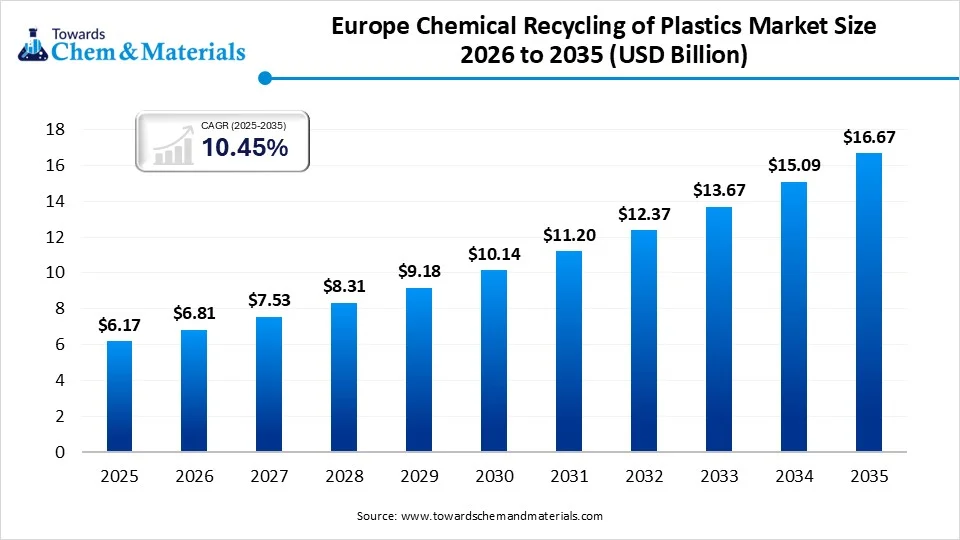
The Europe chemical recycling of plastics market size was valued at USD 6.17 billion in 2025, is estimated to reach USD 6.81 billion in 2026, and is projected to reach USD 16.67 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 10.45% over the forecast period from 2026 to 2035. The physical infrastructure tells a more conservative story. Europe's chemical/advanced recycling landscape comprised approximately 18 operating plants with 289 ktpa of combined capacity, against approximately 2.8 Mtpa of additional planned capacity across 65 projects as of the latest detailed project mapping.
Approximately 262 ktpa of operating capacity was pyrolysis-based, compared with 19 ktpa of solvolysis and 8 ktpa of solvent-based capacity. Nine projects representing approximately 819 ktpa had already been discontinued, highlighting the difference between the announced pipeline and bankable capacity.
The addressable feedstock pool is substantially larger. EU-27 plastic production was approximately 57.9 Mt in 2022, while approximately 42.5 Mt of plastic waste was generated in the EU in the same year. Only around one-fifth of total plastic waste was recycled, leaving substantial material flows for technologies capable of processing difficult-to-recycle fractions. Packaging is particularly important: the EU generated approximately 15.8 Mt of plastic packaging waste in 2023, of which approximately 42.1% was recycled.
Key Coverage
- 2025 market revenue and 2035 forecast
- Operating versus announced chemical-recycling capacity
- Technology, polymer, and application segmentation
- Feedstock availability and supply economics
- Regulatory and mass-balance developments
- European country opportunity mapping
- Company capacity, technology, and strategic positioning
- Investment, M&A, and project pipeline intelligence
Market Size & Forecast - Revenue Growth Is Strong, but Physical Capacity Must Catch Up
The European market is estimated at approximately USD 5.74 billion in 2025 and USD 6.21 billion in 2026, with an estimated USD 13.64 billion opportunity by 2035. The implied incremental revenue opportunity from 2025 to 2035 is approximately USD 7.9 billion. Depolymerization represents the largest technology revenue pool, with an estimated 49.0% share in 2025.
A second lens based on physical throughput produces a much more conservative picture. Operating capacity remains below 0.3 Mtpa, while announced/planned capacity is nearly 2.8 Mtpa. This means the principal market constraint is not the availability of potential feedstock but the successful conversion of projects into reliable, economically competitive operating assets.
The full analysis therefore distinguishes market revenue, waste-processing capacity, recycled-output capacity, nameplate capacity, commissioning capacity, and actual utilization, rather than treating these metrics as interchangeable.
Key Coverage
- 2021-2025 historical development
- 2025-2035 revenue forecast
- Capacity-based market model
- Base/upside/downside scenarios
- Incremental revenue opportunity
- Operating versus planned capacity
- Country-level forecasts
- Technology-level forecasts
Segmentation Analysis—Pyrolysis Dominates the Capacity Pipeline, While Depolymerization Captures a Large Value Pool
The market is segmented primarily by technology, polymer/feedstock, output, application, and geography.
Pyrolysis is the dominant infrastructure pathway. Across operating and planned European chemical-recycling projects, pyrolysis accounts for approximately 1.94 Mtpa of combined technology capacity, compared with approximately 860 ktpa for gasification, 102 ktpa for solvolysis, 68 ktpa for solvent-based technologies, 50 ktpa for enzymatic processes, and 70 ktpa for hydrothermal processes.
By polymer, the principal opportunity centers on PE, PP, PET, PS, and mixed-polyolefin waste, with technology economics differing substantially by feedstock purity. PET and other condensation polymers provide attractive depolymerization opportunities where high-purity monomer recovery is feasible, while mixed PE/PP streams are more strongly associated with thermochemical routes.
Packaging is the principal downstream demand pool because of its large waste base and increasing recycled-content requirements. Automotive, electronics, construction, textiles, and consumer products provide additional high-value applications where recycled material must meet demanding technical or purity specifications.
Key Coverage
- Pyrolysis, gasification, depolymerization, dissolution, solvolysis, and enzymatic routes
- PE, PP, PET, PS, PVC, and mixed plastics
- Packaging, automotive, electronics, construction, and textile applications
- Revenue and capacity by technology
- Growth contribution by polymer
- Country and application segmentation
Market Dynamics—Regulation Creates Demand, but Feedstock, Energy, and Project Economics Determine Conversion
The principal growth driver is the structural requirement to increase recycled content while maintaining virgin-like material performance. The new European packaging framework establishes minimum recycled-content requirements for plastic packaging from 2030, including 35% for specified categories of plastic packaging, with higher requirements scheduled for 2040.
The market is simultaneously constrained by energy intensity, feedstock preprocessing costs, contamination, yield losses, product-quality consistency, and competition with relatively inexpensive virgin polymers. The project pipeline itself demonstrates this risk: approximately 819 ktpa of announced chemical-recycling capacity had been cancelled in the mapped European project universe.
The resulting competitive battleground is shifting from technology demonstration toward feedstock security, plant utilization, downstream integration, certification, and long-term offtake contracts.
Key Coverage
- Recycled-content mandates
- Feedstock availability
- Energy and utilities costs
- Project economics
- Technology yield
- Product quality
- Offtake structures
- Investment barriers
Pricing Analysis—Circular Feedstock Commands a Premium Only When Regulatory and Technical Value Is Monetized
Chemical-recycling economics are driven by a combination of waste-feedstock cost, preprocessing cost, conversion yield, energy consumption, capital recovery, downstream upgrading, and circular-polymer premiums.
Unlike conventional commodity recycling, pricing can involve several linked transactions: waste-gate fees, pyrolysis-oil or intermediate-feedstock prices, recycled monomer prices, polymer premiums, and mass-balance certificates. Consequently, a single €/tonne benchmark is insufficient.
The commercial premium is particularly relevant for applications where mechanically recycled material cannot meet purity, odor, color, or food-contact requirements. However, the premium must compensate for higher conversion costs and capital intensity. The analysis therefore models pricing by feedstock quality, technology, product, and geography, together with virgin-polymer price sensitivity.
Key Coverage
- €/tonne feedstock and output economics
- Pyrolysis-oil and recycled-monomer pricing
- Circular-polymer premiums
- Energy and preprocessing costs
- Gross-margin sensitivity
- Virgin-polymer price correlation
- Regional pricing differentials
Can Europe Convert Its Large Plastic-Waste Pool into a Commercial-Scale Chemical-Recycling Supply?
Europe generated approximately 42.5 Mt of plastic waste in 2022, while only around one-fifth of the waste stream was recycled, indicating a substantial pool of material that remains outside effective recycling pathways. Against this backdrop, Europe’s chemical-recycling operating base of approximately 289 ktpa represents only about 0.7% of total plastic-waste generation, highlighting a pronounced gap between potential feedstock availability and actual chemical-recycling throughput. Our analysis indicates that the European market is not fundamentally constrained by the volume of plastic waste available; rather, the critical bottleneck is the conversion of heterogeneous waste into a consistent, technically suitable, and economically viable feedstock stream.
In our view, feedstock quality and availability will become a more important competitive differentiator than nominal plant capacity as the market scales. Mixed post-consumer plastics require collection, sorting, preprocessing, and contaminant removal before they can reliably enter pyrolysis, depolymerization, or other chemical-conversion processes. This creates a potential capacity-utilization risk for projects that secure headline-scale plants without equally robust feedstock infrastructure. We believe long-term feedstock agreements, advanced sorting capability, and proximity to concentrated waste streams are therefore likely to become important sources of competitive advantage, particularly as multiple projects compete for the same suitable waste fractions. The strategic implication is that the next phase of European chemical-recycling growth will be determined less by announced capacity and more by the ability to achieve sustained utilization and predictable conversion yields.
The full analysis quantifies the waste-to-capacity gap by country, technology, and feedstock type, including operating versus planned capacity, potential supply deficits, plant utilization, commissioning schedules, and regional feedstock availability. It further evaluates the implications of preprocessing requirements, collection economics, regional imbalances, and import/export flows to identify where additional sorting, aggregation, or chemical-recycling capacity could be commercially justified. The assessment also distinguishes theoretical waste availability from technically addressable feedstock, providing a more realistic view of the volume that can ultimately support chemical-recycling facilities.
The underlying intelligence can also be structured as a granular feedstock and capacity database, tracking country, waste stream, polymer type, annual waste generation, technically addressable feedstock, recycling route, operating capacity, planned capacity, commissioning status, utilization, preprocessing requirements and capacity additions. Such a dataset would allow users to filter and benchmark European markets by feedstock availability, technology and capacity gap, complementing the strategic analysis with facility- and country-level quantitative intelligence.
Value Chain & Supply Chain - Value Is Shifting Toward Feedstock Control and Integrated Chemical Conversion
The value chain extends from municipal and commercial waste collection through sorting, washing, and preprocessing to chemical conversion, purification, upgrading, polymerization, and final material sales.
The most strategically valuable positions are increasingly those that connect multiple stages. Integrated players can reduce feedstock risk, optimize process yields and place circular feedstocks directly into existing crackers or polymer assets. Technology licensors can capture value through proprietary reactors, catalysts and process know-how, while waste-management specialists control critical input streams.
Key Coverage
- Feedstock collection and aggregation
- Sorting and preprocessing
- Conversion technologies
- Refining/upgrading
- Steam-cracker integration
- Polymer production
- Certification and traceability
- Margin pools and bottlenecks
Which Technologies Are Moving Chemical Recycling From Pilot-Scale Demonstration Toward Commercially Integrated Processing?
Europe’s chemical-recycling technology landscape is shifting from a single-technology development model toward a broader portfolio of process routes, with pyrolysis currently accounting for the largest share of the project pipeline. However, depolymerization, dissolution, enzymatic recycling and gasification address different feedstock and product requirements: depolymerization can selectively recover monomers from suitable polymers, dissolution can retain polymer-chain value, enzymatic processes are particularly relevant to PET, while gasification can accommodate broader waste streams but requires more extensive downstream integration. Our analysis indicates that technology leadership is therefore becoming increasingly feedstock- and application-specific rather than determined by project count alone.
Our assessment is that commercial competitiveness will increasingly depend on process economics and integration performance rather than the underlying recycling route in isolation. Yield, energy intensity, contaminant tolerance, product purification requirements and plastic-to-plastic conversion rates directly influence operating economics and the ability to produce consistent recycled feedstocks. In our view, integration with existing petrochemical and polymer infrastructure is becoming a critical differentiator, because technologies capable of converting difficult waste streams into specification-grade outputs while leveraging established downstream assets can potentially reduce infrastructure requirements and improve commercialization economics. This also suggests that reactor design, catalysts, enzymes and purification systems will become increasingly important sources of technology differentiation as projects progress from demonstration to larger-scale deployment.
The full report benchmarks the European technology landscape across technology maturity, reactor configuration, catalysts and enzymes, conversion yields, energy intensity, product quality, purification requirements, patent activity, commercial demonstration status and technology-licensing models. The analysis distinguishes technologies by feedstock compatibility and commercial readiness, enabling assessment of where each route is most technically and economically relevant and where scale-up, contamination or downstream-integration constraints could limit deployment.
The underlying intelligence can also be structured as a technology-level database, tracking technology type, target polymer/feedstock, process configuration, capacity, conversion yield, plastic-to-plastic yield, energy intensity, contaminant tolerance, product output, commercial demonstration stage, patents, licensing status and project geography. This enables users to filter and benchmark technologies by technical performance, maturity and application, complementing the strategic assessment with granular innovation and commercialization intelligence.
Regulation & Sustainability - 2026 Marks a Material Change in the Regulatory Recognition of Chemical Recycling
A major regulatory milestone occurred in 2026 when European rules established calculation, verification, and reporting provisions for recycled plastic content in single-use beverage bottles that explicitly accommodate chemical recycling through mass-balance accounting. The framework requires facility-level accounting and verification, providing a clearer mechanism for chemically recycled material to contribute to recycled-content targets.
The Packaging and Packaging Waste Regulation further increases structural demand for recycled content. The regulatory environment is therefore transitioning from uncertainty over whether chemical recycling can qualify toward more detailed questions concerning allocation, traceability, certification, environmental performance, and eligible feedstocks.
Key Coverage
- PPWR recycled-content requirements
- Single-use plastics rules
- Mass-balance methodology
- Certification and traceability
- Food-contact requirements
- Carbon-accounting implications
- Waste-shipment restrictions
- Sustainability benchmarking
Competitive Landscape - Europe Is Becoming a Race Between Integrated Chemical Platforms, Technology Specialists and Feedstock Owners
The competitive structure is unusually fragmented because the market combines waste management, recycling technology, petrochemicals and polymer manufacturing. No single business model has yet emerged as dominant.
Integrated chemical companies possess downstream crackers, polymer assets and customer relationships. Technology specialists compete through proprietary pyrolysis, depolymerization or enzymatic processes. Waste-management companies provide feedstock access and sorting infrastructure, while emerging recyclers seek to commercialize standalone facilities.
The central competitive question is shifting from “whose technology works?” to “whose technology can achieve high utilization with secure feedstock, bankable offtake and acceptable regulatory economics?”
The latest European project mapping shows the scale of the opportunity and the competitive risk simultaneously: 2.8 Mtpa of planned capacity versus only 289 ktpa operating, with pyrolysis representing the largest development pathway.
Tentative Leading Company Universe - 22 Companies Shaping the European Market
| # | Company | Headquarters | Market Position | Core Strength | Major Applications / Segments |
| 1 | BASF | Germany | Integrated chemical leader | Mass-balance integration, ChemCycling | Packaging, automotive, electronics |
| 2 | LyondellBasell | Netherlands/US | Integrated polymer producer | MoReTec catalytic recycling | PE/PP, packaging |
| 3 | TotalEnergies | France | Integrated petrochemical platform | Advanced recycling integration | Packaging, polymers |
| 4 | Repsol | Spain | Integrated chemicals/energy | Chemical recycling and gasification | Polyolefins, circular chemicals |
| 5 | OMV | Austria | Refinery-integrated recycler | ReOil pyrolysis | Mixed plastics |
| 6 | Borealis | Austria | Polyolefin/circular-materials player | Recycling integration | PE/PP |
| 7 | SABIC | Saudi Arabia/Europe | Global polymer producer | Advanced-recycled polymers | Packaging, healthcare |
| 8 | INEOS | UK | Integrated chemicals | Circular polymer/feedstock platform | Packaging, polymers |
| 9 | Eastman | US/Europe | Molecular-recycling specialist | Polyester depolymerization | PET/polyester |
| 10 | Veolia | France | Waste-management leader | Feedstock and recycling infrastructure | Mixed plastics |
| 11 | Plastic Energy | Spain | Pyrolysis specialist | Mixed-plastic conversion | Packaging |
| 12 | Quantafuel | Norway/Denmark | Pyrolysis specialist | Mixed-plastic pyrolysis | Circular feedstock |
| 13 | Pryme | Netherlands | Emerging pyrolysis producer | Commercial-scale pyrolysis | Mixed plastics |
| 14 | Mura Technology | UK | Advanced-recycling specialist | Hydrothermal liquefaction | Mixed plastics |
| 15 | BlueAlp | Netherlands | Technology/licensing specialist | Pyrolysis technology | Mixed plastics |
| 16 | Xycle | Netherlands | Emerging recycler | Pyrolysis | Difficult-to-recycle plastics |
| 17 | CARBIOS | France | Enzymatic specialist | PET biorecycling | PET/textiles |
| 18 | Ioniqa | Netherlands | Depolymerization specialist | PET molecular recycling | Polyester |
| 19 | Agilyx | Norway/US | Chemical-recycling technology | Polystyrene/chemical recycling | PS and plastics |
| 20 | Indaver | Belgium | Waste-management/chemical recycling | Advanced sorting/depolymerization | Mixed plastics |
| 21 | ReNew ELP | UK | Commercial-scale recycler | Hydrothermal processing | Mixed plastics |
| 22 | Enval | UK | Specialized recycling technology | Difficult flexible packaging | Laminates/flexible plastics |
This is a tentative market universe, not a numerical ranking. The full competitive database evaluates these companies by European capacity, operating status, technology, feedstock access, polymer exposure, customer relationships and strategic investment.
Market Share & Competitive Ranking - Capacity and Integration Are More Reliable Indicators Than Reported Revenue
Public company disclosures do not provide a consistent definition of “chemical recycling revenue,” making precise company-level revenue shares difficult to validate. The market therefore requires a dual competitive-share framework: operating chemical-recycling capacity share and commercial circular-polymer/feedstock exposure.
The current European operating base is sufficiently fragmented that no individual participant can be treated as controlling the market. The more meaningful competitive distinction is between companies with operating assets, companies with projects under construction, and companies whose principal exposure is technology, licensing or downstream offtake.
The full analysis therefore calculates company shares using standardized capacity definitions and separately tracks announced, FID-approved, construction-stage, commissioning and operating capacity to prevent pipeline projects from inflating competitive share.
Competitive Benchmarking - Integration, Feedstock and Downstream Polymer Access Create the Strongest Structural Advantages
The competitive benchmark evaluates companies across revenue exposure, operating capacity, technology maturity, feedstock security, polymer integration, geography, customer access, R&D, sustainability credentials and M&A activity.
Integrated chemical players generally possess advantages in downstream upgrading and polymer sales, while technology specialists can differentiate through process efficiency and licensing. Waste-management companies have stronger control over collection and sorting, while newer recyclers can move faster but typically face greater financing and scale-up risk.
A particularly important KPI is circular-feedstock-to-polymer integration: the ability to transform waste into an intermediate and then monetize it through existing chemical assets rather than relying solely on standalone recycled-oil sales.
Product Portfolio Benchmarking - Broad Chemical Platforms Compete With Specialized Circular-Material Producers
Portfolio breadth ranges from recycled oils and chemical intermediates to circular PE, PP, PET, PS and specialty polymers.
Integrated producers increasingly offer circular versions of existing polymer families through mass balance, allowing customers to maintain established processing equipment and specifications. Technology specialists instead compete through the quality and consistency of their recycled feedstock.
The resulting portfolio white space lies in high-purity recycled polymers for food contact, healthcare, electronics and other applications where mechanical recyclate cannot consistently meet specifications.
Technology & Innovation Benchmarking - Yield, Product Quality and Energy Intensity Are Emerging as the Critical KPIs
Technology differentiation is increasingly measurable through plastic-to-plastic yield, energy requirements, contamination tolerance and product quality.
One integrated catalytic platform reports more than 80% plastic-to-plastic yield under defined feedstock conditions, while its first commercial-scale European facility is designed for 50 ktpa of mixed-plastic waste.
Other platforms are pursuing molecular recycling of polyester, enzymatic PET recycling, hydrothermal processing and refinery-integrated pyrolysis. The full benchmark compares technology readiness, patent position, demonstration history, plant economics, licensing model and scale-up record.
Application Competitive Benchmarking - Packaging Is the Volume Pool, but High-Purity Applications Drive Premium Economics
Packaging remains the principal addressable application because it generates the largest volume of difficult-to-recycle plastic waste and faces explicit recycled-content requirements.
Food-contact packaging is strategically important because chemically recycled material can potentially deliver virgin-like polymer characteristics after appropriate purification and repolymerization. Automotive, healthcare and electronics offer smaller volumes but potentially higher value per tonne because qualification requirements and material-performance standards create stronger barriers to substitution.
Geographic Competitive Landscape - Germany, France, Spain, the Netherlands, the UK and Benelux Form the Core Industrial Cluster
Germany is estimated to represent approximately USD 1.17 billion of chemical-recycling market revenue in 2025, while the Netherlands, France, Spain, Belgium, Austria, the UK and Nordic countries provide important combinations of petrochemical infrastructure, waste availability and technology development.
Geographic competitiveness is increasingly determined by proximity to waste-feedstock pools, ports, refineries, steam crackers, polymer plants and customers rather than waste generation alone.
Manufacturing & Capacity Benchmarking - The Pipeline Is Large, but Project Execution Is the Competitive Filter
Operating European capacity of approximately 289 ktpa is dwarfed by the approximately 2.8 Mtpa development pipeline.
Individual projects demonstrate the emerging scale. A 16 ktpa refinery-integrated pyrolysis facility is operating in Austria; a 15 ktpa advanced recycling facility began production in France in 2026; and a German catalytic facility is designed for 50 ktpa.
Capacity benchmarking therefore emphasizes actual operating status, utilization, construction progress, feedstock contracts and downstream offtake rather than announced nameplate capacity alone.
Customer & Channel Benchmarking - Long-Term Offtake and Certification Are Becoming Core Competitive Assets
Customers include polymer converters, packaging producers, consumer brands, automotive manufacturers, healthcare suppliers and chemical distributors.
Purchasing decisions increasingly combine price, recycled-content eligibility, certification, carbon footprint, polymer performance, traceability and supply reliability. Long-term contracts can reduce project-financing risk, while mass-balance certification allows circular feedstocks to enter established chemical production systems without redesigning downstream manufacturing.
Strategic Developments - Europe Is Moving Toward Integrated Circular-Feedstock Ecosystems
Recent developments illustrate the transition from pilot projects to industrial integration. TotalEnergies launched France's first advanced plastics recycling plant in 2026 at 15 ktpa, using pyrolysis to process difficult-to-recycle household plastic waste.
OMV started a 16 ktpa ReOil facility in Austria and continues to evaluate larger-scale expansion, while LyondellBasell is developing its 50 ktpa MoReTec-1 facility in Germany.
The strategic direction is clear: future projects increasingly combine waste sourcing, sorting, chemical conversion and existing petrochemical assets.
M&A Landscape - Consolidation Is Shifting Toward Technology, Feedstock and Operating Assets
M&A and strategic investment are increasingly focused on acquiring technology capability and securing feedstock rather than simply adding recycling tonnage.
A notable recent transaction involved Borealis transferring its majority stake in Renasci to BlueAlp while acquiring a 10% stake in BlueAlp, strengthening the technology relationship and licensing platform.
The full M&A analysis tracks acquisitions, minority investments, JVs, technology licensing, project financing and strategic offtake arrangements across Europe, with particular emphasis on transactions that provide access to technology IP, feedstock, operating assets or downstream polymer demand.
Company Profiles - Financial, Operational and Strategic Intelligence Across the Leading Universe
Detailed profiles cover the 22 companies identified above across:
- Headquarters, ownership and corporate structure
- Total revenue and relevant business exposure
- Chemical-recycling revenue where disclosed
- Operating and planned capacity
- Technology platform
- Feedstock strategy
- Product portfolio
- Customer/application exposure
- European manufacturing footprint
- R&D and patents
- Capital expenditure
- Partnerships and JVs
- M&A
- Commercialization status
- Strategic strengths and vulnerabilities
The analysis explicitly separates company-wide financial performance from market-relevant exposure, avoiding the common error of attributing the entire revenue of diversified chemical groups to chemical recycling.
Company Strategic Positioning - Scale, Technology, Feedstock and Integration Define Distinct Competitive Archetypes
The market is best understood through qualitative strategic archetypes rather than a single competitive score.
Market Leaders combine industrial scale with polymer and chemical infrastructure. Technology Leaders possess differentiated conversion processes or intellectual property. Scale Leaders are developing large commercial plants. Regional Leaders benefit from localized feedstock and infrastructure.
Application Specialists focus on technically demanding polymer streams such as PET or flexible packaging. Emerging Challengers are attempting to establish first commercial-scale assets.
The strategic positioning framework evaluates each company across growth, technology maturity, capacity, customer access, geography, feedstock security, integration and investment commitment.
Opportunity & White-Space Analysis - The Largest Untapped Opportunity Is the Conversion of Difficult Waste Into High-Value Circular Polymers
The European opportunity extends well beyond construction of recycling plants.
The largest white spaces include mixed polyolefin waste, multilayer flexible packaging, hard-to-recycle polyester, contaminated post-consumer streams, regional feedstock aggregation and high-purity circular polymers.
The approximately 2.8 Mtpa development pipeline provides a useful upper-bound indicator of potential near-term infrastructure expansion, while the much smaller operating base highlights the execution gap.
Additional opportunities exist in sorting, preprocessing, technology licensing, certification, waste aggregation, circular-polymer distribution and integrated refinery/chemical sites.
Industry Structure - Competitive Rivalry Is High, While Feedstock and Technology Create Entry Barriers
| Force | Assessment | Market-specific evidence |
| Supplier power | Medium-High | Suitable post-consumer feedstock is difficult to aggregate consistently |
| Buyer power | Medium-High | Large polymer converters and brand owners can demand certification and price competitiveness |
| Threat of new entrants | Medium | Technology development is accessible, but commercial-scale plants require substantial capital and qualification |
| Threat of substitutes | High | Mechanical recycling, virgin resin, incineration and alternative materials compete for feedstock and demand |
| Competitive rivalry | High | Numerous technologies and projects compete for limited high-quality feedstock and long-term offtake |
The full report quantifies these forces by technology, geography, feedstock and customer segment.
PESTLE Analysis - Regulation and Industrial Economics Will Determine How Much of the Pipeline Becomes Reality
- Political: circular-economy policy and industrial competitiveness are accelerating investment.
- Economic: virgin-polymer prices, European energy costs, financing rates and recycled-material premiums directly affect project returns.
- Social: pressure to reduce plastic pollution increases demand for circular solutions.
- Technological: reactor efficiency, catalysts, enzymes, sorting and purification determine commercial viability.
- Legal: recycled-content rules, mass-balance accounting, certification and waste-shipment requirements are becoming increasingly material.
- Environmental: carbon intensity, waste diversion and lifecycle performance determine the sustainability case for different recycling routes.
Market Attractiveness - The Highest Potential Lies Where Regulatory Need, Feedstock Availability and Existing Chemical Infrastructure Intersect
The most attractive market configurations are those combining large difficult-to-recycle waste streams, strong recycled-content requirements, established petrochemical infrastructure and customers willing to pay for certified circular materials.
Germany and Benelux benefit from industrial integration; France and Spain offer major project activity; the UK has a significant technology-development ecosystem; and Austria provides an example of refinery-integrated chemical recycling.
The opportunity is therefore highly localized: a theoretically attractive country may become less competitive if feedstock logistics, energy economics or downstream integration are unfavorable.
Future Outlook - The Market Is Moving From Announcements to Bankability
By 2030-2035, the European market could evolve from a sub-0.3 Mtpa operating-capacity base toward several million tonnes of annual processing capacity if a meaningful proportion of the announced pipeline reaches final investment decision, construction and stable operation. Current market-revenue estimates imply approximately USD 13.6 billion by 2035, but physical throughput will depend heavily on project execution and utilization.
- Base case: selective project commercialization, continued regulatory support and gradual expansion of integrated pyrolysis/depolymerization capacity.
- Upside case: faster mass-balance adoption, strong recycled-content premiums, lower energy costs and successful commissioning of a larger share of the pipeline.
- Downside case: weak virgin-polymer pricing, high European operating costs, project cancellations, feedstock shortages or regulatory constraints on eligible recycled content.
- The next competitive phase is therefore likely to favor companies able to secure feedstock + technology + financing + offtake + regulatory eligibility simultaneously.
Key Strategic Questions Addressed
- What is the current revenue and physical capacity of Europe's chemical recycling market?
- How large is the gap between operating and announced capacity?
- Which chemical-recycling technologies are achieving commercial scale?
- Which polymer waste streams offer the strongest economic opportunity?
- How much suitable feedstock is actually available for chemical recycling?
- What price premium is required for circular polymers to compete with virgin resin?
- How will recycled-content requirements reshape European demand?
- Which countries offer the strongest combination of feedstock, infrastructure and customers?
- Which companies control operating capacity versus project pipeline capacity?
- Which players possess the strongest technology, feedstock and downstream integration?
- Where are the most important capacity expansions and commercial-scale projects?
- Which partnerships, JVs and acquisitions are changing the competitive structure?
- Where are the largest white spaces across technology, application and geography?
- What proportion of announced European capacity is likely to become commercially operational?
- Which technologies, business models and application segments are positioned to capture the next generation of circular-material profit pools?
Top Key Companies
- BASF
- LyondellBasell
- TotalEnergies
- Repsol
- OMV
- Borealis
- SABIC
- INEOS
- Eastman
- Veolia
- Plastic Energy
- Quantafuel
- Pryme
- Mura Technology
- BlueAlp
- Xycle
- CARBIOS
- Ioniqa
- Agilyx
- Indaver
- ReNew ELP
- Enval
Market Report Segmentation
By Technology
- Pyrolysis
- Catalytic Pyrolysis
- Thermal Pyrolysis
- Microwave-Assisted Pyrolysis
- Other Pyrolysis Technologies
- Gasification
- Conventional Gasification
- Advanced Gasification
- Plasma Gasification
- Depolymerization
- PET Depolymerization
- Polyamide Depolymerization
- Other Polymer Depolymerization
- Solvolysis
- Glycolysis
- Methanolysis
- Hydrolysis
- Other Solvolysis
- Dissolution
- Selective Dissolution
- Solvent-Based Purification
- Enzymatic Recycling
- PET Enzymatic Recycling
- Other Polymer Enzymatic Recycling
- Hydrothermal Processing
- Hydrothermal Liquefaction
- Other Hydrothermal Processes
- Other Chemical Recycling Technologies
By Polymer / Feedstock
- Polyethylene (PE)
- HDPE
- LDPE
- LLDPE
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene (PS)
- Polyvinyl Chloride (PVC)
- Polyamide (PA)
- Mixed Polyolefins
- Mixed Plastic Waste
- Multilayer Plastics
- Other Plastics
By Feedstock Source
- Post-Consumer Plastic Waste
- Packaging Waste
- Household Waste
- Commercial Waste
- Industrial Waste
- Post-Industrial Plastic Waste
- Municipal Solid Waste
- Flexible Packaging Waste
- Rigid Packaging Waste
- Automotive Plastic Waste
- Electronic Plastic Waste
- Textile Waste
- Other Plastic Waste
By Output
- Recycled Polymer
- Circular PE
- Circular PP
- Circular PET
- Circular PS
- Recycled Monomers
- Pyrolysis Oil
- Circular Hydrocarbons
- Chemical Intermediates
- Syngas
- Other Recycled Outputs
By Application
- Packaging
- Food Packaging
- Beverage Packaging
- Flexible Packaging
- Rigid Packaging
- Films
- Bottles and Containers
- Caps and Closures
- Automotive
- Electronics & Electrical
- Construction
- Textiles
- Healthcare & Medical
- Consumer Goods
- Industrial Products
- Agriculture
- Other Applications
By End-Use Polymer
- Polyethylene
- Polypropylene
- PET
- Polystyrene
- Engineering Plastics
- Specialty Polymers
- Other Polymers
By Business Model
- Integrated Chemical Recycling
- Standalone Recycling Plants
- Technology Licensing
- Joint Ventures
- Waste-to-Chemical Partnerships
- Toll Processing
- Circular Feedstock Supply
- Recycling-as-a-Service
By Sales Channel
- Direct Sales
- Long-Term Offtake Agreements
- Polymer Producers
- Chemical Distributors
- Waste Management Companies
- Trading Companies
- Other Channels
A Seven-Phase Framework
Our methodology is designed to be universally applicable across commodity chemicals, specialty chemicals, petrochemicals, construction chemicals, coatings, electronic chemicals, industrial gases, agrochemicals, water treatment chemicals, and performance materials. Each phase builds upon the last, creating a layered validation structure that minimizes estimation error and maximizes analytical confidence.
The framework ensures comprehensive market coverage, robust cross-validation, and reliable long-term forecasting — producing market estimates that withstand scrutiny from investors, regulators, and corporate strategy teams.

Seven-Phase Framework — Analytical Effort Distribution
Relative analytical effort allocated across each phase of the Chemicals & Materials research framework

Phase 1 - Secondary Research: Establishing the Foundation
Secondary research collects and evaluates publicly available information from authoritative sources, establishing the foundational understanding of market structure, value chain dynamics, competitive landscape, and end-use demand patterns. Every source is evaluated for credibility, recency, geographic relevance, and methodological soundness before inclusion.
Industry Associations
Sources include ACC, CEFIC, ICCA, JCIA, CPCIF, and SOCMA providing production volumes, consumption trends, capacity developments, and sustainability initiatives.
Company Disclosures
Annual reports, investor presentations, earnings transcripts, and regulatory filings reveal product portfolios, manufacturing footprints, capacity expansions, and revenue segmentation.
Government Databases
National statistical offices, customs authorities, environmental agencies, and industrial production databases provide verified statistics on output, trade flows, and regulatory compliance.
Trade Databases
UN Comtrade, ITC, Eurostat, and national customs authorities enable assessment of global product movement, import dependency, and export competitiveness across regions.
Our Secondary Research Sources
- Ministry of Chemicals and Fertilizers
- European Chemicals Agency
- United States Department of Energy
- Ministry of Industry and Information Technology
- Ministry of Economy Trade and Industry
- Ministry of Trade Industry and Energy
- National Institute of Standards and Technology
- Council of Scientific and Industrial Research
- Fraunhofer Society
- National Institute for Materials Science
Phase 2 — Supply-Side Assessment: Mapping Production Capabilities
Production Capacity Analysis
All major manufacturers are assessed for existing installed capacity, planned additions, expansions, new plant announcements, and technology adoption — mapped at global, regional, and country levels.
Capacity Utilization Adjustment
Installed capacity is adjusted using utilization rates based on demand conditions, feedstock availability, plant operating rates, maintenance schedules, and regulatory restrictions.
Manufacturer Revenue Analysis
Product-specific revenues, segment-level performance, regional distribution, average selling prices, and margin trends are evaluated to establish market value estimates.
Supply-Side Assessment — Capacity vs. Effective Production by Region
Illustrative comparison of installed capacity vs. effective production volume (after utilization rate adjustment) across major regions

Phase 3 — Demand-Side Assessment: Quantifying Chemical Consumption
Demand-side analysis quantifies chemical consumption across industries, applications, and geographies — identifying where and how chemicals are consumed throughout the value chain with precision.
End-Use Industry Analysis
Chemical demand is evaluated across automotive, construction, packaging, electronics, agriculture, healthcare, consumer goods, industrial manufacturing, energy and utilities, and water treatment. Industry output, production trends, and consumption intensity are analyzed to determine demand patterns.
Consumption Modeling
Demand is estimated using measurable indicators: kilograms per vehicle, kilograms per square meter of construction, dosage per cubic meter of water treated, kilograms per hectare of agricultural land, and kilograms per ton of manufactured products. Consumption factors are validated through industry publications and primary interviews.
Application Analysis
The market is segmented by application area to understand product performance requirements, formulation trends, technology adoption, customer preferences, and regulatory requirements improving demand accuracy and segmentation granularity.
Demand-Side Assessment — End-Use Industry Demand Distribution
Illustrative distribution of chemical & materials demand across key end-use industries

Phase 4 - Trade Flow Analysis: Balancing Regional Supply and Demand
Trade flow analysis reconciles regional supply and demand estimates through import and export data, identifying net supply positions, regional dependencies, and market imbalances. It serves as an independent validation layer that tests the consistency of supply-side and demand-side estimates.
Import Analysis
Import data is evaluated to determine volumes, source countries, product dependency, regional supply gaps, and pricing trends — identifying markets that rely heavily on external supply and where domestic production is insufficient to meet demand.
Export Analysis
Export assessments reveal production surplus, export competitiveness, regional manufacturing strength, and global market participation. Export patterns also help validate domestic production estimates and identify net exporting regions.
Apparent Consumption Model
Regional consumption is assessed using the standard apparent consumption formula:
Results identify net importing regions, net exporting regions, regional deficits, and surpluses — serving as an independent validation of supply and demand estimates.
Trade Flow Analysis — Net Supply Position by Region
Illustrative apparent consumption vs. domestic production across major regions — positive gap indicates net import dependency

Phase 5 — Primary Research: The Critical Validation Layer
Primary research tests and refines findings from secondary research through direct engagement with industry participants across the supply chain, demand side, and expert community. It captures intelligence that no database or published report can provide — the real-world experience of manufacturers, buyers, and specialists operating in the market.

Supply-Side Interviews
Conversations with chemical manufacturers, raw material suppliers, contract manufacturers, technology providers, and plant operators cover production trends, capacity utilization, pricing developments, technology shifts, and competitive dynamics.

Demand-Side Interviews
Engagement with OEMs, industrial consumers, procurement managers, distributors, formulators, and end-use manufacturers focuses on consumption trends, purchasing behavior, product substitution, demand outlook, and emerging applications.

Industry Expert Consultations
Additional interviews with industry consultants, independent experts, regulatory specialists, technical professionals, and research institutions provide deeper market context and validate key analytical assumptions.
Focus Areas of Primary Research:
Market Size & Forecast Validation
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.Supply Chain & Value Chain Assessment
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.Production & Capacity Analysis
Manufacturing capacity, utilization rates, expansion projects, plant investments.Pricing & Cost Structure Analysis
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.Competitive Landscape Assessment
Volume and value estimates confirmed to be fully consistent with one another before publicationInterview Volume by Market Scope
| Study Scope | Number of Interviews |
|---|---|
| Niche Market | 20 – 30 |
| Mid-Sized Market | 30 – 50 |
| Global Market | 50 – 80 |
| Highly Fragmented Market | 80 – 120 |
Interview Details:
Category : Manufacturers, Suppliers, Distributors, End Users, Experts/Associations
Average Duration : 30–60 Minutes
Interview Mode : Video calls, telephonic interviews, expert consultations
Interview Format : Structured / Semi-Structured questionnaire
Focus Areas of Primary Research:
Market Size & Forecast Validation :
Revenue estimates, volume consumption, growth rates, forecast assumptions, regional demand.
Supply Chain & Value Chain Assessment :
Raw material sourcing, supply chain challenges, distribution networks, procurement practices.
Production & Capacity Analysis :
Manufacturing capacity, utilization rates, expansion projects, plant investments.
Pricing & Cost Structure Analysis :
Product pricing trends, feedstock costs, energy costs, margin pressures, pricing outlook.
Competitive Landscape Assessment :
Market share, competitor positioning, strategic initiatives, partnerships, acquisitions.
Primary Research — Stakeholder Coverage by Category
Distribution of interview respondents across stakeholder categories (% share from PPT data)

Primary Research — Respondent Designation Profile
Seniority breakdown of interview respondents (% share from PPT data)

Primary Research — Geographic Coverage of Interviews
Regional distribution of primary research engagement (% share from PPT data)

Phase 6 — Data Triangulation and Market Validation
No single methodology is relied upon in isolation. Multiple independent estimation approaches are combined and reconciled to ensure consistency, accuracy, and analytical defensibility. Any material deviations between approaches are investigated and adjusted through additional validation cycles.
The final market size is derived through weighted triangulation of all validated methodologies. Any material deviations between approaches are investigated and adjusted through additional validation cycles. The outcome represents the most realistic assessment of the market based on available evidence and expert confirmation ensuring that volume and value estimates are fully consistent with one another.
Triangulation Framework — Input Contribution Weight
Relative weight each sizing input contributes to the final reconciled market estimate

Phase 7 — Forecast Modeling: Projecting Future Market Evolution
Forecasting evaluates the future trajectory of the market using a combination of quantitative indicators and qualitative assessments across economic, industry, and regulatory dimensions. Rather than simple extrapolation, each driver is independently modeled and integrated into a composite forecast.
Macroeconomic Indicators
GDP growth, industrial production, manufacturing output, construction activity, consumer spending, and capital investment form the quantitative foundation of long-term demand projections. These are applied at country, regional, and global levels.
Industry Growth Drivers
Urbanization, infrastructure development, industrialization, technological innovation, sustainability initiatives, and evolving product performance requirements are assessed at regional and industry levels — capturing both structural and cyclical demand drivers.
Capacity Expansion Analysis
Announced plant expansions, new manufacturing facilities, technology upgrades, and strategic investments are evaluated to determine future supply-demand dynamics and potential market tightness or oversupply situations.
Regulatory & Sustainability
Environmental regulations, chemical safety standards, emission reduction targets, circular economy initiatives, and sustainability requirements are incorporated as they often influence product adoption rates and market growth trajectories.
Scenario Forecast Range — Indexed Market Growth (Year 1–10)
Illustrative indexed growth trajectories across Base, Optimistic, and Pessimistic scenarios over a 10-year forecast horizon

Forecast Drivers — Relative Impact Score by Category
Impact score (0–100) of each driver type on chemicals & materials market forecast




Comments
Share your thoughts, ask a question, or provide feedback about this report.